Blog Page 337

10 Points to consider before buying Property in auction

You can save a lot of money by buying a property in the auction. The property sold in the auction is generally 20-30% cheaper than the market cost. If you’re looking to buy your first home, therefore, Property Auctioneers are a great place to look if you’re struggling to buy at market value.

Navigating the property auction landscape requires a keen understanding of property auction finance. Potential buyers should proactively explore financing solutions tailored to the unique demands of auction transactions, ensuring they have the financial flexibility to seize opportunities and successfully acquire their desired assets. With careful consideration of property auction finance, participants can position themselves strategically in the competitive bidding environment.

Recently I attended a bank property auction along with my friend. It was indeed a very good experience. I was surprised that the property was sold at 40% lower than the market rate.

Many investors and property buyers get lured by the reduction in the property price and they blindly purchased the property in the auction without understanding the pitfall. I am not saying that you should not purchase property in the auction. However, you should be cautious before purchasing property in the auction.

If you are planning to purchase property in the auction this post is for you. In this post, I will explain the property auction process and also discuss points to consider before buying property in the auction.

Also Read – 10 point checklist before buying property

property auction

What is a property auction?

Property auction is the public sale of property, generally organized by the bank. A Property sold in the auction is repossessed property. When people default on paying home loan EMI three times or above bank can auction the property to recover the home loan money.

How does a property auction work?

  • Property auction is a simple process where the bank first set a minimum reserve price for the property.
  • Every participant (the bidder) needs to give EMD (Earnest Money Deposit). EMD is returned back if the property is not sold to you.
  • A bid is accepted by every bidder. This bid will be either in seal envelope or spot open bidding.
  • The property is sold to the highest bidder in the auction. If you win the bid you have to pay 25% of your bid amount to confirm the deal.

10 Points to Consider Before Buying Property in Auction

#1 Legal Disputes

Properties sold in the auction are disputed properties. Bank sells the property on “as is” basis. No legal information about the property is available. Bank does not provide access to any property documents. So, there are chances that the Title of the property is not clear and the property has been sold to the property owner more than once.

Bank does not take responsibility for any legal disputes that arise once the property is sold via auction. You need to be ready to fight a legal battle in court on your own.

#2 No factual information

The information available for the property is very limited and may not be based on fact. It is risky to purchase the property in the absence of factual information. I have come across instances where the bidder realized afterward that heavy property tax was unpaid. A bidder had no choice but to clear the dues.

Also Read – 10 mistake to avoid while making Rent Agreement 

#3 Uncertainty about No dues

You cannot ascertain that all pending dues of the property are paid by the property owner. A person who can default on EMI can default on other things also. In many cases, it is seen that utility bills, society dues, or maintenance costs are not paid for several months.

#4 No Black Money

In a property auction, you need to pay the entire money in white only. As you are directly dealing with a bank you cannot expect the bank to accept black money. You need to consider this point before buying property in the auction.

#5 No Home Loan

You cannot get a home loan on the auction property. The reason for not giving a home loan is (1) Disputed property (2) Already mortgage and NPA for the bank.

#6 Confirming party

The original borrower or defaulter should become the confirming party in your sale agreement/deed. This is to ensure that in the future he/she should not file a case in court to cancel the auction.

#7 The minimum reserve price of the property

The Minimum reserve price of the property is very important in the property auction. You should survey the market and satisfy yourself with the price of the property. The minimum reserve price should be at least 20% lower than the market price.

#8 Repairs in property

Before participating in a bid you should actually visit the property to find out the repair cost associated with the property. Check for leakage and other maintenance costs.

Also Read – RERA Act – 10 Key Feature you should know 

#9 Other costs

Look for other costs such as registration of property, stamp duty, society transfer fees, the cost of moving into a property, etc.

#10 Legal Help

You may need to involve an advocate or sought for legal help for the disputed property.

Where to look for property in the auction?

You can find detail about property auctions at the following places.

Conclusion –

You are likely to get the property at a cheaper rate in the bank auction. However, there are multiple issues and pitfalls associated with the property auction. So you need to be cautious before buying property in the auction.
10 Tips to be successful in a Job Interview

0

Finding a good job in and earning a handsome salary is a dream seen by many young individuals. It is known fact that you need to clear the job interview for getting a job. However, research reveals that more than 70% people feel anxiety, fear, and competition while facing job interview. Here are tips and tricks that will reduce your anxiety and help you to be successful in Job Interview.

Job Interview Tips

10 Tips to be successful in Job Interview

(1) Take extra care while making CV

The aim of making CV is to show your potential employer that you are the best person for the job. Your CV is the first thing which interviewer see. It should leave a very good impression to the interviewer.

Take extra care while making CV. If the interviewer does not like your CV or he/she find a silly mistake in your CV, then it can adversely impact your selection. So, make sure to be cautious when preparing the CV. You can always reach out to professionals, like CV Experts or similar other specialists that can help you curate the the CV as per your tastes.

In a majority of companies first cut short listing is done based on the CV. So, if your CV is not good you may not get shortlisting for the interview. A few tips about making a good CV are given below.

  • Your CV should look like a professional.
  • Don’t use big paragraphs. Use bullet points. It is easy for the Interviewer to read bullet points.
  • Describe your skill and job experience properly.
  • Your CV should be free from spelling mistakes.
  • Highlight the points which are relevant for the job.
  • Ask experts to carry out proofreading of your Resume.

Also Read –5 Reasons to Leave Job and Start Business Today

(2) Give importance to theoretical knowledge while preparing for the job interview

You should give importance to theoretical knowledge while preparing for the job interview. I know many incidents where people with good practical knowledge do not succeed in a job interview, as they are lacking in theoretical knowledge.

If I talk about myself I spend 60% of my interview preparation time in improving my theoretical knowledge. It gives a boost to my confidence and increases my chance of getting successful in the Job interview.

Don’t take interview casually. It is a competition where you need to prove yourself that you are the most eligible person for the job.

(3) Place yourself in the place of employer

I advise you to think like interviewer whenever you are preparing for the job interview. Place yourself in the place of the employer. Think what qualities job interviewer will be searching in the ideal candidate.
In addition to that understand skill requirement for the job position and showcase the same while you appear for the job interview. You can also hide the qualities that are not required the job.

For example: If you are going to appear for the marketing job, you should highlight your traveling hobby and if a job is for the operations you should not highlight this hobby. You should modify your CV as per job requirement. Make your CV more effective for the job.

Similarly, if you place yourself in the place of job interviewer you will come to know many things which will be helpful for cracking job interview.

(4) Make a list of frequently asked questions for the Job Interview

The majority of questions in job interviews are common. So, I advise you to make a list of frequently asked questions for the job interview and prepare for the same.

Here is a list of some most common questions asked during the job interview.

  • Tell me about yourself
  • Walk me through your CV
  • Tell us about your current job profile, what is your role?
  • Why you want to change your job?
  • Why do you want to join this company?
  • What is your strength/ weakness?
  • Why should we select you?
  • Why did you choose this specialization?
  • Why your marks are very low in XYZ exam?
  • What has been your biggest achievement till date?
  • What is your ambition in life?

In addition to that make a list of few common question related to your industry and be ready with answers.

I am not saying that you by learn by heart answers of all these questions. However, you should mentally prepare what to answer in case these questions are asked in the interview.

For example – If someone ask that, what are your strength? You will defiantly answer him/her by mentioning your strength. However, it may so happen that you will forget to mention one of your important strength. If you are well prepared it will never happen.

(5) Visualize and run job interview process in mind

Before giving any interview I visualize job interview process 2-3 times in the mind. This improves my confidence level and also helps me in facing job interview.

Starting from what to wear in the interview, what to carry, how to make a gesture, how to introduce myself I try to visualize everything. I find this technique very useful.

(6) Carryout mock drill about Job Interview

If you don’t have experience of giving job interview, it is advisable to carry out mock drill of the job interview. You can request your friend or senior to help you in conducting this mock drill. Take this activity very seriously it will defiantly make a difference and help you in bringing success for the job interview. If no one is available you can give an interview by sitting in front of the mirror.

Usually, interviewers look for common qualities like confidence, subject knowledge, suitability, and ability to work in the team while taking an interview. Make sure while practicing you express all these qualities.

(7) Give importance to nonverbal communication

In addition to verbal communication, you should give importance to nonverbal communication. Multiple things come in nonverbal communication like your body language, tone, the way you sit, eye contact, your dressing sense everything matters.

You should take care of following –

  • You should reach the interview venue on time.
  • You should wear a decent formal pair while appearing for the job interview.
  • Your voice should not be dull. Enthusiasm and confidence are required for the job interview.
  • Friendly gesture and smile is important for the job interview.
  • You should research about the company. Gather as much information as possible.

Furthermore, grooming plays a significant role in nonverbal communication. Visiting reliable salons or barbers Fitzrovia (or elsewhere) ensures you look polished and presentable. A fresh haircut, well-groomed beard, and overall neat appearance can boost your confidence and leave a lasting impression. By taking the time to care for your grooming, you demonstrate professionalism and show that you take the interview seriously.

(8) Don’t give any contradictory answer in the job interview.

The interviewer can ask any question to check your honesty. You should answer all questions carefully and honestly. You should not give any contradictory answer in the job interview.

For Example – If you have already said that this is your dream company, an interviewer might ask you in more detail about services or product offered by the company. Now if you don’t have basic knowledge about your dream company it is but obvious that you are not an honest candidate.

Also Read – Online Jobs for Students – Easy without Investment

(9) Select Job Interview language based on your comfort level

If you are expert in English and Hindi language you can skip this step. However, if you are not good at English this point could be an important point for you.

The majority of job interviews are taken in English. However, at few places where verbal communication is less important interviewer may prefer other local languages. If you are not comfortable in English you should approach interviewer and express your concern.

(10) Overcome the fear of Rejection

You should overcome the fear of rejection in the Job. Remember even the best candidate face the rejection in the Job interview. Don’t give up. Your effort will defiantly see the success.

Video – How to Crack a Job Interview?

Final thoughts –

Friends, I hope that Job interview tips given here will help you in improving your success rate for the interview.

I will be waiting for your feedback and job interview-related questions.

Personal loan or Gold loan which is best option?

personal loan

A personal loan is an option selected by many individuals in the financial crises. Another alternative of personal loan is gold loan or loan against fixed deposit. If you looking for a personal loan for your immediate cash requirement it is better to go for gold loan or loan against fixed deposit instead of a personal loan.

In this post, we will discuss key difference between these two loans and also reach to the conclusion that Gold Loan is better option compare to personal loan.

What is Personal Loan?

  • The personal loan is loan given by the bank without any collateral.
  • This loan is given by bank considering your income eligibility.
  • A personal loan can be used for any purpose including medical expense, marriage expense, home improvement, purchasing household items or to pay your credit card debt.
  • This loan is given to the salaried individual and self-employed.

Also Read – Things to remember before giving loan to friends or relative

What is Gold Loan?

  • The Gold loan is given by the bank or financial institute by taking gold as collateral.
  • The Gold loan is given based on the quantity of gold and its value.
  • The gold loan can be used for any purpose like a business, medical expense, marriage etc.
  • This loan can be given to the gold owner irrespective of profession.

What are the difference between Personal Loan and Gold Loan?

Processing Fees

The bank does not ask for any guarantor or any security deposit for the personal loan. Bank does verification of your income documents. As time and efforts are involved in this process bank will charge processing fees for the personal loan. The processing fees generally vary from 0.5% to 1% of loan amount.

In the case of Gold loan, no processing fees are charged by the NBFC (Muthoot Finance). However, the bank may charge processing fees for the gold loan. You can negotiate with the bank to waive off the processing fees on the gold loan.

Interest Rates

The interest rate applicable on the personal loan is very high compared to Gold Loan. The gold loan can be availed with 12-15% interest. However, for the personal loan, you need to pay the interest rate in the range of 18-24%. The main reason for a high-interest rate on the personal loan is no collateral requirement.

The difference in interest rate is making personal loan much more costlier compare to gold loan.

Repayment Tenure

The repayment tenure of personal loan varies from 1 year to 5 years. This means you need to repay the personal loan amount in 5 years.

However, the gold loan is available only for the shorter time duration of 12 months. So, if you are in the position to repay the loan in 12 months you can take a gold loan.

Also Read – Credit Card Loan or Personal Loan

Pre-payment Charges

A personal loan is payable with fixed EMI, spanning over fixed period of time. If you wish to do Pre-payment bank will charge you pre-payment charges. This charge varies from bank to bank. However, it is usually in the range of 1-2% of the outstanding principal amount.

In a gold loan, no pre-payment charges are applicable. You can do repayment and close the gold loan at any time.

No EMI

In the personal loan, you need to pay Fix EMI and you cannot default. You need to carry principal and interest burden throughout the loan period.

However, in the gold loan, you can have an option of NO EMI. This means you need to only pay interest amount and a principal amount can be paid at the end of loan period. This feature reduces burden on the borrower considerably.

In nutshell Gold loan gives following benefits –

  • Faster processing time as gold is given as a collateral.
  • No or very fewer documents are required.
  • The gold loan is less costly as no need to pay processing fees.
  • The interest rate is low in gold loan compare to personal loan.
  • You can avail No EMI option and reduce your burden considerably.

Personal loan or Gold loan which is best option?

Looking at the features and benefits mentioned above it can be said that that Gold Loan is Best Option compared to personal loan. Gold loan is less costly and offers multiple other benefits compare to personal loan. A comparison of a gold loan and a personal loan in graphical form is given below.

personal loan

Where to get a Gold Loan – Bank or NBFC?

You can take a gold loan from Bank or NBFC. Some of the most popular NBFC’s offering gold loan is as follows.

  • Manappuram Gold Loan
  • Muthoot Finance
  • Muthoot Fincorp

In addition to NBFC banks like HDFC Bank, ICICI Bank, Union bank of India, Bank of India etc also offers a gold loan.

NBFC are preferred choice by many individuals due to simpler documentation and faster processing. However, if you look at the security of gold and interest rate bank is a more recommended option. Gold loan is offered by the bank at much lower interest rate compared to NBFC.

Conclusion –

From above discussion, it can be concluded that Gold loan is best option compare to personal loan.

If you have idle gold parked in your locker and you have immediate requirement of cash you should contact the bank to avail gold loan instead of personal loan.

Home loan Tax benefits – Section 24, 80EE & 80C- 10 less known facts

home loan

Many of us take a home loan to buy the dream home. However, we hardly know the tax benefits associated with Home loan. In this post, I will throw light on Home loan tax benefits. I will also cover 10 less known facts which are not known to a majority of people.

Home Loan Tax Benefits

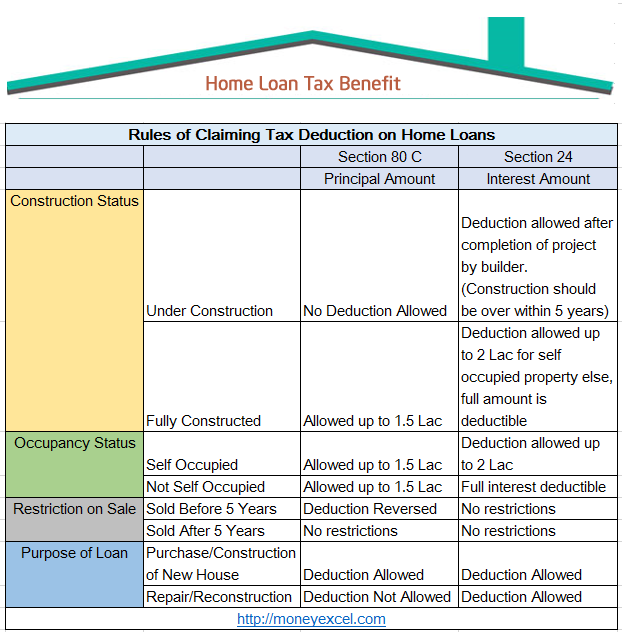
Home Loan EMI payment has two components (1) Principal (2) Interest (Section 24). You can avail tax benefit on both these components.

  • Principal – You can claim tax deduction on the Home loan principal paid by you. The limit for this deduction is 1.5 Lac (Section 80C). You can get details about principal amount paid by you from your lender.
  • Interest – You can also avail tax benefit on the interest component of the home loan. The total deduction allowed on interest component is up to 2 Lac. The condition of availing this tax benefit is owner should live in the house for which home loan is taken or house should be vacant.

Total Tax Benefit = 1.5 Lac Principal (80 C) + 2 Lac Interest (Section 24) = 3.5 Lac

Now let’s take a look at 10 less known facts about home loan tax benefit section 24.

10 Less Known facts about Home Loan Tax Benefits

First time home buyers can claim additional tax deduction of Rs 50,000 on Home Loan Interest

In budget 2016 new section 80EE is introduced for the first time home buyers. As per the new section 80EE, first time home buyers can claim an additional tax deduction of Rs 50,000 on home loan interest. This deduction is over and above tax deduction of 2 Lac under section 24 and 1.5 Lac under section 80C.

So, maximum tax benefit shall be 4 Lac per year. This new benefit is applicable under following conditions.

  • You are first time home owner.
  • No other house is owned by you.
  • The value of the loan is less than 35 lacs and property value is less than 50 lacs.
  • The loan should be sanction between 1st April 2016 and 31st March 2017.

This benefit shall be extended till the time repayment of home loan continues.

Deduction is allowed to the borrower and co-borrower

Home loan deduction on principal and interest is extended to the borrow and co-borrower both. This means if you have taken a home loan on your and your wife’s name you and your wife both can claim these tax deductions. So, effectively you and your wife both can enjoy tax benefit applicable on a home loan.

No benefit on principal payment during construction on property

As per income tax law, you can not avail any tax benefit on principal payment during the construction of the property. You are eligible for this benefit only after the project is completed and property possession is given to you.

Preconstruction period interest is also deductible in 5 equal proportion in 5 years.

You can claim home loan benefit only on the possession of the property. Any preconstruction payment towards principal cannot be claimed. However, you can claim preconstruction period interest payment once you received possession of the property. The tax deduction benefit on such interest is available equally over a period of 5 years starting from the year of possession.

Tax benefit on Home Protection Insurance premium payment

Many banks offer home protection insurance scheme. If you opt to take home protection scheme, an insurance premium paid towards this scheme can be claimed for tax deduction under section 80C. For home protection scheme sum assured and premium changes with the time.

Principal and repayment tax benefit shall be reversed if you to sell the property before 5 years.

You cannot sell the property before 5 years. If you sell the property before 5 years, all principal paid by you in last five years shall be reversed and added to your income. In addition to this, you may need to pay capital gain tax.

Loan from relative and friends is also eligible for tax benefits

You can take home loan from your friends and relatives and avail tax benefits. However, you will not get any tax benefit on the principal amount.

Let me explain, if you take home loan from your friend you can claim a tax deduction on interest paid to your friend (Under section 24). The following condition should be fulfilled in order to avail this tax benefits.

  • You need to submit proof that you have paid interest to your friend. This may be in the form of a certificate.
  • Your friend needs to show this interest income and he/she need to pay income tax on this income.

You can not avail tax benefit on principal payment under such case.

Benefit of section 80 C, section 24 and HRA

You can not avail the benefit of HRA if you are living in your own house and getting tax benefit towards section 80 c and section 24. However, if you are living in rented house despite owning your own house you can avail the benefit of section 80 C, section 24 and HRA also.

Buying multiple homes using home loan

You can purchase multiple home and avail tax benefits. The benefit under section 80 C for the principal payment shall be capped at 1.5 Lacs for all loans. The benefit under section 24 for the interest payment for the self-occupied property shall be 2 Lacs.  For the house which is given on rent, there is no limit on interest payment claim.

Stamp Duty, Registration fee, Processing Fee and Tax Deduction

In addition to principal and interest component other expenses can also be claimed for the tax benefit. These expenses include stamp duty, registration fee expenses etc. All these expenses can be claimed as tax benefit under section 80C. Any processing fees for getting home loan sanction can also be claimed for tax benefit.

home loan tax benefit

Over to you –

Hope I have clarified your doubts about home loan and tax benefits. If you have any other confusion related to home loan and tax benefit, feel free to post your query in the comment section.