Blog Page 212

Corporate Finance – What Is It, Example & Its Type

0

Corporate finance is a field of finance that deals with the financial transactions and relationships between companies and their investors. It includes everything from issuing and selling securities to mergers and acquisitions. Corporate finance professionals help companies manage their finances, ensuring they can meet their financial obligations and stay afloat during turbulent times. They also protect shareholders’ interests by making sure companies are financially sound.

Corporate finance is a highly complex field that requires a thorough understanding of financial theory and practical business experience. The best corporate finance professionals can combine these skills to provide clients with the best possible service. They also have strong analytical skills, allowing them to understand complex financial data quickly.
Corporate Finance

Corporate Finance – What Is It, Example & Its Type

Decisions related to investments:

When making corporate financing decisions, there are several factors to consider. One of the most important is the company’s financial condition. This includes things like its debt burden, its cash flow, and its ability to pay back its debt. Another critical factor is the company’s ability to generate future income. This includes things like its marketability, its profitability, and its growth potential.

Finally, the company’s credit score is essential – especially if it’s looking to borrow money. These factors play a role in determining the company’s eligibility for corporate financing.

Some examples related to corporate financing can be deciding which new projects you should pursue and which tasks need scrapping. Also important is to find out which type of accounts you can utilize better for your business. Opening a current account is an excellent choice for such companies.

Financing decisions:

Corporate financing decisions help us determine a business’s financial needs. Suppose you have selected a project that needs to be pursued. Now lay the vital question, where will the money come from? Will you depend on cash at hand, will you be issuing debt, or will you rely on equity? If you choose a debt option, then you will have to pay back a fixed sum to the lender regardless of the success or failure of the project. If you choose equities, then a certain percentage will have to be given to the investor.

Types Of Corporate Finance

Below are some types of corporate finance

Equity Financing:

Equity financing is a type of financing that allows businesses to raise money by issuing shares to investors. This financing is often used in startups and small companies that need additional capital to grow and expand.

Equity financing can be used to finance various projects, including the acquisition of new businesses, the expansion of an existing business, the development of new products or services, and the purchase of property or other assets. Equity financing can be risky, but it can also be an enriching experience for both the business and the investors.

Angel Investing:

Angel investing is a venture capital investment strategy that uses private investors to finance startup companies. Typically, angel investors are experienced business people willing to invest small amounts of money in early-stage companies. This helps startups gain the financial stability and resources they need to grow and eventually become successful.

Angel investing is a great way to invest in a company before it becomes publicly traded. It can offer the potential for significant returns. If you’re patient and invest in the right company, then you could make a lot of money. If you’re interested in investing in startup companies, then angel investing is the perfect strategy for you.

IPO:

An IPO is a type of public offering – companies raise money by selling shares to the public. IPOs are often the biggest and most important event in a company’s history. It can be an inspiring time for shareholders as they get to invest in a new company at an early stage. For the company itself, an IPO can be a very positive experience – it can help to raise awareness and boost the stock price. IPOs are an excellent way for companies to raise money, and they’re worth considering if you’re interested in investing in a new company.

LIC New Tech Term Plan – LIC Term Plan Review 

LIC has launched LIC New Tech Term Plan (Table 954). The earlier launched tech term plan by LIC is now closed. LIC’s New Tech-Term is a Non-Linked, Non-participating, Individual, Pure Risk Premium Life Insurance Plan.

LIC New Tech Term plan is an online-only plan you can purchase from LIC’s website. You must be keen to know the difference between the old tech term plan and LIC’s New Tech Term Plan. So, here is a complete post about key features, eligibility, benefits, and a review of LIC’s New Tech Term Plan.

LIC Tech Term Plan

Key Features of LIC New Tech Term Plan

  • LIC New Tech Tem is a pure Online Term Life Insurance Plan.
  • The minimum Sum assured for this plan is 50 Lakh with no upper limit on Sum assured.
  • Flexibility to choose from two benefit options: Level Sum Assured and Increasing Sum Assured.
  • Flexibility to choose from Single Premium, Regular Premium, and Limited Premium Payment 
  • Choose the Policy Term/Premium Paying Term 
  • Opt for payment of benefits in installments. 
  • Special rates for women. 
  • The benefit of an attractive High Sum Assured Rebate. 
  • Two categories of premium rates namely (1) Non-Smoker rates and (2) Smoker rates.  
  • Option to enhance coverage by opting for Accident Benefit Rider on payment of additional premium for the rider benefit.

Benefits payable under an in-force policy shall be as under

#1 Death Benefit

The death benefit payable on the death of the life assured during the policy term after the date of commencement of risk but before the date of maturity provided the policy is in force and the claim is admissible shall be “Sum Assured on Death”.

For Regular premium and Limited premium payment policies, “Sum Assured on Death” is defined as the highest of:

  • 7 times of Annualised Premium; or
  • 105% of “Total Premiums Paid” up to the date of death; or
  • Absolute amount assured to be paid on death. For a Single premium policy, “Sum Assured on Death” is defined as the higher of:
  • 125% of Single Premium.
  • Absolute amount assured to be paid on death.

Where,

i. “Annualized Premium” shall be the premium payable in a year chosen by the policyholder, excluding the taxes, rider premiums, underwriting extra premiums, and loadings for modal premiums, if any, and

ii. “Total Premiums Paid” means the total of all the premiums received, excluding any extra premium, any rider premium, and taxes.

iii. Absolute amount assured to be paid on death shall depend on the Death Benefit Option chosen at the time of taking this policy and is as under:

Option I: Level Sum Assured

The absolute amount assured to be paid on death shall be an amount equal to Basic Sum Assured, which shall remain the same throughout the policy term.

Option II: Increasing Sum Assured

The absolute amount assured to be paid on death shall remain equal to the Basic Sum Assured till the completion of the fifth policy year. Thereafter, it increases by 10% of the Basic Sum Assured each year from the sixth policy year till the fifteenth policy year till it becomes twice the Basic Sum Assured. This increase will continue under an in-force policy till the end of the policy term; or till the Date of Death; or till the fifteenth policy year, whichever is earlier. From the sixteenth policy year and onwards, the Absolute amount assured to be paid on death remains constant i.e. twice the Basic Sum Assured till the policy term ends. For example, the Absolute amount assured to be paid on death under a policy with a Basic Sum Assured of Rs. X will be Rs. X till the end of the fifth policy year, Rs. 1.1X during the sixth policy year, 1.2X during the seventh policy year, increasing so on by 10% of the Basic Sum Assured each year till it becomes 2X in the fifteenth policy year. From the sixteenth policy year and onwards, the Absolute amount assured to be paid on death will be 2X.

The Death Benefit Option once chosen cannot be changed later.

#2 Maturity Benefit: 

On survival of the life assured to the end of the policy term, no maturity benefit is payable.

 Eligibility

a) Minimum Age at entry: 18 years (Last Birthday)

b) Maximum Age at entry: 65 years (Last Birthday)

c) Maximum Age at Maturity: 80 years (Last Birthday)

d) Minimum Basic Sum Assured: Rs. 50,00,000/-

e) Maximum Basic Sum Assured: No Limit*

The Basic Sum Assured shall be in multiples of Rs. 5,00,000/-, if the Basic Sum Assured for the policy is Rs. 50,00,000/- to Rs. 75,00,000/-. Rs. 25,00,000/-, if the Basic Sum Assured for the policy is above Rs. 75,00,000/-.

f) Policy Term: 10 to 40 years

g) Premium Paying Term

Regular Premium – Same as policy term

Limited Premium –

  • [Policy Term minus 5] years for Policy Term [10 to 40] years
  • [Policy Term minus 10] years for Policy Term [15 to 40] years

Single Premium – NA

LIC New Tech Term Plan – LIC Term Plan Review 

LIC New Tech Term Plan is a pure term plan where the minimum sum assured value is 50 Lakh. It is a very good product by LIC. As it is an online term plan it can be purchased with a click of a button without intervention from LIC Agent.

This new policy is a direct copy of the LIC Tech Term Plan (Table 854). The only change is in the premium amount.

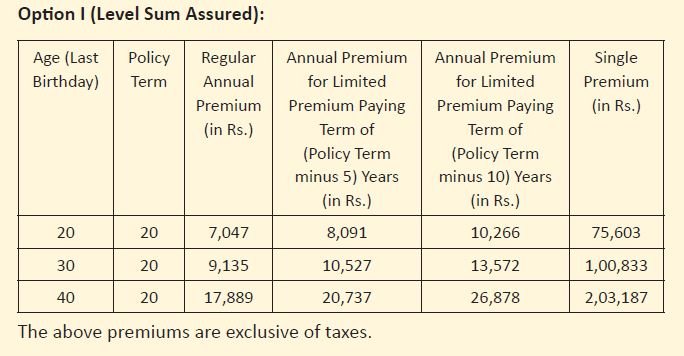
Examples of premium change in Level Sum assured for 1 Cr Plan – Nonsmoker Male are given below.

Age Policy Term Regular Annual Premium (Old Policy) Regular Annual Premium (LIC New Tech Term Plan)
20 20 INR 5368 INR 7047
30 20 INR 7216 INR 9135
40 20 INR 13770 INR 17889

This means that compared to the last plan (old tech term policy) premium of the new plan is increased. The increase is nearly 25%. This means for the new plan you need to pay a 25% extra premium amount (yearly regular plan).

LIC New Tech Term Plan Premium

LIC New Tech Term Plan Premium Detail Level Sum Assured

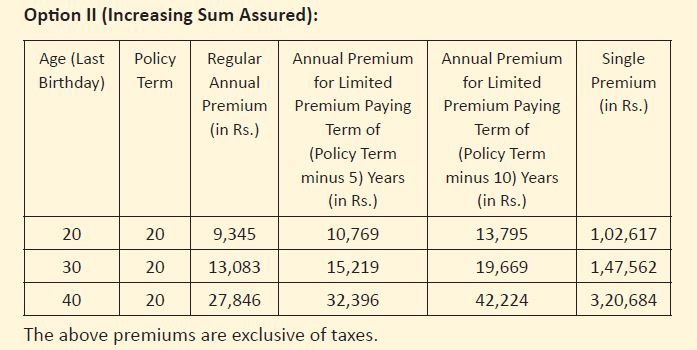
LIC New Tech Term Plan Premium Detail Increasing Sum Assured

This premium is at par with other available term plans like ICICI Pru Term Plan. This plan provides coverage for up to 80 years. The accidental rider option and discounted rate premium for non-smokers and women are additional advantages.

You have the flexibility to select the sum assured and type of plan. You can select level sum assured as well as increasing sum assured. The increasing sum assured is a unique feature of this policy. The risk level is increasing with age & one should increase the sum assured with age. This concept is perfectly covered in this plan. One can avoid purchasing multiple insurance policies if he/she opts for an increasing the sum assured.

If you have not purchased any term plan you can go for LIC New Tech Term Plan.

60 Seconds Binary Options Strategy

0

People often wonder if they can make money from short-term trading without working for a big investment house or trading firm. And the answer is yes. Even though there are a lot of risks, many people trade as a hobby or to make extra money every day. If you know what you’re doing and take steps to lower your risk, a 60 seconds binary options strategy is a great way to make money quickly.

binary options strategy

60 Seconds Binary Options Strategy

Explanation

A binary options strategy is a list of things you should think about before making a trade. Some of these things are studying the market, looking at charts, reading the news, using indicators and signals, and so on.

Risk management and emotional control are the foundations of every strategy. These are extremely important for every binary options trader because this is a very risky market and many traders let their emotions get in the way when placing trades.

Statistics

A 60-second binary trading strategy is good for both beginners and more experienced traders but it’s just one of seven basic trading strategies that could be employed on the forex market. Even if you don’t know much, you can get fast results and make money as a beginner. Professionals tend to make more money right away because they already know a lot and can use their experience to maximize their profits.

Benefits

The short trading window’s main benefit is that you can win quickly. You can make money almost any time the price goes up or down. The shorter window also has more risk, so the returns are higher compared to, say, the day window. You can also have more than one trade going on at the same time. Not to mention, 60-second binary options are pretty easy to understand as they only have two possible outcomes: win or lose.

Strategies

Trading 60-second binary options need a careful, proactive approach. Having a solid plan in place not only makes it easier to make decisions but also makes the whole thing less stressful. Importantly, there is no one-size-fits-all strategy for trading 60-second binary options, but we have put together some of our best tips below.

Risk Management

Risk management is the core of any good strategy, and 60-second binary options trading is no different. The 1% rule is a place to start for many traders. This rule says that you shouldn’t risk more than 1% of your total portfolio on a single trade. It is used to keep losses to a minimum and make sure that traders can deal with small problems and keep trading.

Charts

Setting up your chart should be pretty simple. The best place to start is with candlestick charts. Set them to a time frame of 1 minute. You can also use 1-hour charts, but we suggest working your way down to shorter charts, which will give you the most accurate information to work with. You want a price that is low over 50 candlesticks, if possible. Make sure you mark the beginning and end of the 50-candlestick period.

Support & Resistance

Since prices tend to move toward one line or the other, support and resistance levels can help you make better predictions. They can be used to figure out where the price is likely to go next. They are a good place to start for traders of all levels, but especially those who are new to trading binary options.

Technical Indicators

As you learn more, you might want to use moving averages to help you make predictions. There are a lot of technical indicators out there that can help you predict what the price will do. As a general rule, we recommend setting up moving averages and support and resistance levels. These can make it easier to tell if the price is going up or down.

Profitability

Trading binary options can make money, just like any other type of trading. But that doesn’t mean it will always make money. There is also a chance that you will lose your initial investment if things don’t go as planned. Because of this, you shouldn’t take big risks just because you think you will win a lot of money if you do. Remember that trading binary options is a lot like gambling at a casino. You should look at it as a way to make extra money, not as a way to make a living.

Conclusion

Trading in 60-second binary options is a high-stakes game with a lot of adrenaline. You’ll need to be disciplined, stick to your plan, and know your limits if you want to do well. But while the risks are big, so are the chances of success.

Top 5 Words to Avoid in Sales

Sales play an important role in any business. You can not grow your business without sales. 

However, it is often observed that when it comes to sales and closing, we end up using words that do not allow us to sell. These words generate different types of emotions in the brain of the buyers.

So, which are those words that you need to avoid while selling? 

Well, today I am going to share 5 words that I avoid in sales. Here it is.

avoid sales

Top 5 Words to Avoid in Sales

#1 To be honest with you

To be honest with you is the word you should avoid while selling products or services. Have you ever heard of that one before from a salesperson?

Just to be honest with you. Right, this is the best price that we could give you. To be honest with you or we never give this deal to anybody else.

Now, what happens is right after usually, to be honest with you, what you are telling the prospect is, well, all the conversation you’ve had up to this point, it’s a lie, right?

‘Cause to be honest with you, it means what?

You have not been honest with me this whole time, right?

You’ve been lying to me, is this what it is?

#2 Trust Me  

Have you ever heard of that one? Just trust me on this.

Yeah, this is a great deal, just trust me, man. Trust me.

Usually, when people have to say, oh, trust me, do you trust them?

No, right? 

No, because your action speaks louder than your words.

Your action would show through.

Your action would demonstrate if a prospect or someone should trust you or not.

So don’t use those words, don’t use trust me.

#3 Sorry to Bother You

Sorry to bother you. Then why the hell are you bothering me?

If you feel so sorry about it then just don’t bother me in the first place.

Sometimes I get these phone calls. Oh, you know, sir, sorry to bother you.

Then don’t call me, don’t bother me. Like, you hang up.

  • Why are you calling me in the first place?
  • Why are you bothering me in the first place?
  • Why are you wasting my time?

Before you do anything when it comes to closing in sales, usually the prospect has the power.

#4 Buy

Here’s another word, buy. Buy.

See, people love to buy, they hate to be sold. Even though they love to buy, they don’t like the idea of buying because the word buy means that oh, it’s gonna cost me money, right?

Like, I have to spend money, right? So we do love the action, the act of buying, but the word itself triggers oh when you have to buy something I’m gonna spend money on it.

So don’t use the word buy. Do you wanna buy this now? No.

So instead what should you say? Own. Or take this home with you.

So imagine if I’m selling you this, hey, do you wanna buy this?

I don’t know. Would you like to take this home with you?

Sure, right? I wanna take this home with me.

  • Would you like to own this? Oh, sure.
  • Would you like to take advantage of this? Oh, sure.
  • Would you like to move forward? Sure.

Who doesn’t like to move forward, right?

You’re moving forward in life. Oh, would you like to buy this?

I don’t know, let me think about it. It triggers a lot of resistance. It triggers fear.

#5 Individual

Another word that you wanna avoid and that is individual. Individual.

Is it individual is a very cold, institutional word. It’s very, very cold.

Oh, I know you are a busy individual.

I know you’re a very successful individual.

Do you talk to your friends that way?

Hey, do you, individual, do you wanna to watch this movie together?

Do you talk to your wife this way, individually, right?

You don’t do that. So that’s not how you talk to your friends.

That’s not how you talk to the people that you care about, right?

It’s an institutional word, it’s a very cold phrase. Don’t use it.

Use more casual, more conversational words. So eliminate an individual from your vocabulary.