Blog Page 213

Top Secret that can Make you Rich

Let’s talk about how money works. Today, I’m going to share a secret with you that guarantees you’ll be rich or you’ll be broke.

So I want you to think about how money came about.

Back then, it’s let’s say, I am a farmer and I grow vegetables in my garden, on my farm or I have some crops.

And then if I want to eat some other food and maybe you also have a farm of some sort and you have some other crop in the farm.

Back in the old days, if what we wanna do. If I wanna have some other crop, we need to trade. You’re gonna bring me the other crop and then you bring it to my farm, I’m gonna give you some vegetables in exchange.

It is a simple barter system. When you get to a point where people say, you know what? It’s kind of difficult to have everything that I want to trade with me all the time.

It’s difficult to have big items with me all the time. What can we do to just live more efficiently?

How can we make this a little bit more convenient for each other?

And people came up with the concept of money. Now back then, we’re talking about it could be like old days certain types of stones right?

And then precious metals or gold coins and things like that and now today
we’re talking about, of course, paper.

Rupees, bills, dollars, or even our digital currency. But that’s how money works.

Now, let’s talk about Top Secret that can Make you Rich.

Rich

Top Secret that can Make you Rich

You have to understand the world revolves around value. So if you understand the world revolves around value.

The business of making money is nothing more than a value and value exchange.

Once you realize that, that is how money works and that’s how the game works.

So what we do is we trade our time, if you’re an employee.

Our products or services, our expertise as an entrepreneur.

Our skills. We trade that and exchange that with other people for money.

What it means is, the more value that you could provide, the more money people are willing to trade you with it.

It’s that simple. So instead of just focusing on, I wanna make more money being all desperate and panicking, what you focus on is instead of becoming a person of success, become a person of value.

If you wanna make more money, the question you have to constantly ask yourself is how could I be a person of value?

How could I become more valuable?

How do you become more valuable to the marketplace?

Once you understand this, money is not an issue. Because the marketplace is always willing to pay good money for good value.

What’s the difference between someone making an INR 200 hour instead of someone making let’s say INR 2000 an hour as a doctor?

Someone making an hour, the marketplace is saying, hey you know what, you’re only worth INR 200 or INR 300 or INR 500 an hour, versus I’m willing to pay INR 2000 to spend an hour with a doctor.

The difference in value, not your person. Not a person, not valued as a person.

Value, the marketplace is willing to pay. And you notice, people who don’t make a lot of money, people who are struggling, or people making minimum wage, are easily replaceable.

They see someone working at a restaurant.

A waiter, waitress. Maybe they do a very good job, and they work very hard but if they leave or the boss or the manager fires them, they could be easily replaced.

When you could be easily replaced, you are not very valuable.

The more difficult you are to replace, the more valuable you are.

That’s the secret that will guarantee if you’ll be broke or you’ll be rich.

Now the next step, assuming you’re working hard, you are developing your skills, and you’re becoming more valuable in the marketplace.

What you really wanna get to is to become invaluable. Now, what do I mean by that?

Invaluable meaning, irreplaceable.

When you are invaluable in the marketplace, the marketplace will reward you handsomely because you are irreplaceable.

Let me give you some examples.

Michael Jackson. That’s invaluable because there’s only one Michael Jackson in the world.

Michael Jordan. He is invaluable because there’s only one Michael Jordan in the world and that’s why fans, of Nike are willing to spend millions and millions of dollars with one person because he’s invaluable.

Oprah.

Beyonce.

All the celebrities. There’s only one of them. There are many other singers and dancers but there’s only one Beyonce.

Being invaluable also means you are wanted, you are needed, and you’re being desired by a large group of people.

The more people who desire you, who want you, who need you, the more invaluable you are.

The more difficult it is to replace you, the more invaluable you are, and the more invaluable you are, the more money you’re gonna make, and the more wealth you can create.

So become a person of value.

That’s how money works. It is a value and value exchange.

So ask yourself, what are you willing to do to be a person of value?

To become that valuable person in the marketplace.

And then maybe, eventually become invaluable.

That is the Top secrete that can make you rich.

Investing in Savings Schemes Online: What Are Your Options?

0

Savings schemes allow investors to save and grow their money. There are a number of different savings schemes available, each with their own features and benefits.

The main purpose of any savings scheme is to help you save money, increase your savings, and build a financial buffer so that you can deal with unexpected expenses when they arise.

Here are the benefits of investing in savings schemes

Investing saving online

#1 Help in Long-Term Financial Planning

As an investor, the biggest advantage of investing in a savings scheme is that it will help you to save for your future. By putting aside money for retirement, you can ensure that you have a steady income in old age.

Furthermore, if you’re not comfortable with high investment risks, then you can choose a lower-risk option like savings schemes, as they provide stable returns. This way, you won’t need to worry about running out of money in retirement.

#2 Help You Meet Financial Goals

It is important to have savings to meet financial goals. Having a savings plan can help you set and meet financial goals and achieve them faster. By saving regularly, you can build wealth over time.

Furthermore, there are savings schemes that are created to meet specific goals. For instance, a few savings schemes allow you to pay for your child’s future expenses.

#3 Help in Getting Tax Benefits

Most savings schemes allow you to avail a tax deduction of up to Rs. 1.5 Lakh under Section 80C.

The Importance of Savings

The importance of savings cannot be overstated. If you don’t have sufficient money saved up, then it can become difficult to get the things you need or achieve your financial objectives, like buying a home. However, if you do have a lot saved up, then it can help you feel less stressed about the future and give you the confidence to take on bigger projects.

There are several ways to save money. You can set aside money every month in a savings account or invest in savings schemes online. This will give you the incentive to save and may also help you budget better. Whatever way you choose, make sure that you are saving enough money each month so that you can cover expenses that may come up.

Here are some options that you should consider to achieve your savings goals-

#1 Public Provident Fund (PPF)

One of the most popular savings options is PPF. You can apply for it at banks or post offices. You’ll get returns based on the interest rate. Furthermore, by investing in PPF, you can get a tax deduction of up to Rs. 1.5 Lakh under Section 80C.

#2 National Pension Scheme (NPS)

NPS is a scheme launched by the government. The main objective of this scheme is to provide subscribers with a regular income for life after retirement. At retirement, subscribers can receive a specific percentage as a lump sum amount. The remaining amount is used to purchase an annuity, and it will be provided as a pension on a regular basis.

#3 Senior Citizen Savings Scheme (SCSS)

The SCSS was launched to help individuals who are 60 years and above. It is a great option for people who want to secure their future financially. You can also get a tax deduction under Section 80C by investing in this scheme.

#4 Mutual Funds

One of the best investment options that can provide exponential returns are mutual funds. Mutual funds are investment vehicles that pool money from many investors and invest it in a range of different assets.

They also provide the benefit of diversification. They spread your money across a wider range of investments and help reduce the risk of losing all of your money if one particular investment underperforms.

#5 National Savings Certificate (NSC)

National Savings Certificate is a scheme supported by the government. It provides guaranteed returns to investors. The interest rates on NSC are decided by the government.

Invest in Savings Schemes to Ensure Financial Safety

If you haven’t started saving money, then now is the right time to start. Whether you’re a student or a professional, you need to start building your savings as soon as possible. The sooner you start, the better.

So don’t wait any longer. Prioritise saving in your life today. Don’t forget to put some money aside every month – it’s the only way you’ll be able to make significant progress.

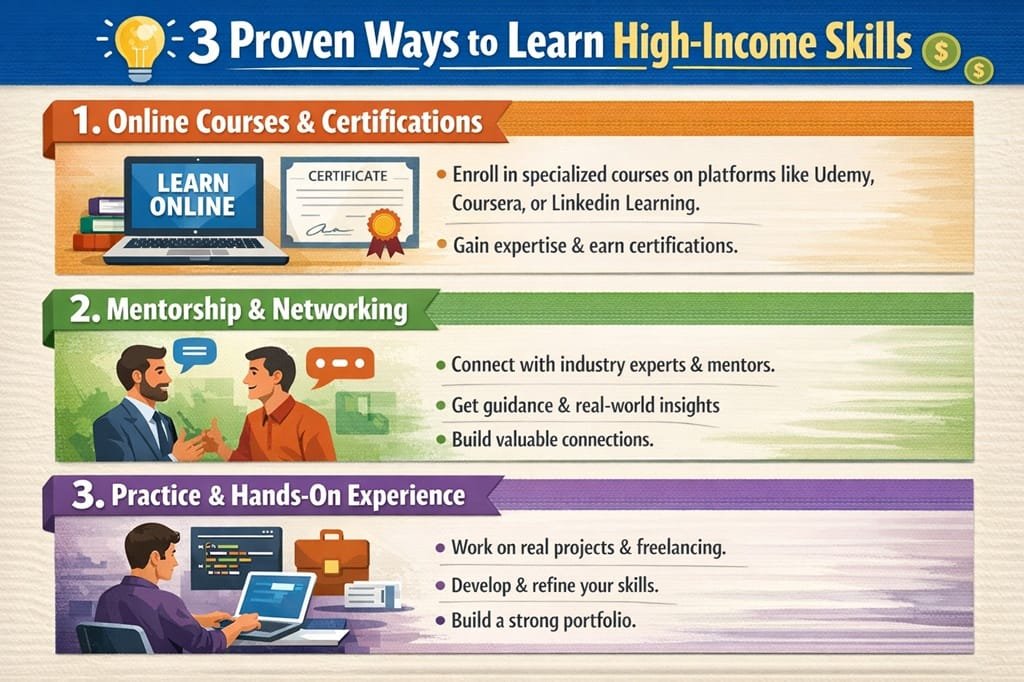
3 Proven Ways to Learn High-Income Skills

Do you want to learn a high-income skill?

Do you want to learn a new language? Or maybe you want to learn how to start your online business, or you want to learn sales and marketing and many different topics in business.

Now, today I’m gonna share something with you that has profoundly changed my life, and that is how you learn properly.

learn high income skills

I believe there are only three proven ways that you can learn. Here it is.

3 Proven Ways to Learn High-Income Skills

#1 Self Learning  

The first way is learning from yourself. People call that the school of hard knocks.

Learning from your own mistakes by trial and error. Where you make enough mistakes that you will learn from it, and that’s perfectly fine.

Now, a lot of people learn this way, and the problem is it is very, very costly and it takes a long time for you to learn anything, but if you are persistent enough, if you’re determined enough, and if you are resourceful enough, you could figure things out on your own.

But you can end up working on the wrong information. You can end up making some mistakes and that may be costly.   

Now, that’s learning from yourself, which is fine. There are some pros and cons.

The pros is, you can learn from yourself, there’s no barrier to entry, you can learn it any time you want and it is free, right?

Learning from yourself.

The downside is, it costs a lot of money, sometimes it costs a lot of time, and it’s like the saying if you think education is expensive, try ignorance.

Right, it’s very, very true. So, learn from yourself.

#2 Learning from Your Peers 

The second way that you can learn is by learning from your peers.

Learning from your peers. 

So, learning from the people, kind of, around you, maybe the same level.

Now, the problem is, learning from your peers is sometimes you learn the wrong thing.

They kind of, they tell you about this, tell you about that, they have an opinion about everything, and because they’re your peers and you like them they like you and you listen to them, then you thought, you know what?

Now, the biggest problem with learning from your peers is this, I want you to imagine this, okay?

Let’s say you want to learn how to speak English as it is a widely accepted language.

And you and your friends get together. And you don’t know how to speak English, and he doesn’t know how to speak English either.

So, imagine this. You’re both locked in the room. And you’re locked in a room for 2 days.

And I say, okay, I’m gonna come back in days. Now, chances are when I come back, what is the chance that you know how to speak English after 2 days?

Zero.

Why?

Because you don’t know, and he doesn’t know. How could you have two people who don’t know something and suddenly, when you put them together, suddenly, magically, they will know it?

No, that’s not how life works. Now, that is a little bit of an extreme example, but it’s not so extreme.

Think about this.

In terms of success, in terms of creating wealth, in terms of creating, like financial business success. 

A lot of people, a lot of you, take advice from your peers.

And they tell you, hey –

  • You shouldn’t do sales this way.
  • You shouldn’t get your customers this way.
  • You shouldn’t grow your business this way.
  • You shouldn’t invest your money this way.
  • You should invest in this way and that way.

The problem is, you and them, are on the same level. You don’t know what you don’t know.

How could they possibly teach you? And why do you want to listen to them? When you’re at the same level.

Two people who don’t know something getting together and now they learn from each other? It is a mess. It is a disaster, right?

It’s just back and forth, back and forth, lip service. 

The third way that you can learn, which I believe is the most powerful way to learn, which is also the way that I have learned over the years, why I’m able to accomplish what I’ve accomplished at a young age instead of the age of 42 and not at 50,60.

And that is learning from a mentor.

#3 Learning From a Mentor

Learning from someone who’s been there and done that and continues to do it.

Imagine if you are an athlete.

You want to learn how to play cricket.

Yes, you can learn from yourself, and yes, you can kind of play basketball with your friends.

But if you want to be a professional, guess what? You need to get a mentor, need to get a coach to show you exactly what drills you need to practice on a daily basis to get better.

What are some of the exercises that you have to do?

The coach, he’s watching you, he’s correcting you, right?

He’s shaping you, he is molding you. He’s helping you to get to that next level. That’s the power of a mentor.

I am where I am today, yes, I have made a lot of mistakes, absolutely.

I have learned from other people. My peers, yes.

But, I am where I am today because of my mentors & Teachers. I learn from my mentors.

I eat, sleep and drink – Money, Digital Marketing, and Content Creation. 

I learned many things from my mentor and I am implementing them. I also become Multi Income Coach and Infopreneur mentor. I teach people High-Income skills and How to make money online part-time along with a job. I am proud to say that I am spreading knowledge and Many people have learned from me.

  • I’m a great teacher because
  • I’m a very, very dedicated student.
  • I’m always coachable.
  • I’m always, always hungry for knowledge and for more.

More insights, more distinctions, just more perspectives.

I’m hungry for that.

So if you’ve been following me for some time now, I can see your comment on social media, and on YouTube.

And you ask me, Shitanshu, can you be my mentor?

Shitanshu, can I attend your Webinar? Or can I learn from you, can you help me?

I have created multiple programs that could help you.

I’ve got many, many ways that I could help.

But you see, reading a blog like this, that’s not mentorship.

Because to me, a mentorship there has to be an interactive component into it.

So you think you’re learning a lot, just by reading blog content and watching my video, then you are wrong. I call it an outsider.

My insider, more inner circle students, the ones that are my private students, are learning from me.

I’m a mentor, I’m a see-through to them.

So if you’re serious, very serious, and committed to learning and you really want me to be your mentor, not thinking about it, not someday, but today.

5 Factors to Consider Before Financing Your New Car

0

Buying a car is a big decision, and it can be one of the most expensive purchases ever. Usually, car deals are made by financing it by taking a car loan. Getting a loan for your car will be the best thing for you as these loans are often easily availed at lower interest rates.

However, there are a few things that you need to consider to make your car financing a successful venture for you. From calculating your credit score to determining an affordable EMI, you must go through a few things before applying for a car loan.

Before diving into financing your new car, it’s essential to carefully assess the five factors highlighted here. Among these considerations, one pivotal aspect is understanding the multiple finance options available. Navigating through these diverse financial avenues will enable you to make a more informed decision tailored to your specific needs and financial goals when purchasing your new vehicle.

Here’s a rundown of a few such points of consideration:

Car Financing

5 Factors to Consider Before Financing Your New Car

#1 Evaluate Your Credit Score First

Your credit score is one of the most influential factors in getting a car loan. But, surprisingly, it isn’t as easy to compute your credit score as it may seem to be. First, you must ensure that the credit report you’re referring to has been updated in the last 30 days.

You can use a car finance calculator available online to calculate your loan figures. It will give you an accurate calculation about everything including the loan amount, tenure and monthly EMI.

What you should do:

  • Check your credit report before visiting the dealership.

  • Use free tools like Credit Karma or CIBIL (in India) to get a snapshot.

  • Fix errors if you find any. You’d be surprised how often they pop up!

  • If your score is low, consider delaying your purchase and improving your score. A few months can make a big difference.

#2 Determine an Interest Rate

You must not just settle for a car loan with an interest rate of 15% because this may push you into tens of thousands of dollars in debt due to interest payments over the next decade. Instead, you must always look for a car loan with the lowest interest rate you qualify for and can pay back.

Besides, it’s also a good idea to compare interest rates and choose the best option that suits you best. Then, with a little research, you can get a car loan that will match your requirements with an affordable interest rate.

Watch out for:

  • Processing fees

  • Documentation charges

  • Prepayment penalties

  • Insurance premiums bundled into the loan

  • Extended warranties and add-ons you didn’t ask for

What you should do:

  • Request a loan cost breakdown before signing.

  • Ask, “Are there any pre-closure charges?”

  • Get clarity on interest calculation method—flat rate or reducing balance?

  • Double-check if the insurance and accessories are optional or mandatory.

#3 Find an Accountable Car Dealer

You must find a car dealer who will be able to answer all your questions and provide you with a good deal. If you have found a good car dealer, then it is likely that you are on the right track to successfully finance your car.

A reputable car dealer tends to offer comprehensive services, from buying and selling to financing and servicing, significantly streamlining your entire vehicle acquisition journey.

#4 Calculate Your Down Payment

The amount of your down payment should ideally be at least 10% of the car’s total value. Aside from this, it is very important to ensure that your down payment will ensure that you have enough cash to repay your loan in full when it comes down to it.

Are you looking for an SUV, a commuter vehicle, or something else? This will likely impact how much money you will pay upfront and what interest rate you will get after going through car financing.

The catch with zero down:

  • You borrow more money, which means more interest.

  • You’ll have higher EMIs.

  • You may end up upside-down—owing more than the car’s value.

Why a bigger down payment rocks:

  • Less money borrowed = less interest paid.

  • Lower monthly payments.

  • Better chance of loan approval with favorable terms.

#5 Make Sure You Can Handle the Monthly EMI

As a rule of thumb, you should never commit to a car payment higher than 15% of your net income or 10% of your gross monthly income. To calculate the EMI, divide the cost of the new car by its interest rate. The lower the figures, the more manageable the repayment will be.

Longer loan = smaller EMI, but…

  • You pay more in interest over time.

  • You might owe more than the car’s worth at some point due to depreciation.

  • Longer terms can tempt you to buy more car than you can afford. Ouch.

What you should do:

  • Aim for the shortest term you can comfortably afford.

  • Ask the lender to show you the total repayment amount, not just the monthly EMI.

  • Don’t be afraid to negotiate or walk away if it feels off.

FAQs

Q1: Can I finance a car with bad credit?

Yes, but expect higher interest rates. Consider improving your credit score first or getting a co-signer with better credit.

Q2: Is it better to get a car loan from a bank or a dealership?

Banks generally offer lower interest rates, while dealerships may offer convenience but at a cost. Always compare both.

Q3: What’s the ideal loan tenure for a car?

Ideally, 3 to 5 years. Anything longer increases your total interest cost.

Q4: Can I pay off my car loan early?

Absolutely, but check for prepayment penalties or fees before doing so.

Q5: What if I miss an EMI payment?

You could face late payment charges, a hit to your credit score, and even repossession if it continues.

Conclusion

There’s no denying it—financing your new car can open doors (or rather, car doors!) to ownership that fits your lifestyle and budget. But without the right planning, it can also steer you straight into a financial pothole.

By taking time to understand your credit, exploring all your options, avoiding sneaky charges, and making thoughtful decisions, you set yourself up for smooth cruising—not just on the road, but in your financial life too.

So the next time you spot your dream car, don’t just ask, “Can I afford the EMI?”
Ask, “Is this the smartest way to finance my new car?”