Blog Page 18

How to Withdraw Your EPF Online

If you are a salaried employee in India, there is a good chance that a portion of your salary gets deducted every month and goes into your Employees’ Provident Fund (EPF) account. Your employer adds a matching contribution as well. Over the years, this money accumulates — often becoming a substantial sum — and earns interest declared by the EPFO (Employees’ Provident Fund Organisation) every year.

This fund acts like a safety net for your retirement. However, life does not always go in a straight line. You might lose a job, face a medical emergency, plan to buy a house, or need to fund your child’s education. The good news is that EPFO allows you to withdraw this money — either fully or partially — depending on your situation.

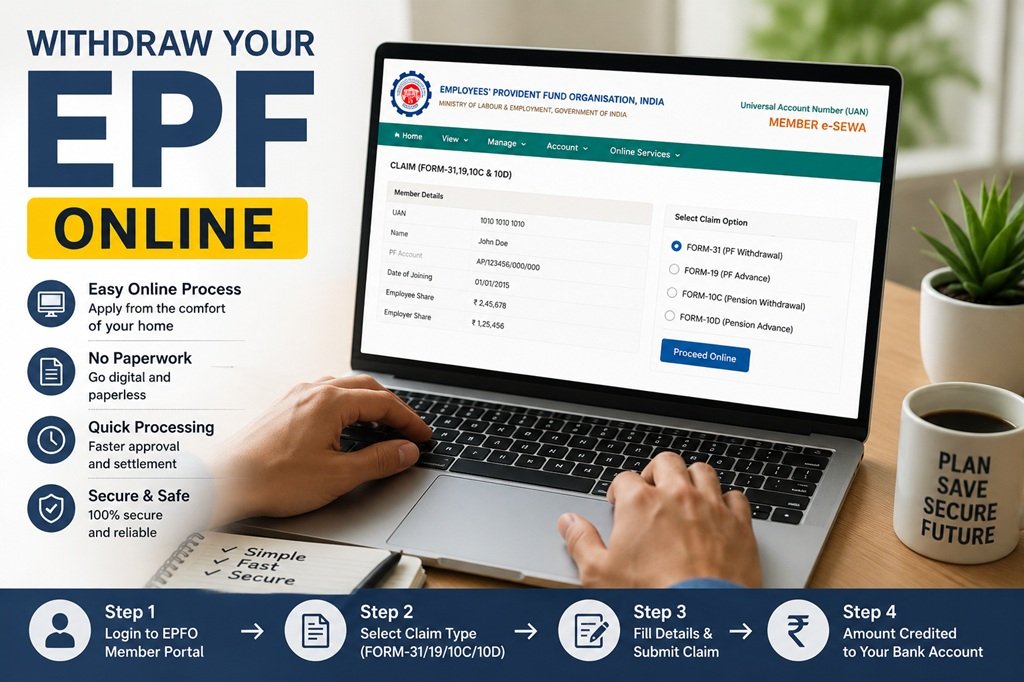
The even better news: you can now do most of this online, from the comfort of your home, without needing your employer’s signature for most claims.
withdraw epf online

Types of PF Withdrawal

Withdrawal Type Form Required Processing Time Employer Approval?
Full PF Settlement Form 19 3 to 5 working days Not Required
Partial Advance (PF) Form 31 7 to 10 working days Not Required
Pension Withdrawal Form 10C 7 to 20 working days Not Required

Who Can Withdraw PF Online?

Before you begin, make sure you meet all of the following conditions. If even one is missing, your claim may get rejected.

  • Your UAN (Universal Account Number) must be activated.
  • Your Aadhaar and PAN must be linked and verified on the UAN portal.
  • Your bank account must be seeded (linked) with your UAN.
  • Your mobile number must be the same one linked to your Aadhaar — you will receive an OTP on it.
  • You must have updated your Date of Exit in the EPFO portal (not required for partial advance while employed).
  • You meet the eligibility condition: retired, unemployed for 2+ months, or eligible for a specific partial withdrawal.

Important: If your name in EPFO records does not exactly match your Aadhaar name, your claim will be rejected. Make sure to fix this before applying.

Documents and Things to Check Before You Apply

There is no physical document upload required for most online claims. However, you must make sure the following are in order — think of it as a checklist before you press ‘Submit’.

  1. UAN Activation and KYC

Your UAN must be active and your KYC (Aadhaar + PAN) must be verified. Log in to the UAN portal and check under Manage > KYC to see if your Aadhaar and PAN show a green ‘Verified’ status.

  1. Bank Account Details

Your bank account IFSC code and account number must be correctly linked. Even a single digit error can cause the money to bounce back. Double-check this before applying.

  1. Date of Exit

If you are applying for a full settlement (Form 19) or pension withdrawal (Form 10C), your Date of Exit must be updated. This is the date you officially left your last employer. If it is not updated, you cannot proceed. You may need to ask your previous employer to update it, or raise a grievance with EPFO.

  1. No Overlapping Service Dates

Check your Service History in the portal. If two jobs show overlapping dates — even by one day — your claim may get stuck. Contact your former employers to fix any such discrepancy.

How to Withdraw PF Online: 8 Simple Steps

Follow these steps carefully. The entire process takes about 10 to 15 minutes if everything is in order.

  1. Go to the UAN Member Portal at unifiedportal-mem.epfindia.gov.in. Log in using your 12-digit UAN and password.
  2. Once logged in, click on ‘Manage’ in the top menu and then click ‘KYC’. Verify that your Aadhaar, PAN, and bank account are showing as ‘Verified’ (green tick). If anything is unverified, fix it first.
  3. Go to ‘Online Services’ in the top menu and select ‘Claim (Form-31, 19, 10C & 10D)’.
  4. A page will appear showing your basic member details. At the bottom, enter the last 4 digits of your bank account number and click ‘Verify’.
  5. A certificate of undertaking will appear on screen. Read it and click ‘Yes’ to proceed.
  6. Click the button that says ‘Proceed for Online Claim’.
  7. You will now see a dropdown menu asking you to select the type of claim. Choose the one that applies to your situation: Form 31 if you are still employed and need a partial advance, Form 19 if you have left your job and want to settle your full PF balance, or Form 10C if you have left your job and want to withdraw your pension (EPS) amount.
  8. Tick the declaration checkbox at the bottom of the page. An OTP will be sent to the mobile number linked to your Aadhaar. Enter that OTP and click ‘Submit’.

That is it! Your claim is submitted. You can track its status on the same portal under ‘Online Services > Track Claim Status’.

How to Withdraw PF Using the UMANG App

If you prefer using your phone instead of a computer, you can do the entire process through the UMANG app. UMANG (Unified Mobile Application for New-age Governance) is a government app available on both Android and iOS.

  1. Open the UMANG app and log in with your registered mobile number.
  2. In the search bar, type ‘EPFO’ and open the EPFO services section.
  3. Tap on ‘Raise Claim’ under the employee services.
  4. Enter your UAN and verify your identity using the OTP sent to your Aadhaar-linked mobile number.
  5. Choose the type of claim — Full Settlement, Partial Advance, or Pension Withdrawal.
  6. Verify your bank account details shown on screen.
  7. Upload any supporting documents if prompted (for some advance types, you may need a scanned copy of a relevant certificate).
  8. Submit the claim and note down the reference number for tracking.

How to Withdraw PF Offline

If you are unable to complete the process online — perhaps your Aadhaar is not linked yet, or your mobile number is different — you can still withdraw PF by visiting your regional EPFO office.

Option 1: Composite Claim Form (Aadhaar)

Use this form if your Aadhaar and bank account are linked on the UAN portal. Download it from the EPFO website, fill it in, and submit it to the EPFO office that handles your region. You do not need your employer’s signature in this case.

Option 2: Composite Claim Form (Non-Aadhaar)

If your Aadhaar is not linked, download this version of the form instead. In this case, you will need your employer’s attestation (signature and stamp) before submitting it to the EPFO office.

Tip: Since 2017, EPFO allows self-certification for partial withdrawals. You no longer need multiple certificates or letters from your employer to explain your reason for withdrawal. A simple declaration is enough.

Types of PF Withdrawal

  1. Full Withdrawal (Complete Settlement)

You can withdraw 100% of your EPF balance only under two conditions: retirement (at age 58 or above) or unemployment. If you have been unemployed for at least 2 months, you can withdraw your entire PF amount. During the waiting period, you can still withdraw 75% immediately after losing your job.

Situation How Much Can You Withdraw?
Unemployed for less than 2 months 75% of your PF balance
Unemployed for 2 or more months 100% of your PF balance
Retired (age 58+) 100% of your PF balance
  1. Partial Withdrawal (Advance)

You do not need to resign or retire to access your PF. EPFO allows partial withdrawals for specific life needs. Here is what you need to know:

Purpose Maximum Amount Service Required Key Condition
Medical Emergency Employee’s share + interest or 6 months’ wages (whichever is less) No minimum For self or family member
Child’s Education Up to 50% of employee’s share (max 3 times) 7 years Children’s education after Class 10
Wedding Up to 50% of employee’s share (max 3 times) 7 years For self, sibling, or child’s marriage
House Purchase Up to 90% of total balance 5 years Property in your or spouse’s name
Home Renovation 12 times monthly wages 5 years Can only be claimed once
Pre-retirement 90% of total balance Not applicable Must be 54+ years old or within 1 year of retirement
  1. Pension (EPS) Withdrawal Rules

Your EPF contributions are split into two parts: the actual Provident Fund (EPF) and the Employees’ Pension Scheme (EPS). The pension part follows different rules:

  • Less than 6 months of service: You cannot withdraw pension money at all.
  • 6 months to 9.5 years of service: You can withdraw the full pension amount using Form 10C.
  • More than 9.5 years of service: You are not allowed to withdraw pension money. Instead, you become eligible for a monthly pension when you reach the age of 58.

Will Your EPF Withdrawal Be Taxed?

This is where many people get confused. The tax treatment of your EPF withdrawal depends mainly on how long you have worked in total (across all employers where EPF contributions were made).

Your Total Service Period Withdrawal Amount Tax Treatment
5 years or more Any amount 100% Tax-Free
Less than 5 years Below Rs. 50,000 No TDS deducted
Less than 5 years Rs. 50,000 or more (with PAN linked) 10% TDS deducted
Less than 5 years Rs. 50,000 or more (without PAN) 30% TDS deducted

Pro Tip: If you have worked for less than 5 years and your total income for the year is below the taxable limit (currently Rs. 2.5 lakh under the old regime or Rs. 3 lakh under the new regime), you can submit Form 15G (for people below 60) or Form 15H (for senior citizens) to avoid TDS deduction altogether.

Also remember: if you change jobs and transfer your PF instead of withdrawing it, your service period is counted continuously. So if you worked 3 years at Company A and transferred your PF to Company B where you work for another 3 years, your total service is 6 years — making your withdrawal tax-free.

Why Do PF Claims Get Rejected?

A rejected claim is frustrating. Here are the most common reasons — and what you can do about each.

  • Your name in EPFO records is different from your Aadhaar. Even a small difference like ‘Raj Kumar’ vs ‘Rajkumar’ can cause rejection. Fix it by submitting a Joint Declaration Form signed by you and your employer. Name Mismatch:
  • The cancelled cheque you uploaded was blurry or the bank name, account number, or IFSC code was not readable. Upload a clear, flat scan or photo. Unclear Cheque Image:
  • You selected Form 31 (advance while employed) but mentioned that you are ‘out of service’. Or you selected the wrong reason in the dropdown. Re-read the form options carefully. Wrong Form Selected:
  • The money was processed by EPFO but bounced back because your bank account was inactive, frozen, or closed. Activate your account or update your bank details. Dormant or Frozen Bank Account:
  • For full settlement claims, EPFO will reject the claim if your Date of Exit is blank. Ask your previous employer to update it — or contact EPFO if your employer is unresponsive. Date of Exit Not Updated:

EPFO 3.0: What’s New in 2026?

EPFO has launched a major upgrade to how members can access their money. Under the EPFO 3.0 framework, several new features have been introduced:

  • ATM-based PF Withdrawal: In the coming months, you will be able to withdraw PF money directly from an ATM, similar to how you use a debit card. A special ATM card linked to your PF account will be issued.
  • UPI-based Withdrawal: You can transfer your PF advances directly to your UPI ID, making the process even faster.
  • Higher Auto-Settlement Limit: The limit for automatic settlement has been raised to Rs. 5 lakh. This means claims below this amount are processed automatically without manual intervention.
  • No Employer Approval: For most claims, you no longer need your employer to approve or sign off. The system works entirely through Aadhaar-based OTP verification.
  • Minimum Balance Rule: You must always maintain at least 25% of your PF balance in the account, even after withdrawals.

How to Track Your PF Claim Status

Once your claim is submitted, here is how you can check where it stands:

  1. Log in to the UAN Member Portal.
  2. Click on ‘Online Services’ in the top menu.
  3. Select ‘Track Claim Status’.
  4. Your claim will show one of these statuses: Under Process (EPFO is reviewing it), Settled (money has been transferred to your bank), Rejected (your claim was denied — check the reason), or Returned (money was sent but bounced back).

Typically, online claims are processed within 3 to 20 working days depending on the type of claim. If your claim is stuck for more than 20 days, you can raise a grievance on the EPFiGMS portal (epfigms.gov.in).

EPFO Contact Details

Need help? Here is how to reach EPFO:

  • Toll-Free Helpline: Call 14470 (available on working days during office hours)
  • Missed Call Service: Give a missed call to 9966044425 from your registered mobile number to get your EPF balance details.
  • SMS Balance Check: Send the message EPFOHO UAN to 7738299899 from your registered mobile number.
  • Email Support: Write to employeefeedback@epfindia.gov.in for queries or complaints.
  • Grievance Portal: Visit epfigms.gov.in to register a formal complaint if your issue is not resolved.

Final Thoughts

Withdrawing your EPF is much simpler than it used to be. A few years ago, you needed physical forms, employer signatures, and multiple visits to the EPFO office. Today, if your UAN is activated and your KYC is in order, you can complete the entire process in under 15 minutes — right from your phone or laptop.

The most important thing to do right now, even if you are not planning to withdraw, is to make sure your UAN is active, your Aadhaar and PAN are linked, and your bank account is correctly updated. That way, whenever you need the money, you are ready.
NPS Swasthya Pension Scheme for Secure Retirement

NPS – The Pension Fund Regulatory and Development Authority (PFRDA) has officially launched the NPS Swasthya Pension Scheme. It is health care scheme for retirement where NPS subscribers can have a dedicated health-linked pension account to pay for out-patient visits, hospital stays, and other qualifying medical expenses.

Remember it is not health insurance. It is your own saving for your own health in the separate account. You can save money via NPS Swasthya and use it in the future when you actually needs it. Think of it as the pension world finally growing up and acknowledging that healthcare costs are just as real as retirement costs.

In this article, we will look at everything about NPS Swasthya Pension Scheme Eligibility, contributions, withdrawals, and exit criteria.

NPS Swasthya

What Exactly Is the NPS Swasthya Pension Scheme?

At its core, the NPS Swasthya Pension Scheme (also called NSPS) is a health-linked, contributory pension product introduced under the National Pension System’s Multiple Scheme Framework (MSF). It operates as a sector-specific scheme — meaning it’s separate from your regular NPS account but tied to the same overall NPS architecture.

PFRDA launched it as a Proof of Concept (PoC), which basically means it’s running as a pilot for now, in a controlled environment under the Regulatory Sandbox Framework. The idea is to test whether mixing pension savings with healthcare benefits actually works on the ground before rolling it out to the entire country. Smart move, honestly.

The scheme came about after PFRDA examined the feasibility of integrating health-related benefit mechanisms with the existing NPS architecture. And what they found was encouraging enough to move forward with a limited launch.

Here’s the big picture in simple terms:

  • You open a dedicated NPS Swasthya account alongside your regular NPS account.
  • You contribute money into it voluntarily.
  • When you face medical expenses — whether it’s a doctor visit or a major surgery — you can withdraw from this dedicated account.
  • Payments go directly to hospitals or health administrators, not into your pocket.
  • Any leftover money after your medical bill is settled goes back to your regular NPS account.

It’s clean, it’s structured, and it fills a gap that has been gaping for far too long.

Eligibility Criteria for NPS Swasthya

One of the most refreshing things about the NPS Swasthya Pension Scheme is that it isn’t buried under layers of complicated eligibility rules. Here’s the straightforward breakdown:

Basic Eligibility

  • Any Indian citizen — resident or non-resident — is eligible to join.
  • You must already have a Common Scheme Account under the regular NPS. If you don’t have one, you’ll need to open one first.
  • Participation is completely voluntary. Nobody’s forcing your hand here.
  • Standard KYC (Know Your Customer) documentation is required, but the process is streamlined.

The Age-Based Transfer Rule

Here’s where it gets a little more specific — and a bit more interesting:

  • If you’re above 40 years of age and you’re a non-government sector subscriber, you’re allowed to transfer up to 30% of your own contributions from your existing Common NPS Account into the NPS Swasthya account.
  • This is a one-time flexibility option designed especially for those who already have a decent corpus built up and want to earmark a chunk of it for health needs.

Who’s Left Out of the Transfer Option?

This is important: government sector employees and those in government-owned corporates are currently excluded from the 30% corpus transfer option. They can still open an NPS Swasthya account and contribute fresh money into it, but they can’t move existing NPS funds into the Swasthya account under the current pilot rules.

It’s a limitation worth knowing upfront, especially if you’re a central or state government employee who was hoping to redirect an existing corpus.

How Contributions Work Under NPS Swasthya

The contribution structure under the NPS Swasthya Pension Scheme is refreshingly flexible — there’s no rigid monthly amount you’re forced to commit to.

Key Contribution Facts

  • Minimum initial contribution: ₹25,000 to open the account and become eligible for scheme benefits. The moment you make this contribution, you’re in.
  • Subsequent contributions: You can contribute any amount of your choice, as and when you like, in line with existing NPS guidelines for the non-government sector.
  • Investment of funds: Whatever you contribute is invested by empanelled Pension Funds under the Multiple Scheme Framework (MSF) guidelines — so your money isn’t just sitting idle. It’s working for you.
  • No mandatory monthly commitment: Unlike some insurance products that demand a fixed premium, NPS Swasthya gives you the freedom to contribute on your own terms.

One thing to keep in mind: the scheme is contributory, meaning you’re building your own health fund. The government isn’t topping it up. This is your money being managed wisely for your future medical needs.

How Withdrawals Work 

Alright, this is the part most people are curious about — what happens when you actually need to use the money? The NPS Swasthya Pension Scheme has clear, well-defined rules for withdrawals, and they’re designed to be genuinely useful rather than bureaucratically frustrating.

Partial Withdrawals for Medical Expenses

  • Subscribers are allowed to make partial withdrawals from their NPS Swasthya account to cover both outpatient (OPD) and inpatient (hospitalisation) medical expenses.
  • At any given time, you can withdraw up to 25% of your own contributions made to the scheme. Note that this is your contributions, not the total corpus (which might include investment gains).
  • No limit on the number of withdrawals — you can make multiple withdrawals as medical needs arise. No waiting periods between withdrawals either, which is a huge relief compared to the rigid rules of standard NPS.
  • One condition for the very first withdrawal: You need to have accumulated at least ₹50,000 in your NPS Swasthya account before you can make your first withdrawal. Think of it as the scheme ensuring there’s a meaningful corpus before any outflow begins.

Where Does the Money Actually Go?

Here’s the safeguard that keeps the system honest: withdrawn funds are paid directly to hospitals, Health Benefit Administrators (HBAs), or Third Party Administrators (TPAs). The money doesn’t pass through your personal bank account — it goes straight to the medical service provider based on valid claims and supporting invoices.

Any amount left over after the medical bill is settled? It’s automatically transferred back to your regular NPS Common Scheme Account. Nothing is wasted.

Exit Rules and Premature Withdrawal: What Happens in Extreme Situations?

Medical emergencies don’t always play by the rules of a standard 25% withdrawal cap. What if your hospital bill is enormous — far more than what a partial withdrawal can cover?

The NPS Swasthya Pension Scheme has thought about this too.

Premature Exit for Serious Inpatient Treatment

If you’re facing an inpatient hospitalisation where the medical expenses in a single instance exceed 70% of the total corpus in your NPS Swasthya account, you’re permitted to take a premature exit with 100% lump sum withdrawal — regardless of how large or small your corpus is.

Let that sink in. If your medical bill is big enough relative to what’s in your Swasthya account, you can pull everything out at once. No arguments, no lengthy approvals — the scheme understands that a health crisis isn’t the time for bureaucratic red tape.

This exit, like regular withdrawals, is still paid directly to the HBA or TPA. And again, any surplus after settling the medical bill goes back to your regular NPS account.

Regular Exit Provisions

For exits that don’t fall into the emergency medical category, the standard NPS exit rules apply:

  • The accumulated amount in the NPS Swasthya account is first transferred to your Common Scheme Account.
  • From there, normal and premature exit rules applicable to the All Citizens Model under NPS kick in.
  • This ensures your retirement savings are still protected even if you stop contributing to the Swasthya account.

What If the Pilot Scheme Is Discontinued?

Since this is running as a Proof of Concept with a limited duration, there’s always the possibility it doesn’t get a permanent rollout. In that case, PFRDA has already clarified: subscribers can shift their accumulated NPS Swasthya funds back to their regular NPS account, following standard NPS exit rules. You won’t be left hanging.

The Role of Health Benefit Administrators (HBAs) and TPAs

You might be wondering — who exactly validates these medical claims and makes sure the money reaches the right place?

That’s where Health Benefit Administrators (HBAs) and Third Party Administrators (TPAs) come in. These are authorised intermediaries empanelled under the scheme who:

  • Verify medical claims and supporting invoices
  • Process withdrawal requests
  • Remit payments directly to hospitals or healthcare providers
  • Manage any surplus after medical expense settlement

Pension Funds running the NPS Swasthya Pension Scheme can also collaborate with FinTech firms and health service providers to make the entire process smoother and more digital. The goal is a seamless, paperless experience — which is something India’s healthcare payment landscape desperately needs.

Insurance Top-Ups: An Added Layer of Protection

Here’s a feature that doesn’t get enough attention: the NPS Swasthya Pension Scheme also allows for insurance top-ups. If a subscriber opts for health insurance coverage as part of the scheme, the insurance premiums are deducted directly from the NPS Swasthya account as a partial withdrawal.

This is a clever integration. Instead of juggling a separate insurance policy and a pension account, subscribers can essentially have their health insurance premiums funded through their dedicated Swasthya corpus. It adds a layer of protection beyond just direct medical expense withdrawals.

NPS Swasthya vs. Regular Health Insurance: What’s the Difference?

People sometimes ask — why not just buy a health insurance policy? It’s a fair question, and the answer is that NPS Swasthya isn’t really competing with health insurance. It’s complementing it.

Here’s a quick comparison to put things in perspective:

Feature NPS Swasthya Pension Scheme Regular Health Insurance
Nature Self-funded savings Premium-based coverage
Corpus ownership Your money, invested Premiums don’t accumulate
Withdrawal flexibility Multiple, no waiting period Claim-based, subject to policy terms
Tax implications Under NPS framework Section 80D deductions
Coverage scope OPD + inpatient Varies by policy
Investment growth Yes, through Pension Funds No
Government involvement PFRDA regulated IRDAI regulated

Think of NPS Swasthya as your health savings cushion, and health insurance as your health expense safety net. Together, they’re a genuinely powerful combination.

Why the NPS Swasthya Pension Scheme Matters for India

To truly appreciate why this scheme is a big deal, you’ve got to understand the healthcare cost landscape in India. Out-of-pocket medical expenses are among the highest in Asia. Families regularly deplete their life savings during medical emergencies. And for those who’re self-employed or in the informal sector — there’s often nothing between them and a financial catastrophe.

NPS Swasthya addresses this in a way that’s sustainable because it doesn’t depend on government funding per patient. It depends on individual savings, wisely invested and thoughtfully protected. It’s self-reliant healthcare planning — and that’s something India badly needs to normalise.

The scheme also demonstrates PFRDA’s growing willingness to innovate within the pension ecosystem. The fact that they’re willing to relax certain withdrawal regulations specifically for healthcare purposes shows a regulatory body that’s listening to what citizens actually need.

Who Should Seriously Consider Joining NPS Swasthya?

Not everyone will find equal value in this scheme. But certain groups would be wise to give it serious thought:

  1. Self-employed professionals — doctors, lawyers, consultants, freelancers who don’t have employer-sponsored health benefits.
  2. Gig economy workers — delivery partners, independent contractors, content creators who often have zero safety net.
  3. Private sector employees over 40 — especially those who already have a decent NPS corpus and can make the 30% transfer.
  4. Senior family members — if you’re planning retirement finances for ageing parents, this could be a structured way to earmark healthcare funds.
  5. Anyone with a family history of serious illness — because planning for predictable risk is just smart financial hygiene.

If you’re already contributing to NPS and healthcare costs keep you up at night, the NPS Swasthya Pension Scheme is probably worth exploring right now.

Frequently Asked Questions (FAQs)

Is the NPS Swasthya Pension Scheme available to government employees?

Yes, government employees can open an account and contribute fresh funds. However, they’re currently excluded from the option to transfer 30% of their existing NPS corpus into the Swasthya account. That transfer benefit is currently limited to private/non-government sector subscribers above 40 years.

What’s the minimum amount needed to open an NPS Swasthya account?

You’ll need to make an initial contribution of ₹25,000. Once you do that, you’re immediately eligible for scheme benefits.

Can I make unlimited withdrawals from the NPS Swasthya account?

There’s no restriction on the number of withdrawals, but each withdrawal is limited to 25% of your own contributions at any given time. Also, your first withdrawal can only happen after your corpus reaches ₹50,000.

Does the money from withdrawals come to my bank account?

No. Funds are paid directly to hospitals, Health Benefit Administrators (HBAs), or Third Party Administrators (TPAs). Any unused amount after settling the bill is returned to your regular NPS Common Scheme Account.

What happens if my hospital bill is more than what I can withdraw?

If the medical expenses in a single inpatient instance exceed 70% of your total NPS Swasthya corpus, you’re allowed to exit the scheme with a 100% lump sum payout — regardless of the corpus size. This is the premature exit provision for serious medical emergencies.

Is NPS Swasthya a replacement for health insurance?

Absolutely not. It’s meant to complement your existing health coverage, not replace it. Think of it as a dedicated healthcare savings buffer that works alongside your insurance policy.

What if PFRDA discontinues this scheme?

Since it’s running as a pilot (Proof of Concept), there’s a possibility it may not become permanent. If discontinued, you can transfer your accumulated NPS Swasthya funds back to your regular NPS Common Scheme Account under standard exit rules.

Who are Health Benefit Administrators (HBAs)?

These are authorised intermediaries appointed under the scheme to verify medical claims, process withdrawal requests, and ensure that payments go directly to healthcare providers. Pension Funds may also collaborate with FinTech companies and TPAs for this purpose.

Can NRIs join the NPS Swasthya scheme?

Yes, the scheme is open to both resident and non-resident Indian citizens, provided they hold or open a Common NPS Account and meet KYC requirements.

How is the money in the NPS Swasthya account invested? 

Your contributions are invested by empanelled Pension Funds under the Multiple Scheme Framework (MSF) guidelines — the same way your regular NPS corpus is managed. So your health savings are also growing over time.

Conclusion

The NPS Swasthya Pension Scheme is one of those rare policy moves that actually makes you think — why didn’t we do this sooner? India has had pension reform, and India has had health scheme reform. But weaving them together, thoughtfully and systematically? That’s new territory, and PFRDA deserves credit for taking the plunge.

Of course, it’s still a pilot, and a few rough edges remain — most notably the exclusion of government employees from the corpus transfer benefit. But as a concept, NPS Swasthya is genuinely promising. It’s practical, it’s flexible, and it addresses a real problem that millions of Indians face every single year.

If you’re already an NPS subscriber, this is the perfect time to seriously consider adding an NPS Swasthya layer to your financial planning. And if you’re not yet part of the NPS ecosystem at all, this might just be the nudge you needed. Medical expenses don’t send appointment reminders — but with NPS Swasthya, at least your financial preparedness can stay one step ahead.

Silver Loan – How to Apply for Silver Loan in India?

Silver loans are becoming famous nowadays. A silver loan is a secured loan where you pledge your silver ornaments or silver coins as collateral to get instant funds. The option of a silver loan is available from 1st April 2026. You can get 75-85% of the silver mark value as a loan. The maximum limit is 10 Kg of silver.

If you have silver ornaments or coins sitting in your locker, did you know they could help you get cash quickly? A silver loan lets you borrow money by pledging your silver items as security. You don’t have to sell them — you just hand them over temporarily to the lender, get the loan, repay it, and take your silver back.

The Silver loan process in India has become much more structured, transparent, and borrower-friendly. Here is a guide for the silver loan explaining what a silver loan is to how you can apply, how your silver gets valued, and what happens after you repay.

Silver Loan India

What Exactly Is a Silver Loan?

A silver loan is a secured loan. “Secured” simply means you offer something valuable as a guarantee (called collateral) to get the loan. In this case, that valuable thing is your silver — jewellery, ornaments, or coins.

Unlike a personal loan where the lender checks your salary slip, credit score, and bank statement, a silver loan mostly depends on the value of the silver you bring. This makes it much easier for people who don’t have a regular income or a high credit score to still get access to money when they need it.

The lender keeps your silver safely locked away while you use the money. Once you repay the full loan amount along with interest, you get your silver back. If you don’t repay, the lender has the right to sell the silver to recover the loan amount.

Who Can Apply for a Silver Loan?

The eligibility for a silver loan is quite simple and inclusive. Here’s who qualifies:

Age: You must be at least 18 years old. There is generally an upper age limit too, which varies by lender but is typically around 70–75 years.

Nationality: You must be an Indian resident. Non-Resident Indians (NRIs) are usually not eligible.

Ownership of Silver: You must legally own the silver you are pledging. You can’t pledge someone else’s silver without their consent.

KYC Compliance: You need to complete basic identity verification as required by RBI norms.

Silver Quality: Your silver must meet the purity standards defined by the lender. Low-quality or heavily mixed silver may not be accepted.

One of the best things about a silver loan is that there is no income requirement. Whether you are a housewife, a farmer, a small shopkeeper, a student, or a salaried employee — if you have eligible silver, you can get a loan.

What Types of Silver Are Accepted?

Not all silver items are accepted. Here’s a clear breakdown:

Generally Accepted:

  • Silver jewellery (necklaces, bangles, anklets, earrings, rings, etc.)
  • Silver coins issued by banks or authorised refiners
  • Silver idols or religious items (depending on lender policy)
  • Household silver items like silver plates or glasses (at select lenders)

Generally Not Accepted:

  • Silver bars or bullion
  • Industrial-grade silver
  • Digital silver or Silver ETFs
  • Silver with unclear ownership or origin
  • Items with non-silver metals making up a large portion of the weight

If you’re unsure whether your silver will be accepted, simply visit the lender’s branch and ask before applying. Most lenders are happy to do a quick check for you.

Documents You Need for a Silver Loan

One of the biggest advantages of a silver loan is the minimal paperwork. You don’t need to collect a stack of documents. Here’s what you’ll typically need:

Identity Proof (any one):

  • Aadhaar Card (most widely accepted)
  • PAN Card
  • Voter ID Card
  • Driving Licence
  • Passport

Address Proof (any one):

  • Aadhaar Card (if it has your current address)
  • Utility bill (electricity, water, gas) — not older than 3 months
  • Bank passbook with current address

PAN Card: Required if your loan amount crosses ₹5 lakh, in line with income tax regulations.

Photograph: One or two recent passport-size photographs.

Silver Items: The physical silver you want to pledge — this is the most important requirement!

No salary slips, no ITR, no bank statements — silver loans are refreshingly simple on the paperwork front.

Banks and Institutions offering Silver Loans

  • Union Bank of India: Offers loans against silver ornaments, particularly for agricultural and short-term needs.
  • Co-operative Banks: Various cooperative banks offer specialized silver loans.
  • NBFCs (Non-Banking Financial Companies): Firms like Muthoot Finance and Emkay Finserv are among those providing loans against silver items.
  • Major Banks: While initial adoption varies, large banks such as HDFC Bank, ICICI Bank, Axis Bank, and State Bank of India are expected to offer these services under the new regulatory framework.

Silver Loan Process — Explained Simply

Here is the complete journey from application to getting money in your account:

Step 1: Submit Your Application

You can start the process by visiting your nearest bank or NBFC branch. Some lenders also allow you to begin your application online or through their mobile app. You fill in a simple form with your basic details — name, address, contact number, and the purpose of the loan.

While the purpose of the loan is usually not strictly verified for silver loans (unlike some government scheme loans), it’s good practice to have clarity on what you’ll use the money for — whether it’s a medical emergency, paying school fees, funding a business need, or home repairs.

Step 2: KYC Verification

Once you submit your application, the lender will verify your identity and address using the documents you’ve provided. This is called KYC — Know Your Customer. It’s a mandatory requirement set by the RBI for all financial transactions.

This step usually takes only a few minutes at the branch. In some cases, if you’re an existing customer of the lender, your KYC may already be on file and this step gets skipped or fast-tracked.

Step 3: Silver Appraisal (Valuation)

This is the most important step in the entire process. A trained appraiser at the lender’s branch will evaluate your silver. Here’s what they check:

Purity Testing: The silver undergoes purity testing using standard methods — typically an acid test or a touchstone test. This tells the lender how pure your silver actually is. For example, 999 purity silver is considered the finest, while most jewellery falls in the range of 800–925 purity.

Weight Measurement: After purity is established, the net silver weight is measured precisely. Lenders usually deduct the weight of any non-silver materials — like plastic stones, thread, or metal fittings attached to the jewellery.

Market-Linked Pricing: The appraiser then checks the current market price of silver per gram. Silver prices change daily based on international commodity markets, so the value is always assessed on the date of your loan application.

Once all three factors are known — purity, weight, and market price — the appraiser calculates the total assessed value of your silver. This is the value that forms the basis of your loan offer.

Step 4: Loan Offer and Key Fact Statement (KFS)

After valuation, the lender will give you a loan offer. This will include:

  • The loan amount you are eligible for
  • The interest rate (usually expressed as an annual percentage)
  • The processing fee (if any)
  • The loan tenure (how long you have to repay)
  • The repayment options available

Importantly, as per the 2026 RBI-aligned norms, lenders are required to share a Key Fact Statement (KFS) with every borrower. Think of the KFS as a simple, clear summary of your loan — written in plain language so you know exactly what you are agreeing to. It mentions the effective cost of the loan, any hidden charges, and your rights as a borrower.

Take time to read this document carefully. Ask questions if anything is unclear. A good lender will always be happy to explain.

Step 5: Signing the Agreement and Pledging Your Silver

If you are happy with the loan offer, you sign the loan agreement. This is a legal document that outlines all the terms and conditions of the loan.

At this point, you also formally pledge your silver to the lender. The lender will tag or seal your items and store them securely in their vault or locker. You will receive a receipt or acknowledgment slip listing all the silver items pledged — keep this safely, as you’ll need it when you come to repay and take back your silver.

Step 6: Loan Disbursal

Once the agreement is signed and silver is pledged, the loan amount is transferred to your bank account. Most lenders process silver loan disbursals on the same day — often within a few hours of completing the steps above. This makes silver loans an excellent option for urgent financial needs.

For smaller loan amounts, some lenders may also disburse cash at the branch itself, though digital bank transfer is increasingly the standard method.

How Is the Loan Amount Calculated?

You might wonder — if my silver is worth ₹1,00,000, will I get ₹1,00,000 as a loan? The answer is no. Lenders never give a loan equal to the full value of the collateral. Here’s why and how it works:

Loan-to-Value (LTV) Ratio: This is the percentage of the assessed silver value that the lender is willing to give as a loan. Under standard RBI-aligned guidelines, the LTV ratio for secured loans backed by silver is typically up to 75% of the assessed value.

Simple Example:

Factor Details
Silver weight 200 grams
Purity 925 (standard silver)
Market price on day of loan ₹110 per gram
Net assessed value ₹22,000
LTV (75%) ₹16,500 (maximum eligible loan)

So in this case, you could get up to ₹16,500 as a loan against silver worth ₹22,000. The remaining ₹5,500 acts as a cushion for the lender against any fall in silver prices during your loan period.

Please note that actual rates per gram and LTV percentages vary by lender and change based on daily silver market prices. Always confirm the current rates with your lender on the day you apply.

Interest Rates and Charges

Silver loan interest rates are generally lower than personal loans or credit cards because the loan is backed by collateral. Typical interest rates for silver loans in India range from around 10% to 24% per annum, depending on the lender, the loan amount, and the tenure.

Apart from interest, you may also encounter:

  • Processing Fee: Usually a small flat fee or a percentage of the loan amount (e.g., 0.5% to 1%)
  • Valuation/Appraisal Fee: Some lenders charge for the silver appraisal
  • Late Payment Charges: If you miss an EMI or repayment date
  • Foreclosure Charges: If you want to repay the entire loan before the tenure ends (many lenders waive this)

Always check the KFS for a complete list of charges before signing.

Repayment Options

Silver loans usually come with flexible repayment options. Here are the most common ones:

EMI-Based Repayment: You pay a fixed monthly amount (Equated Monthly Instalment) that includes both the principal and interest. This is the most structured option and helps you plan your budget.

Bullet Repayment: You pay only the interest each month and repay the full principal at the end of the loan tenure. This is helpful if you expect a large cash inflow at a future date.

Overdraft Facility: Some lenders offer a credit line against your silver. You can withdraw money as needed, up to your limit, and pay interest only on the amount you actually use. This is especially useful for business owners with fluctuating needs.

Partial Repayment: Many lenders allow you to make part-payments towards the principal, which reduces your interest burden over time.

Once you repay the full outstanding amount, the lender will return all your pledged silver items to you immediately.

What Happens If You Cannot Repay?

Life is unpredictable, and sometimes people struggle to repay on time. Here’s what usually happens:

If you miss payments, the lender will first try to contact you and offer options like restructuring or extending the tenure. However, if the loan remains unpaid for a prolonged period and the value of your silver falls significantly, the lender has the legal right to auction your silver to recover the outstanding loan amount.

To avoid this situation, always communicate with your lender early if you’re facing difficulties. Most lenders prefer to work out a solution rather than go to auction.

Silver Loan vs. Other Loan Options

Feature Silver Loan Personal Loan Gold Loan
Collateral Required Yes (Silver) No Yes (Gold)
Processing Time Same Day 1–7 Days Same Day
Income Proof Needed Usually Not Yes Usually Not
Interest Rate Moderate Higher Moderate
Credit Score Impact Minimal High Minimal
Loan Amount Based on Silver Value Based on Income Based on Gold Value

Tips Before You Apply

Get your silver weighed at home first. While the lender will weigh it officially, having a rough idea helps you estimate the loan amount you can expect.

Compare lenders. Interest rates and LTV ratios can vary. Check 2–3 lenders before finalising.

Understand the total cost. Don’t just look at the interest rate — factor in processing fees, insurance charges, and late payment penalties.

Read the KFS carefully. It’s designed to protect you. Use it.

Keep the pledge receipt safe. You’ll need it to reclaim your silver.

Repay on time. Timely repayment protects your silver and keeps your credit profile clean.

Conclusion 

A silver loan is one of the quickest and most accessible ways to meet urgent financial needs in India. It doesn’t care about your income, your job status, or your credit history — it only cares about the silver you bring. The process is straightforward, the paperwork is minimal, and the disbursal is often on the same day.

With the 2026 RBI-aligned guidelines now in place, borrowers are better protected than ever before. Lenders are required to be transparent about costs, follow clear valuation processes, and give you a Key Fact Statement so you know exactly what you’re signing up for.

If you have silver at home that’s just sitting idle, a silver loan might be exactly the kind of financial tool you’ve been overlooking.

Global Exposure Through Domestic Funds

US equities have outperformed the Indian market and delivered better returns last year. However, Indian stock market Sensex and Nifty50 have posted negative four percent returns past year. This is the main reason many people are investing globally.

Anyone who wants to expand his/her portfolio globally from India and not able to find the way due to SEBI and RBI restriction this post is for you. In this post I will share details of domestic fund with global exposure.

domestic fund with global exposure

Why Global Exposure Matters More Than Ever in 2026

Just look around – the world economy is not stagnant. India is doing well, especially with its flourishing digital economy and young population; but putting all your investments in India might prove risky. Consider this: when there’s a downturn in the Indian market because of elections, inflation, or external factors, the exposure to global markets will come in handy.

But why is diversification important? Just as having friends in different places can be helpful during bad weather in one place, global exposure allows you to diversify the risks among other economies, currencies, and sectors. US technology companies can be thriving when Indian Information Technology is facing tough times, and vice versa.

Furthermore, with the fluctuating rupee, having global exposure helps you protect yourself from currency risks. Many domestic funds invest in investments denominated in dollars, and therefore, when the rupee depreciates, your returns see an increase. That is brilliant, isn’t it? By 2026, the world is expected to change politically, technologically, and environmentally, and thus global exposure is a must.

Why Pure International Funds Got Tricky

You might wonder, “Why not just go for pure international funds?” Well, RBI and SEBI have set overall limits on overseas investments by Indian mutual funds – around $7 billion industry-wide, with caps per AMC. When these limits hit, new subscriptions often get paused or restricted. Many investors found themselves locked out during hot market phases.

That’s where domestic schemes shine. They’re not bound by the same strict overseas caps because their primary focus stays on Indian assets. They allocate a portion – say 10-30% – to foreign stocks or global funds. This setup gives you global exposure legally and seamlessly through regular SIPs in rupees. No LRS (Liberalised Remittance Scheme) hassles, no extra tax complications at entry. Sounds like a win, right?

Top Domestic Indian Schemes Offering Global Exposure

Let’s talk specifics. Here are some standout domestic schemes that smartly blend Indian roots with international flair. Remember, past performance isn’t a guarantee, but these have caught investors’ eyes for their balanced approach.

Parag Parikh Flexi Cap Fund: The Balanced All-Rounder

This one’s a favorite among investors who want global exposure without going overboard. With around 10-12% in international stocks like Microsoft, Alphabet, and Amazon, it offers a solid mix. The fund managers pick high-quality businesses globally while keeping the bulk in promising Indian companies.

Why do people love it? Low churn, experienced team, and consistent returns even during volatile times. If you’re starting your journey toward global exposure, this could be your gateway. Minimum SIPs are affordable, making it accessible for salaried folks.

DSP Multi Asset Allocation Fund: Diversification on Steroids

Want more than just equities? DSP’s multi-asset fund throws in equities, debt, gold, and yes, significant global exposure – often up to 20%. It invests in overseas equities and might even tap into commodities or bonds abroad.

Imagine your money working across asset classes and borders! During uncertain times, this fund’s flexibility helps it navigate rough patches better than pure equity plays. Investors eyeing retirement or medium-term goals often pick this for its smoother ride.

SBI Focused Fund: Quality Picks with a Global Twist

SBI Focused isn’t a multi-cap in the traditional sense; it concentrates on high-conviction ideas, including international ones (around 11-12%). You get exposure to strong global brands alongside Indian winners.

It’s not for the faint-hearted who chase every trend, but if you trust active management, this fund delivers that precious global exposure through carefully chosen overseas bets.

Edelweiss Technology Fund and Other Sectoral Plays

Tech enthusiasts, listen up! Funds like Edelweiss Technology have pushed overseas allocation higher – sometimes over 25% – into global tech giants. Similarly, healthcare-focused domestic funds tap into international pharma and biotech.

These aren’t for everyone, but if your portfolio lacks sector diversity, they add that global exposure punch. Just don’t go all-in; sectoral funds can swing wildly.

ICICI Prudential Commodities Fund and Hybrid Options

Commodities aren’t just local anymore. Some domestic hybrids allocate to global mining, energy, or metal companies, giving indirect global exposure. DSP Value Fund is another one often mentioned for its 10%+ international holdings, focusing on undervalued opportunities worldwide.

How These Schemes Actually Deliver Global Exposure

You might ask, “How does a ‘domestic’ fund invest abroad?” Great question! Most use the Foreign Portfolio Investor (FPI) route or invest in overseas ETFs and mutual funds as feeders. For example, a domestic FoF might park money in a US index tracker without you dealing with foreign brokerages.

This structure keeps things simple. Your KYC stays Indian, transactions happen in rupees, and taxation follows domestic mutual fund rules (equity-oriented if over 65% in equity). Long-term capital gains over one year get taxed favorably. Easy peasy!

Benefits That’ll Make You Rethink Your Portfolio

  • Risk Reduction: Markets don’t crash in sync. Global exposure cushions blows.
  • Growth Potential: Access to innovative sectors like AI, semiconductors, and EVs that might be underrepresented in India.
  • Currency Hedge: Rupee depreciation can sweeten returns.
  • Convenience: Invest via apps like Groww, Zerodha Coin, or direct AMC platforms. No forex worries.
  • Inflation Beater: Global assets, especially quality equities, have historically outpaced inflation over decades.

Who wouldn’t want that?

Potential Risks and Smart Ways to Handle Them

No investment is foolproof. Currency volatility can hurt if the rupee strengthens sharply. Geopolitical tensions – think US-China trade spats – affect global holdings. Management fees might be slightly higher for funds with overseas research needs.

Plus, overexposure to one region (say heavy US tilt) could backfire if that economy slows. Solution? Start small with SIPs, review annually, and don’t exceed 20-30% of your total portfolio in these for global exposure. Consult a financial advisor if your goals are complex.

Step-by-Step: How to Start Investing Today

  1. Assess Your Goals: Short-term? Long-term? Risk appetite?
  2. Open an Account: Demat or mutual fund folio if you don’t have one.
  3. Research Funds: Check latest factsheets for current global exposure percentages.
  4. Start SIP: Even ₹500-1000 monthly builds habit.
  5. Monitor: Use apps for alerts, but avoid daily tinkering.
  6. Rebalance: Once a year or when allocations drift too much.

Simple, right? No need for fancy tools.

Real Investor Stories: Learning from Others

Take Ramesh, a software engineer from Bangalore. He missed the international fund boom but parked money in Parag Parikh Flexi Cap. “I sleep better knowing part of my savings rides with global tech leaders,” he says. His portfolio stayed steadier during the 2025 market dips.

Or Priya, a teacher saving for her daughter’s abroad studies. Hybrid funds with global exposure helped her corpus grow while keeping volatility in check. These aren’t made-up tales – countless middle-class Indians are quietly benefiting.

Comparing Domestic Global Exposure vs Pure International Options

Pure international funds offer higher direct global exposure, but face subscription halts. Domestic ones provide moderate but reliable access. Returns? Domestic blends often lag in strong bull markets abroad but shine in balanced conditions.

Expense ratios are competitive. Liquidity? Excellent in domestic schemes. For most retail investors, the domestic route wins on convenience.

Tax Implications You Should Know

Equity-oriented domestic funds (65%+ equity) enjoy indexation benefits? Wait, rules evolve, but generally, LTCG over ₹1.25 lakh taxed at 12.5% without indexation for equity. Debt portions follow slab rates if holding under 3 years. Always check latest ITR guidelines or consult a CA. Better safe than sorry!

Future Outlook: What’s Next for Global Exposure in India?

By late 2026 and beyond, more AMCs might increase overseas sleeves as regulations ease or demand grows. Themes like climate tech, biotech, and space economy will drive global exposure opportunities. Indian investors are getting savvier – expect innovation in these hybrid products.

Conclusion

Missed out on international funds? Don’t sweat it. These domestic Indian schemes have opened doors to global exposure in a practical, regulated, and exciting way. By blending the stability of Indian markets with the dynamism of the world economy, they offer a balanced path to wealth creation.

Whether it’s Parag Parikh’s thoughtful picks, DSP’s multi-asset magic, or sectoral tech plays, opportunities abound. The key? Start today, stay disciplined with SIPs, and keep learning. Your future self – dreaming of financial freedom with a globally diversified portfolio – will thank you.

Remember, investing is a marathon, not a sprint. Embrace global exposure wisely, and watch your money work harder across borders. Happy investing, folks! What’s stopping you now?