Blog Page 19

EGR – Electronic Gold Receipts – New Gold Investment Option in India

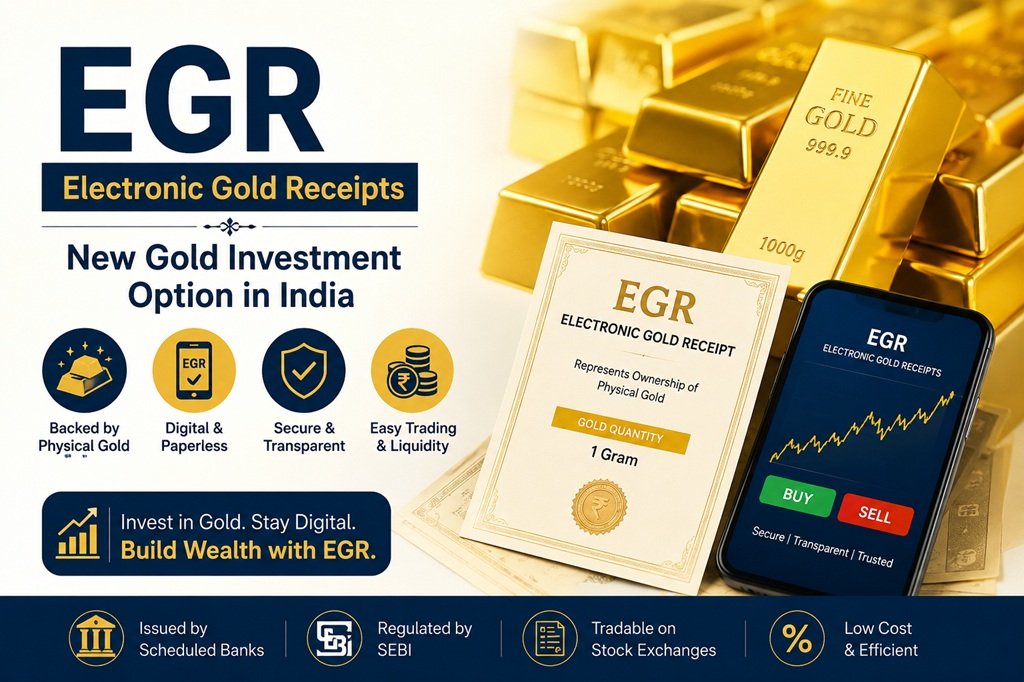
EGR (Electronic Gold Receipts) is new gold investment option in India introduced by the National Stock Exchange of India (NSE). EGR is demetallized form of receipts that physical gold is stored in the SEBI-accredited vaults.

When it comes to investing in gold, most of the people go for buying gold physically in terms of jewelry, gold coins, or gold bars. Few people opt for Gold ETF or SGB (Digital Gold). Physical and Digital Gold both have their own advantages and drawbacks. The new option EGR brings the best of both worlds, and it is government-approved and controlled.

In case you wish to learn more about EGRs, read on in this blog. You will discover what is EGR, the way they function, the salient features, and ways to invest in gold.

Electronic Gold Receipts

What is Electronic Gold Receipt (EGR)?

Electronic Gold Receipts (EGRs) are digital representations of physical gold held in SEBI-approved vaults. While the case with Gold ETFs is different, EGRs provide the facility for taking possession of physical gold within certain limitations.

 Instead of storing gold in its tangible form, people can trade EGRs in the stock market (as they do with stocks). This makes it easier and more secure for Indians to invest in gold.

Every EGR certificate comes with an equal amount of real gold in standard purity. If required, one can even convert EGR to gold.

Key Features of Electronic Gold Receipts

Regulator – Securities and Exchange Board of India (SEBI)
Segment – EGR segment on National Stock Exchange of India (NSE)
Asset Class – Securities under SCRA, 1956
Ecosystem – SEBI, Exchanges, Clearing Corporations, Depositories, Vault Managers
Trading – Buy/sell like shares on stock exchange
Settlement – T+1 cycle
Depositories – Hold EGR in demat & manage settlement
Vault Managers – Handle gold deposit, storage & withdrawal
Market Timings  – Mon–Fri: 9:00 AM to 11:30 PM / 11:55 PM*
Margin  – VaR + ELM + MTM
Participants – Retail investors, jewellers, traders, refineries
Product Options – Multiple units (1kg to 100mg) in 999 & 995 purity

 EGR vs Physical Gold vs Gold ETFs

The EGR is a receipt for physical gold traded on an exchange, which provides liquidity and physical delivery options. The physical gold provides ownership but entails storage and manufacturing costs. Gold ETFs are financial products that follow the price movements of gold without providing physical delivery.

The following are the distinctions between Gold EGR, Physical Gold, and Gold ETFs.

Electronic Gold Receipts (EGR) Physical Gold Gold ETF
Form Digital (demat) Physical (jewellery, coins, bars) Digital (fund units)
Backing Backed by physical gold in vaults Direct ownership of gold Tracks gold prices (no direct ownership)
Trading Traded on the NSE and BSE Not exchange-traded Traded on stock exchanges
Minimum Investment Flexible (small units like grams) Higher (depends on form) Flexible (1 unit onwards)
Physical Delivery Yes (on request) Already physical No
Liquidity High Low to moderate High
Storage Stored in SEBI-approved vaults Self-storage required Managed by AMC
Costs Storage & transaction charges Making charges, storage cost Expense ratio
Safety High (regulated by Securities and Exchange Board of India) Risk of theft/storage issues High (regulated market)

Step-by-Step Process to buy EGR

Step 1: Get Demat and Trading Account

The investors need to possess a demat account and trading account from a registered stockbroker by SEBI to trade in NSE EGRs since these are traded through stock exchanges.

Step 2: Do the KYC Verification Process

KYC stands for know your customer process that needs to be fulfilled by investors in terms of documents like PAN card, Aadhaar card, bank details, and proof of address for accessing the stock trading services.

Step 3: Find Out if Your Broker Offers EGR Services

As NSE EGRs represent a newer investment category, therefore, certain stockbrokers may not yet offer facilities for NSE EGRs trading. The investors may follow the below procedure to find out if their broker is offering EGR services.

Login to their trading app or website

  • Check if there are EGR symbols listed on the platform of NSE
  • Find out if their broker has enabled the EGR trading segment

Step 4: Finding NSE EGR Contracts

After confirming that the trader can trade in EGR contracts through the broker’s platform, now he can check for different NSE EGR contracts based on quantity denominations. These are 1 kg, 100 gm, 10 gm, 1 gm, and 100 mg.

Step 5: Issue a Buy Request

The value of EGR is affected by the market prices of gold within India and other international locations. After choosing the denomination of EGR to be bought, investors can then do the following:

  • Enter the quantity
  • Get the real-time market price linked with gold
  • Place an order during trading hours

Step 6: Credit EGRs to Demat Account

Once the trade process is complete, the acquired EGR will be deposited into the demat account of the investor. As for the settlement process in NSE EGRs, it presently uses the T+1 structure wherein settlement occurs on the next business day after the trade.

Step 7: Keep, Track, or Liquidate

Because EGRs can be traded on exchanges, transparency in terms of liquidity and pricing is maintained. Therefore, EGRs may be held as gold investment and sold any time within market hours.

Tax on EGR

According to the tax law 2023, there will be no capital gains tax if the gold becomes electronic gold receipt or vice versa.

It should be remembered that capital gains tax applies only in case of redemption. Therefore, if someone makes gains through electronic gold receipt, then that person will have to pay capital gain on physical gold price.

Conclusion

Electronic gold receipts on the National Stock Exchange present an advanced solution that enables investors to trade gold virtually yet backed with actual gold holdings within regulated storage facilities.

Those interested in a more transparent and exchange-based form of gold investments may find NSE EGRs quite significant in the context of India’s gold investment landscape.

What Is a Lien Amount? How to Remove

Have you ever logged into your bank account and noticed that your available balance is less than your actual balance? And the bank shows something called a “lien amount” against your account — but gives no clear explanation? If this has happened to you, you are not alone. Thousands of people across India encounter this situation every year, and most of them have no idea what it means or what they should do next.

This guide explains everything you need to know about lien amounts — in simple, everyday language. We will cover what a lien is, why banks place it on your account, how it affects your money, and most importantly, how you can get it removed.

Lien Amount

What Is a Lien Amount?

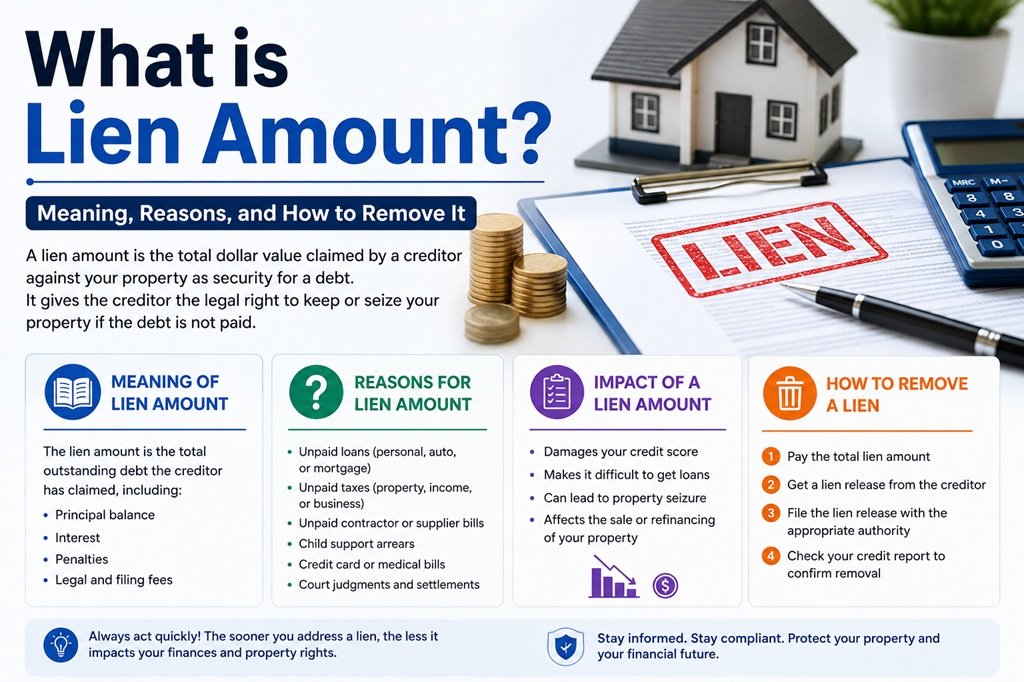
Let us start with the basics. A lien amount is a portion of money in your bank account that the bank has temporarily frozen. You can see this money in your account balance, but you cannot withdraw it, transfer it, or use it in any way — until the lien is lifted.

Think of it this way: imagine you have Rs. 50,000 in your savings account. The bank places a lien of Rs. 15,000 on your account. Your total balance still shows Rs. 50,000, but your “available balance” drops to Rs. 35,000. The Rs. 15,000 is locked — you cannot touch it.

Banks do this as a safety measure. When you owe money to the bank — whether it is an unpaid loan EMI, a pending credit card bill, or something else — the bank wants to make sure it can recover what is owed. Freezing a portion of your funds is their way of protecting themselves.

Lien Amount in Banking

In the world of banking and finance, the term “lien” has a broader meaning. It refers to a legal right that one party (usually a lender or government authority) has over someone else’s property or funds, to secure the repayment of a debt or fulfilment of an obligation.

When it comes to home loans, for example, the bank does not just freeze cash in your account — it places a lien on the property itself. This means the bank has a legal claim on your house until the entire loan is repaid. In India, the Reserve Bank of India (RBI) oversees the rules around liens, and banks are required to follow strict guidelines about when and how they can place one.

For savings or current accounts, a lien is usually a temporary hold on a specific sum of money. Once the underlying issue is resolved — such as clearing an overdue bill — the bank removes the lien and your full balance becomes available again.

Common Reasons Why Banks Place a Lien on Your Account

There are several reasons why your bank might freeze a portion of your funds. Here are the most common ones, explained in plain language:

  • Unpaid Loan EMIs: If you have taken a home loan, personal loan, or any other type of loan, and you miss an EMI payment, the bank may place a lien on your linked savings account. This ensures that the bank can recover the overdue amount directly from your account if needed.
  • Overdue Credit Card Bills: If your credit card outstanding balance remains unpaid for a long time, the bank may freeze an equivalent amount in your savings account. This is especially common when your credit card and savings account are with the same bank.
  • Minimum Balance Violations: Some savings accounts require you to maintain a minimum monthly average balance. If you fall below this threshold repeatedly and fail to pay the resulting penalty, the bank may place a lien on your account.
  • Unpaid Taxes or Government Dues: Government authorities like the Income Tax Department can instruct banks to place a lien on your account if you have outstanding tax liabilities or unpaid government dues. This is a legal measure and the bank has no choice but to comply.
  • Fixed Deposit (FD) Linked Overdraft: If you have taken an overdraft or loan against your fixed deposit and have not repaid it, the bank may mark a lien on the FD amount. In some cases, it can extend to your savings account as well.
  • Fraudulent or Suspicious Transactions: If the bank detects unusual activity in your account — such as large unexplained transfers or suspected fraud — it may temporarily freeze a portion of your funds while it investigates the matter.
  • Court Orders or Legal Disputes: In cases where you are involved in a legal dispute, a court may direct the bank to freeze your account or a specific amount within it. This is an involuntary lien and remains in place until the court issues a new order.
  • Cheque Dishonour Penalties: If you have issued a cheque that bounced due to insufficient funds and the resulting penalty or legal dues remain unpaid, a lien may be placed on your account.

Types of Liens — Understanding the Difference

Not all liens are the same. Depending on how and why a lien is created, it can be classified into several types:

Type of Lien How It Is Created Common Example
Voluntary Lien Created with the borrower’s consent Pledging property as collateral for a home loan
Involuntary Lien Imposed without consent, by law or court order Tax lien imposed by the Income Tax Department
Specific Lien Applies to one particular asset Bank’s claim on a car in a vehicle loan default
General Lien Applies to all assets held by the bank Bank recovers dues from any account in the bank
Statutory Lien Created by law or regulation Lien by GST authorities for unpaid indirect taxes
Equitable Lien Imposed by a court in case of fraud or breach Court-ordered freeze in a property dispute case

How Does a Lien Affect You?

A lien does not just limit your access to funds — it can create a ripple effect across your financial life. Here is how it may impact you:

  • Restricted Access to Funds: The most immediate effect is that a portion of your money becomes inaccessible. You cannot withdraw, transfer, or spend the frozen amount.
  • Failed Auto-Debit Transactions: If you have set up automatic payments for EMIs, insurance premiums, or utility bills, and your available balance drops below the required amount due to the lien, these transactions may fail. This can lead to late payment charges and further damage your financial standing.
  • Impact on Your Credit Score: If the lien is the result of missed EMI payments or loan defaults, it will likely be reported to credit bureaus like CIBIL, CRIF, or Equifax. This can cause your credit score to fall, making it harder to get loans or credit cards in the future.
  • Difficulty in Closing Accounts: You cannot close a bank account if there is an active lien on it. The lien must be removed first before any account closure can happen.
  • Psychological Stress: Seeing money in your account that you cannot use is stressful, especially during a financial emergency. Understanding and resolving the lien quickly is important for your peace of mind.

How to Check If Your Account Has a Lien

Before you can resolve a lien, you need to confirm that one exists and find out the reason behind it. Here are three easy ways to check:

  1. Net Banking: Log in to your bank’s internet banking portal. Go to the account summary or balance details page. If a lien is active, you will see a separate line item showing the lien amount alongside your available balance.
  2. Mobile Banking App: Open your bank’s official app and check your account balance. If the “total balance” and the “available balance” are different, the difference is typically the lien amount. Some apps also show a dedicated “lien details” section.
  3. Visit the Branch: If you are unsure about what you see online, visit your nearest bank branch and speak to the customer service officer. Ask them specifically why a lien has been placed and what the exact amount is.
  4. Passbook or Bank Statement: Request a physical passbook update or download your bank statement. Lien markings may appear as a notation or in the remarks column of recent transactions.

Step-by-Step Process to Remove a Lien Amount

Now for the part that matters most — how do you actually get the lien removed? Follow these steps carefully:

Step 1 — Find Out Why the Lien Was Placed: Contact your bank (by phone, app, or in person) and ask for a clear explanation. You need to know the exact reason and the amount before you can take any action.

Step 2 — Clear Your Outstanding Dues: If the lien is due to unpaid EMIs, credit card bills, or penalty charges, settle the full outstanding amount as soon as possible. Keep the payment receipt or transaction reference number safely.

Step 3 — Obtain the Required Clearance Documents: If the lien is due to unpaid taxes or a legal order, you will need to submit a no-dues certificate or court clearance to the bank. Get these documents from the relevant authority (such as the Income Tax Department or the court).

Step 4 — Submit a Written Request to the Bank: Write a formal letter or submit a written application to the bank, stating that you have cleared your dues and requesting removal of the lien. Attach all relevant payment proofs and clearance documents.

Step 5 — Follow Up and Confirm: After submitting your request, follow up with the bank to track the progress. Ask for a confirmation or acknowledgement in writing once the lien is removed.

Step 6 — Verify the Update on Your Account: After the bank confirms the removal, log in to your account and verify that the available balance now matches your total balance. If the lien amount is still showing, contact the bank immediately.

How Long Does It Take to Remove a Lien?

The time required to remove a lien depends on the type of lien and the bank involved. Here is a general guide:

Bank Type Typical Processing Time
Public Sector Banks (e.g., SBI, PNB, Bank of Baroda) 5 to 7 working days
Private Banks (e.g., HDFC, ICICI, Axis Bank) 3 to 5 working days
Small Finance Banks and Digital Banks 24 to 72 hours
Lien placed by court order Depends on court — can take weeks or months
Lien placed by Income Tax Department 7 to 30 days after clearance is filed

Keep in mind that delays can happen if there are missing documents, processing backlogs, or discrepancies in the payment records. Always follow up proactively and do not assume the lien has been removed without verifying it yourself.

What Happens If the Lien Is Not Removed Even After You’ve Paid?

Sometimes, even after you have cleared your dues, the lien may not be removed automatically. This is a common frustration that many customers face. If this happens to you, here is what you should do:

  • Contact the bank in writing: Send a formal email or letter to the branch manager and escalate to the grievance redressal officer if necessary.
  • Quote your payment reference: Always mention the transaction ID, date, and amount when following up. This makes it easier for the bank to verify your payment.
  • Approach the Banking Ombudsman: If the bank does not resolve the issue within 30 days of your complaint, you have the right to approach the Reserve Bank of India’s Banking Ombudsman.
  • Seek legal advice: In extreme cases — especially if the lien is linked to a court dispute — you may need to consult a lawyer to get the hold lifted.

A lien that remains after the debt is cleared can block you from selling property, refinancing a loan, or even closing your account. It is important to act quickly and not let the matter drag on.

Lien vs. Account Freeze

Many people confuse a lien with a complete account freeze. While they are similar in some ways, there is an important difference:

Feature Lien Amount Account Freeze
What is blocked? Only a specific portion of funds The entire account and all transactions
Can you use remaining funds? Yes, you can use balance above the lien No, all transactions are blocked
Who imposes it? Bank, government, or courts Usually courts or regulatory authorities
Common cause Unpaid EMIs, bills, or taxes Serious legal disputes, suspected fraud, or RBI orders
Resolution Clear dues or provide documents Requires court order or regulatory clearance

Tips to Avoid a Lien on Your Bank Account

Prevention is always better than cure. Here is how you can avoid a lien being placed on your account in the first place:

  • Pay your EMIs and credit card bills on time: Set up auto-debit or reminders to ensure you never miss a due date.
  • Maintain the minimum balance: Always keep your account balance above the required minimum to avoid penalties.
  • File your taxes on time: Delayed or incorrect tax filings can attract penalties and government-imposed liens.
  • Monitor your accounts regularly: Check your bank account at least once a week to spot any unusual deductions or lien markings early.
  • Keep your contact details updated: If your bank has your correct phone number and email address, they can alert you before a lien is placed.
  • Avoid dormant accounts: Dormant accounts are more prone to compliance-related holds. Keep all your accounts active.
  • Resolve disputes quickly: If you are in any financial or legal dispute, try to resolve it as early as possible to prevent a court-imposed freeze or lien.

Frequently Asked Questions (FAQs)

Q: Can a bank place a lien without informing me?

Yes, technically a bank can place a lien without prior notice in some situations, especially when it is required by a court or government authority. However, most banks will send an SMS or email notification. If you notice a lien on your account without any communication, contact the bank immediately.

Q: Will a lien amount affect my credit score directly?

A lien itself does not appear on your CIBIL report. However, the underlying cause — such as missed EMIs or loan defaults — does affect your credit score negatively. Resolving the reason for the lien quickly will prevent further credit score damage.

Q: Can I withdraw the lien amount in an emergency?

No. The lien amount is completely inaccessible until the bank removes it. Even in a genuine emergency, the bank cannot allow withdrawal of the frozen funds. You can only use the balance above the lien amount. This is why it is important to resolve liens as quickly as possible.

Q: How do I know the lien has been successfully removed?

The simplest way is to check your net banking or mobile app. If the available balance equals your total balance, the lien has been removed. You can also visit the branch and ask for a written confirmation.

Q: Can a lien be placed on a joint account?

Yes. If one of the account holders has a financial obligation that triggers a lien, the bank may freeze the joint account even though the other holder has no dues. This is an important risk to keep in mind when operating a joint account.

Conclusion

A lien amount can be confusing and stressful when you first encounter it, especially if no one explains what it means. But as you now know, it is simply a temporary hold placed by the bank to secure an unpaid obligation — and it can be resolved by addressing the root cause.

The key steps are straightforward: find out why the lien was placed, clear your dues or provide the necessary documents, and formally request the bank to lift the hold. Most liens are resolved within a week once you take the right action.

The best long-term strategy is to stay on top of your financial obligations — pay your EMIs on time, clear your credit card bills before the due date, file your taxes correctly, and monitor your bank accounts regularly. If you do these things consistently, you are unlikely to ever face a lien on your account.

And if a lien does appear, remember — it is not the end of the world. It is a solvable problem. Act quickly, stay informed, and do not hesitate to escalate to the RBI Ombudsman if the bank is not cooperative.

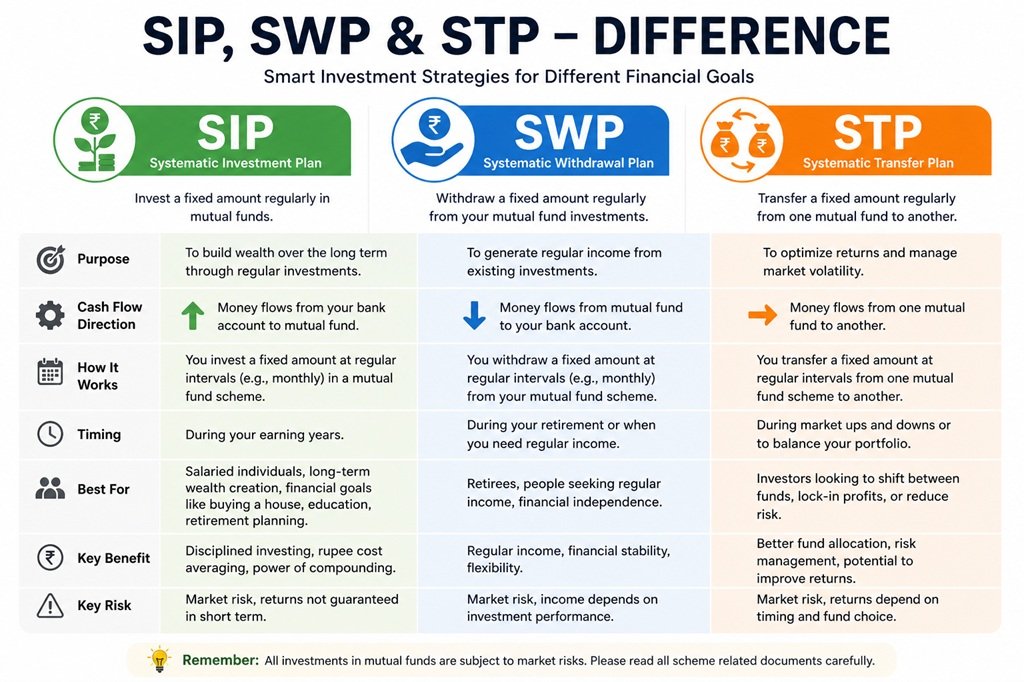
SIP, SWP & STP – Difference

If you have spent any time reading about mutual funds, you have probably come across the terms SIP, SWP, and STP. They sound similar. They all have the word Systematic in them. And they all involve mutual funds. So it is easy to get confused.

But here is the thing — each of these three plans serves a completely different purpose. One is for building wealth. One is for spending it. And one is for moving it around smartly. Once you understand the difference, you will know exactly which one applies to your situation.

Let us break each one down in plain language — no jargon, no confusion.

SIP STP SWP

1. SIP – Systematic Investment Plan

Think of a SIP like a recurring deposit, but for mutual funds. You commit to investing a fixed amount of money at regular intervals — usually every month — and the money automatically gets invested into a mutual fund of your choice.

So if you decide to invest Rs.5,000 every month in an equity mutual fund, that amount will be deducted from your bank account on a fixed date and used to buy units of the fund at that day’s price (called the NAV, or Net Asset Value).

Why SIP is so popular

The beauty of SIP is that it removes two of the biggest problems that investors face: the pressure to time the market and the need for a large lump sum to start.

With a SIP, you invest the same amount regardless of whether the market is up or down. When markets are low, your Rs.5,000 buys more units. When markets are high, it buys fewer. Over time, this averages out your cost of buying — a concept called Rupee Cost Averaging. It means you do not need to stress about market timing.

The second superpower of SIP is compounding. When your mutual fund earns returns, those returns get reinvested. Over time, you start earning returns on your returns. It is a snowball effect — small to begin with, but powerful over the long run.

A quick example

Imagine you invest Rs.5,000 every month starting at age 25. By the time you are 55, assuming a 12% annual return, you could have accumulated over Rs.1.76 crore — even though your total investment was only Rs.18 lakh. That is the power of 30 years of compounding.

Who should use SIP?

  • Salaried individuals who want to invest a portion of their income every month
  • Young investors who are starting their wealth-building journey
  • Anyone who wants a disciplined, stress-free way to invest
  • People saving for long-term goals like retirement, children’s education, or buying a home

Key facts about SIP

  • You can start with as little as Rs.100 per month
  • You can pause, increase, decrease, or stop your SIP anytime
  • Most mutual fund platforms allow you to set up a SIP in minutes
  • You can have multiple SIPs running at the same time in different funds

2. SWP – Systematic Withdrawal Plan

Now let us flip the script. If SIP is about putting money in regularly, SWP is about taking money out regularly. It is the reverse of SIP — and it is incredibly useful for people who have already built a corpus and now need a steady income from it.

Here is how it works: You invest a large amount (a lump sum) into a mutual fund. Then you instruct the fund to pay you a fixed amount every month (or quarter). The fund sells the required number of units to give you that cash, and the rest stays invested and continues to grow.

A practical example

Say you have retired with a corpus of Rs.50 lakh. You put this in a balanced or debt mutual fund and set up a SWP to pay you Rs.25,000 every month. Each month, the fund redeems just enough units to pay you Rs.25,000 and the remaining corpus continues to earn returns.

If your fund earns at least 6–7% per year, your corpus might sustain itself for many years, or even grow while you withdraw. This makes SWP a smarter alternative to simply keeping your money in a savings account or fixed deposit.

Why SWP is better than just withdrawing manually

You might wonder — why not just redeem money when you need it? The answer is discipline and tax efficiency. SWP automates the process so you do not accidentally spend more than planned. And because only a portion of each withdrawal is profit (the rest is your original capital), you often pay less tax compared to putting money in a fixed deposit and paying tax on the full interest.

Who should use SWP?

  • Retirees who need a monthly income from their investments
  • Anyone who has received a large sum (inheritance, bonus, property sale proceeds) and wants to convert it into a steady income stream
  • Investors who want to fund regular expenses like EMIs, children’s school fees, or household costs
  • People who want to preserve their capital while still withdrawing from it

Types of SWP

  • Fixed Amount SWP: You withdraw a set amount every period (e.g., Rs.20,000/month)
  • Appreciation SWP: You only withdraw the profit/gains, leaving your original investment untouched
  • Fixed Units SWP: You redeem a fixed number of units each time, regardless of the NAV

3. STP – Systematic Transfer Plan

STP is a little different from the first two. It does not involve your bank account at all. Instead, it is about moving money between two mutual funds within the same fund house — automatically and at regular intervals.

Think of STP as a bridge between funds. You park your money in a safer fund (like a liquid or debt fund) first. Then, over time, you gradually move it into another fund (like an equity fund) in smaller chunks.

Why would you want to do this?

Let us say you receive a year-end bonus of Rs.5 lakh and you want to invest it in an equity mutual fund. But equity markets are volatile — putting all Rs.5 lakh in at once means if the market drops right after, you immediately lose money.

STP solves this problem. You invest the full Rs.5 lakh in a liquid fund first (which is low-risk and still earns 5–7%). Then you set up a STP to transfer Rs.50,000 per month into your equity fund. Over 10 months, your entire bonus moves into equities gradually — while earning returns in the liquid fund in the meantime.

This gives you the benefit of Rupee Cost Averaging (just like a SIP) without leaving your lump sum sitting idle.

STP is essentially a SIP with existing funds

The key difference from a SIP is the source of money. In a SIP, money comes from your bank account. In a STP, money comes from another fund you already own. The destination (equity fund) does not care — it receives regular investments either way.

Who should use STP?

  • Investors who receive a large lump sum and want to reduce market risk
  • People shifting from conservative to aggressive investments as their risk appetite changes
  • Investors who are nearing a goal and want to move from equity to debt gradually (reverse STP) to protect their gains
  • Anyone who wants the benefits of a SIP but is starting with a lump sum

Types of STP

  • Fixed STP: A fixed amount moves from one fund to another each time
  • Capital Appreciation STP: Only the profits from the source fund get transferred, keeping the principal safe
  • Flexible STP: The transfer amount varies based on market conditions — more units transferred when markets are low, fewer when high

SIP vs SWP vs STP

Feature SIP SWP STP
Full Name Systematic Investment Plan Systematic Withdrawal Plan Systematic Transfer Plan
What it does Invests money regularly into a fund Withdraws money regularly from a fund Moves money from one fund to another
Purpose Build wealth over time Generate regular income from corpus Shift investments between fund types
Direction Money flows IN Money flows OUT Money moves BETWEEN funds
Best for Young earners, wealth builders Retirees, income seekers Lump sum investors, risk managers
Typical frequency Monthly / Weekly Monthly / Quarterly Monthly / Quarterly
Tax on gains? Yes, on redemption Yes, on each withdrawal Yes, each transfer is a redemption

Tax Implications

All three plans have tax implications, and it helps to understand them upfront.

SIP Taxation

Each SIP instalment is treated as a separate investment. When you redeem, each instalment’s holding period is calculated individually. For equity funds, gains held for more than 12 months are taxed at 12.5% (Long Term Capital Gains on amounts above Rs.1.25 lakh per year). Gains held for less than 12 months are taxed at 20% (Short Term Capital Gains). For debt funds, all gains are taxed as per your income tax slab.

SWP Taxation

Every SWP withdrawal redeems units from your fund. Only the profit portion is taxed — the part that represents your original investment is returned tax-free. The same LTCG and STCG rules apply depending on how long the fund has been held. This often makes SWP more tax-efficient than bank FDs, where the entire interest income is taxable.

STP Taxation

This one catches many investors off guard. Every transfer in an STP is treated as a redemption from the source fund. So if your liquid fund has made gains, those gains are taxable every time a transfer happens. The good news is that liquid funds held for over 3 years qualify for indexation benefits (for debt funds under old tax rules) — though recent tax changes mean debt fund gains are now taxed at your slab rate. Always consult a tax advisor for your specific situation.

Which One is Right for You?

The answer depends entirely on where you are in your financial life:

Choose SIP if: You are earning a regular income and want to build wealth steadily over time. SIP is the most popular entry point into mutual fund investing, and for good reason — it is affordable, flexible, and incredibly powerful over the long run.

Choose SWP if: You have already accumulated a corpus and want to convert it into a regular income. SWP is ideal for retirees or anyone who needs predictable cash flow without liquidating all their investments at once.

Choose STP if: You have a large sum to invest but are nervous about putting it all into equities at once. STP lets you start safe, earn something on the waiting money, and gradually shift into higher-growth assets.

The Smart Move

Here is the thing — SIP, SWP, and STP are not competitors. They are different tools for different phases of life. And a well-rounded financial plan often uses all three:

  • In your 20s and 30s: Use SIP to steadily build your wealth
  • When you receive a lump sum: Use STP to deploy it into equities smartly
  • In your 50s and beyond: Gradually shift from SIP to SWP as your focus moves from wealth creation to income generation

Think of it as a financial journey: SIP helps you climb the mountain, STP helps you navigate tricky terrain, and SWP lets you enjoy the view from the top — sustainably.

Final Thoughts

The words systematic and plan in all three names are there for a reason. All three strategies reward discipline and consistency. None of them require you to be a market expert or watch stock prices every day.

Whether you are just starting out with a Rs.500 monthly SIP, deploying a bonus through an STP, or living off decades of savings through a SWP — the key is to start, stay consistent, and let time do its work.

Get a Credit Card Without CIBIL Score in India

If you’ve ever tried to get a credit card for the first time in India, you’ve probably run into this frustrating situation: the bank asks for your CIBIL score, but you don’t have one because you’ve never taken a loan or used a credit card before. It feels like a catch-22. The bank won’t give you a card without a score, and you can’t build a score without a card.

You’re not alone. Millions of Indians — students, young professionals, homemakers, freelancers, and even people who’ve only ever used cash and debit cards — find themselves in this exact situation. The good news? It is absolutely possible to get a credit card without a CIBIL score. You just have to take a slightly different route.

This guide breaks down every option available to you, explains how each one works, and helps you figure out which path makes the most sense for your situation. Let’s start from the beginning.
Credit Card without CIBIL Score

What is a CIBIL Score and Why Do Banks Ask for It?

A CIBIL score is a three-digit number between 300 and 900. It’s calculated by TransUnion CIBIL, one of India’s four main credit bureaus, and it tells banks and lending companies how reliable you are when it comes to repaying borrowed money.

The higher the number, the better. A score of 750 or above is generally considered excellent. Anything below 650 makes banks nervous. And if you have no score at all — because you’ve never borrowed money in your life — banks have nothing to go on. From their perspective, lending to you is a risk because they don’t know how you behave with borrowed money.

This is why so many first-time applicants get rejected. It’s not that you’re a bad borrower — it’s that the system has no data on you at all. The banking industry calls this being “credit invisible.”

Here’s who typically falls into this category:

  • Students who have never taken an education loan
  • Fresh graduates starting their first job
  • Homemakers who don’t have their own income or loans
  • Self-employed individuals or freelancers just starting out
  • People who have always used cash, UPI, or debit cards only
  • NRIs returning to India after several years abroad

If you belong to any of these groups, don’t worry. There are real, working options for you.

Option 1: Secured Credit Card Against a Fixed Deposit

This is the most reliable and widely available option for anyone starting from scratch. A secured credit card is simply a credit card that is backed by a Fixed Deposit (FD) you open with the bank.

How Does It Work?

You deposit a certain amount of money into an FD with the bank. The bank holds this FD as security — if you ever miss your credit card payments, they can recover the money from your FD. In return, they give you a credit card with a spending limit that is usually 80% to 90% of your FD amount.

For example, if you open an FD of Rs 25,000, the bank will give you a credit card with a limit of roughly Rs 20,000 to Rs 22,500.

What Are the Benefits?

  • No CIBIL score required — the bank’s risk is covered by your FD
  • Your FD continues to earn interest even while it’s backing your card
  • Every bill payment you make gets reported to credit bureaus, helping you build your score
  • After 12 to 18 months of responsible usage, many banks upgrade you to a regular unsecured card and return your FD

What Should You Know Before Applying?

The minimum FD amount varies from bank to bank — some start at Rs 10,000 while others require Rs 25,000 or more. Check the specific requirements of your bank before visiting the branch.

Also, your FD will be locked in for the duration of the card. If you break the FD, your credit card will be cancelled. So only deposit an amount you won’t need urgently.

Most major banks in India offer secured credit cards — HDFC Bank, SBI, ICICI Bank, Axis Bank, and Kotak Mahindra Bank all have variants of this product. You can compare their terms online or walk into any branch to enquire.

Option 2: Add-On Card on a Family Member’s Account

If you have a parent, spouse, sibling, or any close family member who already has a credit card, you can ask them to add you as a secondary cardholder. This is called an add-on card, or a supplementary card.

How Does It Work?

The primary cardholder applies to the bank to add you as a secondary user. The bank issues a card in your name, linked to the primary account. You get your own physical card and can use it for purchases. However, the billing statement comes to the primary cardholder, and they are legally responsible for making all payments.

Why Is This Useful for Building Credit?

Some banks in India report add-on card usage to credit bureaus under the secondary holder’s name as well. This means that if the primary cardholder pays bills on time every month, your credit profile might start getting built too — without you even having your own account.

It’s important to check with the specific bank whether they report add-on card usage to credit bureaus, because not all banks do this.

Things to Keep in Mind

  • The primary cardholder can see all your purchases — so it’s best suited for family relationships with a high level of trust
  • If the primary cardholder ever misses a payment, it could hurt your credit profile too
  • Many banks issue add-on cards for free, while some charge a small annual fee of Rs 500 to Rs 1,000

Option 3: Student Credit Cards

If you’re currently enrolled in a college or university, you’re in luck. Several banks in India have introduced credit cards specifically designed for students. These products are built with the understanding that students have no income and no credit history.

Who Offers Student Credit Cards?

SBI Student Plus Advantage Card is one of the most popular options — it’s available to students who have an education loan with SBI. HDFC Bank and ICICI Bank also offer similar products for students maintaining a minimum balance in their savings accounts.

Some banks tie the student card to the college or university — they set up tie-ups with specific institutions and offer cards to enrolled students as a package.

What Are the Typical Features?

  • Low credit limits — usually between Rs 10,000 and Rs 50,000
  • No income proof required
  • No CIBIL score required
  • Lower interest rates compared to standard credit cards
  • Basic reward points or cashback on everyday purchases

What Are the Eligibility Conditions?

Eligibility varies by bank and card, but common requirements include being between 18 and 25 years old, being enrolled in a recognized college or university, and either having an education loan with the bank or maintaining a minimum balance in your savings account.

Option 4: Credit Card Against Your Salary Account

If you’ve just started working and have a salary account with a bank, this is probably the easiest option for you. Banks that manage your salary account have direct visibility into your income, and many of them proactively offer credit cards to salary account holders — even without a CIBIL score.

How Does It Work?

Log into your net banking portal or mobile app and look for a “pre-approved offers” section. Alternatively, walk into your branch and ask the relationship manager whether you’re eligible for a credit card based on your salary account.

The bank will look at how long you’ve been receiving salary credits, the amount of your monthly salary, and whether your account is in good standing. Based on this, they may offer a card with a limit of 2 to 3 times your monthly take-home salary.

What’s the Advantage Here?

Since the bank already has your income data, the verification process is much faster than a regular credit card application. Approvals can sometimes happen on the same day. You’ll typically need to share your last 3 months’ salary slips or bank statements.

This option works especially well if you’ve been receiving your salary in the same account for at least 3 to 6 months. The more consistent your salary credits, the better your chances of approval.

Option 5: Fintech Cards and Co-Branded Products

Over the past few years, a new wave of fintech companies and digital banks has entered the Indian credit card market. These companies don’t rely solely on CIBIL scores to decide who gets a card. Instead, they look at a much wider picture of your financial behaviour.

What Do Fintech Lenders Look At?

  • Your UPI transaction history — how frequently and how much you transact
  • Your savings and spending behaviour over time
  • Your GST filings, if you’re self-employed or run a small business
  • Your mobile phone bill payment history
  • Employment verification through digital methods

Popular Options in This Space

Several products have made it easier for new-to-credit users to get started. OneCard, backed by FPL Technologies, is a full metal credit card with a simple application process and relatively relaxed eligibility. Slice (now merged with North East Small Finance Bank) offers a card-like product with a “pay in 3” instalment feature and accepts applicants with no credit history. Uni Card is another product that lets you split your bill into monthly instalments interest-free.

It’s important to read the fine print here. Some of these products are technically classified as prepaid cards or buy-now-pay-later (BNPL) facilities rather than traditional credit cards. This distinction matters because not all of them report to credit bureaus the same way a regular credit card does.

Who Is This Best For?

  • Freelancers and gig workers who don’t have a formal salary slip
  • Young professionals who prefer digital-only banking
  • People who’ve been rejected by traditional banks
  • Anyone comfortable managing their finances through an app

What to Do After You Get Your First Card

Getting the card is just the beginning. The real goal is to build a strong credit score over the next 6 to 12 months so you can eventually qualify for better cards, personal loans, home loans, and other financial products at good interest rates.

Here’s what you need to focus on:

Pay Your Bills in Full, Every Month

This is the single most important thing. Pay the full outstanding amount — not just the minimum amount due — before the due date every month. Even one missed or late payment shows up on your credit report and can lower your score significantly. Set up an auto-debit mandate if you tend to forget dates.

Keep Your Credit Utilisation Low

Credit utilisation is the percentage of your available credit limit that you’re using. If your card has a limit of Rs 20,000, try to keep your monthly spending below Rs 6,000 — that’s 30% utilisation. Banks prefer to see that you’re not maxing out your card every month. Lower utilisation signals that you’re in control of your finances.

Don’t Apply for Multiple Cards at Once

Every time you apply for a credit card, the bank performs a “hard inquiry” on your credit report. Multiple hard inquiries in a short period of time can signal financial desperation and lower your score. Apply for one card, use it well for 6 to 12 months, and then think about upgrading or applying for a second card.

Check Your CIBIL Score Regularly

You can check your CIBIL score for free once a year at the official CIBIL website. Many banking apps like HDFC, ICICI, and Axis also show your live score for free within the app. It usually takes 3 to 6 months of regular credit card usage before your first score appears.

Once your score crosses 700, you can start looking at better credit card options with higher limits, travel benefits, lounge access, and cashback programs.

Keep Your Card Active

A credit card that’s never used doesn’t help you build a score. Make at least one or two small purchases every month — groceries, mobile recharge, or fuel — to keep the account active and show the credit bureaus that you’re a regular, responsible user.

Common Mistakes First-Time Credit Card Users Make

Here are some things to avoid, especially in your first year of using credit:

  • Paying only the minimum amount due: This keeps you in debt and attracts interest of 36% to 42% per year on the remaining balance
  • Missing even one payment: A single missed payment can drop your score by 50 to 100 points
  • Sharing your card or OTP with others: Even with family members — misuse can lead to disputes and financial loss
  • Withdrawing cash from your credit card: Cash advances carry extremely high interest rates with no grace period, and they can hurt your credit profile
  • Ignoring your credit card statement: Always review your monthly statement for any incorrect or fraudulent charges

Conclusion

Not having a CIBIL score is a starting point, not a permanent barrier. The credit system in India is designed with a way in for everyone — whether through a secured card, a family add-on card, a student card, or a fintech product.

The most important thing is to start somewhere. Even a small secured credit card backed by a Rs 15,000 FD, used responsibly for 6 to 12 months, can give you a CIBIL score above 700. And once you have that score, a whole world of financial products opens up — better credit cards, personal loans at lower interest rates, and eventually a home loan when you’re ready for it.

Think of your first credit card not as a tool for shopping, but as a financial instrument for building your credit identity. Use it with discipline, pay every bill on time, and within a year you’ll have a credit profile that works in your favour for the rest of your life.

Everyone starts from zero — it’s how you play from there that matters.