Blog Page 144

Download Income Tax Calculator FY 2024-25 (AY 2025-26)

0

Download Income Tax Calculator FY 2024-25 (AY 2025-26) in Excel Format. In the ever-evolving landscape of taxation, staying informed about the latest income tax slabs and efficiently managing your investments can significantly impact your financial well-being. Our Income Tax Calculator for the financial year 2024-25 (Assessment Year 2025-26) is not just a tool; it’s your companion in making informed financial decisions. It is a simple and user-friendly income tax calculator for salaried individuals. This calculator will work for both old and new tax slab rates which were released in 2023 and updated in budget 2024. You can calculate your tax liability and decide on tax-efficient investment options and the suitable tax regime for FY 2024-25.

The calculator is created using Microsoft Excel. Simple Excel-based formulas and functions are used in creating this calculator. Before downloading excel Excel-based income tax calculator let’s get acquainted with the Latest Income Tax Slab for FY 2024-25.

Download Latest Income Tax Calculator FY 2025-26

Income Tax Slabs for FY 2024-25 (AY 2025-26)

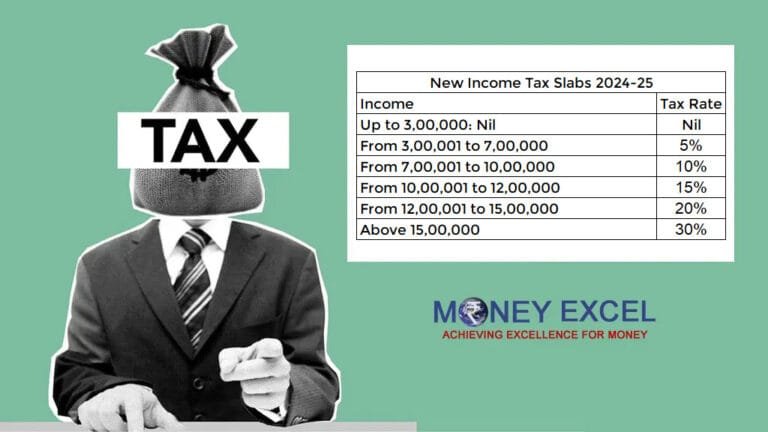
The New Tax Slab FY 2024-25 is given below. This tax slab is as per budget 2024 (New Tax Regime).

Rs 0 to Rs 3 lakh – 0% tax

Rs 3 to 7 lakh – 5% tax

Rs 7 to 10 lakh – 10% tax

Rs 10 lakh to Rs 12 lakh – 15% tax

Rs 12 lakh to Rs 15 lakh – 20% tax

Above Rs 15 lakh above – 30% tax

The old Tax Regime also continued. This means if you want to invest in 80C and save tax you can still use the old tax regime.

The new tax regime announced is more tax efficient and less complicated as you need not exempt any income and remember any complicated tax exemptions such as 80C, 80CCD, 80D, 80DD, etc.

So, still, the taxpayer has two options –

Option 1 – Old Tax Regime – Income Tax Slab 1 – Higher Tax Rate 

The first tax slab is with a higher tax rate. In case an individual salaried or HUF wants to claim exemptions under 80C, 80CCC, 80CCD, 80D, 80DD, 80DDB, etc. the tax rate with a higher rate is applicable. The tax slab in case exemption is claimed is given below.

  Income Tax Slab % Rate  

  Up to Rs. 2,50,000 0%  

  Rs. 2,50,001 to Rs. 5,00,000 5%  

  Rs. 5,00,001 to Rs. 10,00,000 20%  

  Above 10 Lakh 30%  

 Option 2 – New Tax Regime – Income Tax Slab 2 – Lower Tax Rate

The second tax slab is with a lower tax rate. If the taxpayer does not want to claim any exemptions new simplified tax regime is applicable. The new simplified tax regime with a lower tax rate is given below.

  Income Tax Slab % Rate  

  Up to Rs. 3,00,000 – NIL  

  Rs. 3,00,001 to Rs. 7,00,000 – 5% (With Tax Rebate under Sec.87A)  

  Rs. 7,00,001 to Rs. 10,00,000 – 10% (With Tax Rebate under Sec.87A up to 7 Lakh)  

  Rs. 10,00,001 to Rs. 12,00,000 – 15%  

  Rs. 12,00,001 to Rs. 15,00,000 – 20%  

  Rs. 15,00,001 and above – 30%  

The taxpayer is not allowed to claim any exemption under 80C, 80CCC, 80CCD, 80D, 80DD, 80DDB, 80E, 80EE, 80EEA, 80EEB, 80G, 80GG, 80GGA, 80GGC.

However, there are certain deductions you can still claim using the new tax regime and they are as below.

  • Retirement benefits, gratuity etc.
  • Commutation of pension
  • Leave encashment on retirement
  • Retrenchment compensation
  • VRS benefits
  • EPFO: Employer contribution
  • NPS withdrawal benefits
  • Education scholarships

Salaried can select any tax slab. They can switch between old and new tax regime. The option of switching between tax slab is not allowed if an individual or HUF have business income.

Download Income Tax Calculator FY 2024-25 (AY 2025-26)  

Download the latest income tax calculator FY 2024-25 (AY 2025-26) from the link given below and calculate your income tax liability easily. There are two parts to this calculator. Both are given in different sheets.

Part 1 – Calculate Tax as per Higher Tax Rate

The first sheet contains a calculator as per higher tax rate, where deductions & exemptions are allowed.

To calculate your income tax liabilities as per the higher tax rate, you need to provide inputs such as your gross income, and exemption amount. In addition to that, you need to provide information about the investment made by you under various sections. The sheet contains inputs for various sections such as 80C, 80D, 80CCD, etc.

After filling up this detail you need to go to the bottom section where you need to make a selection of applicable tax slab by selecting Male/Female, Senior Citizen and Very Senior Citizen Options.

You will be able to see your tax liability instantly in the Tax Liability with Cess Section.

Part 2 – Calculate Tax as per Lower Tax Rate

The second sheet contains a calculator as per the new tax regime with reducing tax rates, where deductions are not allowed.

To calculate your income tax liabilities as per the new reducing tax rate slab, you need to provide only single input your gross income.

The calculator will calculate tax liability automatically and display it in the Tax Liability with cess Field.

Click on the following image to download the income tax calculator.
Download Income Tax Calculator Excel FY 204-25

Download the Income Tax Calculator in EXCEL Format.

Note – It is not a comprehensive calculator, it is designed to give you a quick idea about your income tax liabilities so that, you can start tax planning. It also helps you to select an appropriate tax slab. This tax calculator does not perform the calculation of Tax Rebate under Sec.87A.

Click Here For Latest Income Tax Calculator FY 2025-26 As per Budget 2025

Key Features of this Income Tax Calculator are given below

  • This calculator is a two-in-one calculator. You can make use of this calculator for calculating tax liabilities as per old as well as new tax slabs.
  • You can compare your tax and decide which tax slab to opt.
  • This calculator is designed exclusively for the salary income only.
  • It is an Excel-based calculator. You can download and use it forever.
  • This calculator is for people with a single home.
  • You will not be able to calculate long-term capital gain tax from this calculator.

I hope this Income Tax calculator for FY 2024-25 will be useful to you.

Do share this calculator and Tax structure with your friends on Facebook & Twitter.

If you have any suggestions share them at info@moneyexcel.com. It will help me to add new features and improve this calculator.
Budget 2024 – Income Tax Slab Rates FY 2024-25

0

The Income Tax Slab and Rates for FY 2024 -25 are changed for the new tax regime. The Income tax slab for the old tax regime remains the same as that of FY 2023-24. Change in Income tax slab and standard deduction announced in budget 2024 by the finance minister Nirmala Sitharaman in her speech. The standard deduction limit is raised for salaried from Rs.50000 to Rs.75000 making an increase of Rs.25000. This means salaried individuals can save Rs.17500 under the new tax regime. 

It is important to note that many changes were made in Budget 2023 in the new tax regime. The income tax slab changes announced in Budget 2023 are effective for the financial year between April 1, 2023, and March 31, 2024, and are set to remain unchanged for FY 2024-25 (April 1, 2024 to March 31, 2025).

We follow a progressive tax system in India, where your income levels determine your tax rates. This means the income tax rate changes and is determined by income bracket. The applicability of these slabs is influenced by factors such as residential status, income amount, type of taxpayer, and age.

income tax slab 2024 - budget 2024

Income Tax Slab Rates FY 2024-25

In Indian taxation, the responsibility falls upon the shoulders of taxpayers to contribute their share based on the income tax slab they inhabit. This intricate structure comprises diverse income ranges, each associated with distinct tax rates. As one ascends the income ladder, so do the corresponding tax rates. The ingenious introduction of the slab system aims at fostering an equitable tax regime within the nation. Notably, alterations to the income tax slab are meticulously executed in alignment with the annual budget proclamation. Embracing these changes ensures a harmonious fiscal landscape and underscores the collective commitment to a progressive and just taxation system. There are three categories under which income tax is divided:-

  • Individuals who are less than 60 years
  • Senior citizens with age of 60 to 80 years
  • Super senior citizens with an age of above 80 years.

Income Tax Slab Rates FY 2024 – 25 – Old Tax Regime

Tax slabs for Individuals below 60 years

Income tax slabs (In Rs)
Income tax rate (%)
Up to 2,50,000 0
2,50,001 – 5,00,000 5%
5,00,001-10,00,000 20%
Above 10,00,001 30%

Tax Slab for Senior Citizen with age of 60 to 80 years

Income tax slabs (In Rs)
Income tax rate (%)
Up to 3,00,000 0
3,00,001 – 5,00,000 5%
5,00,001-10,00,000 20%
Above 10,00,001 30%

Tax Slab for Super Senior Citizen with an age above 80 years

Income tax slabs (In Rs) Income tax rate (%)
Up to 5,00,000 0
5,00,001-10,00,000 20%
Above 10,00,001 30%

Income Tax Slab Rates FY 2024-25 – New Tax Regime 

Income tax slabs (In Rs)
Income tax rate (%)
Up to 3,00,000 0
3,00,001-7,00,000 5%
7,00,001-10,00,000 10%
10,00,001-12,00,000 15%
12,00,001-15,00,000 20%
Above 15,00,001 30%

Cess will be levied at 4% on the income tax amount. Surcharges will be levied on incomes above Rs 50 lakh.

Strategic Financial Planning: Incorporating 1 crore term insurance

For a secure and prosperous future, strategic financial planning is a must. In our country, where speculation and financial aspects are constantly changing, understanding the need for strategic planning is imperative. It is more than setting aside funds; it is tied in with endowing a security net to your near and dear ones, assuring their prosperity when you are no more there. Here’s why consolidating a one crore term insurance plan to your financial plan is essential.

Term Insurance Policy

Integrating one crore term insurance into financial planning

Adding a 1 crore term insurance policy to your financial strategy is not only an instrument but also a need, particularly in our country where our family is considered a cornerstone of one’s life. Read on to understand the reasons behind – 

  • Debt protection

Debt might be a considerable burden for your family, particularly in the non-presence of the fundamental income. A 1 crore term policy covers outstanding commitments such as personal loans, home loans or car loans. It safeguards your family member from the monetary burden and ensures your assets are not forfeited due to your inability to make EMI repayment. 

  • Financial security

A one crore policy offers a financial safety net for the members of your family. In the occasion of the holder’s demise owing to unforeseen scenarios, the sum assured might be adequate to pay the family’s expenditures. It can cover your child’s higher education and daily household expenditures while maintaining a good life standard without compromise. The insurance cover ensures your dependents’ futures are safeguarded even if you are not there anymore. 

  • Affordable premiums

Besides the large sums insured, the benefits of a 1 crore term insurance policy are modest, especially if you begin at a young age. The insurer’s risk decreases when the policyholder is young and healthy. Locking in a low premium early in life may allow you to receive enough coverage without breaking your wallet.

  • Mental peace

Knowing that your near and dear ones will be financially comfortable during your absence offers tremendous mental peace. It enables you to live a life without any frets about your family members’ future financial stability. This peace of mind is a big benefit of having a term policy cover. 

  • Inflation hedge

With the increasing living cost, a huge cover of 1 crore assists in safeguarding the value of the insured fund from inflation. It ensures your dependents’ financial future is secure, with adequate funds to live well in upcoming years.

  • Tax advantages

Making an investment of Rs one crore term insurance covers tax benefits. The premiums paid for the insurance are tax deductible as per Section 80 C and the death benefits availed by the nominees are free of tax as per Section 10 (10D). This makes the term insurance more than a financial protection instrument; it even serves as an excellent tax-saving tool. 

Features to consider when purchasing one crore term insurance.

  • Terms for payment of premium

You can make payment of your premium in a single sum, for a specific length of time or across the course of your policy. Your selection might be impacted by your financial circumstances and income. 

  • Sum assured

Make sure that the sum assured meets your family’s future monetary needs. Factor in their existing lifestyle, future goals, debts, and inflation level. 

  • Claim settlement ratio

This ratio shows the claim percentage settled by the insurer. A higher ratio suggests a better chance of your claim being settled with zero issues, demonstrating the insurer’s good reputation. 

  • Policy term

Select the term insurance policy’s duration that offers cover until an age at which you anticipate your obligations or dependents’ needs would be considerably higher. It is crucial to make sure you are financially secure across your most vulnerable times. 

  • Riders/add-ons

Riders are additional benefits that can be included in a basic insurance policy to offer complete coverage. Such riders might involve critical illness coverage, accidental death benefits, a disability rider, and others. They endow additional security, however at a higher cost. 

  • Flexibility in expanding coverage

Some insurance plans allow you to enhance the amount covered at a specific life event such as childbirth or marriage. This instrument allows your cover amount to grow by your enhancing obligation needs. 

  • Solvency ratio

This ratio evaluates the insurance company’s financial stability as well as its ability to meet long-term obligations. A higher solvency ratio shows financially healthy management, which is essential to ensuring your claim is paid. 

  • Premium waiver benefit

This rider waives future payment if the holder of the policy becomes incompetent or ill, ensuring that the policy is still in existence and lessening the family member’s financial burden. 

  • Tax advantages

Note that the tax advantages of term policies are covered under Sections 80 C and 10 (10D). This can help with smart tax planning.

  • Policy revival period

In the case you fail to pay the insurance premium, your cover might lapse. However, insurers might provide you a grace period during which you can revive your insurance policy. Being aware of your revival terms is essential to avoiding insurance policy lapses. 

  • Payout options

Insurers generally offer many payout options such as monthly income, lump sum, or combination. Select the one that best matches your family member’s needs. 

  • Customer service and support

A good customer care system is required to provide hassle-free service. Check to see if the insurance company has a good track record for customer service and claims payout.

  • Exclusions

Be aware of policy exclusions to minimise surprises during a claim. Common exclusions include suicide within the first year, death as a result of engaging in harmful activities, and so on.

  • Underwriting process

Know how the insurer evaluates your application for an insurance policy, involving the required healthcare tests and the time range for issuing the policy. This assists in drafting well-informed expectations. 

Final thoughts

Adding a 1 crore term insurance policy to your plan is more than just securing considerable funds for the future of your family, it is even about ensuring that their objectives, dreams, and daily needs are met well in your absence. It expresses affection, responsibility, and foresight. As a consequence, while life is unpredictable, having a great term insurance plan ensures that your family’s financial future is covered regardless of what occurs. Make the correct decision now for a peaceful and happy tomorrow. 

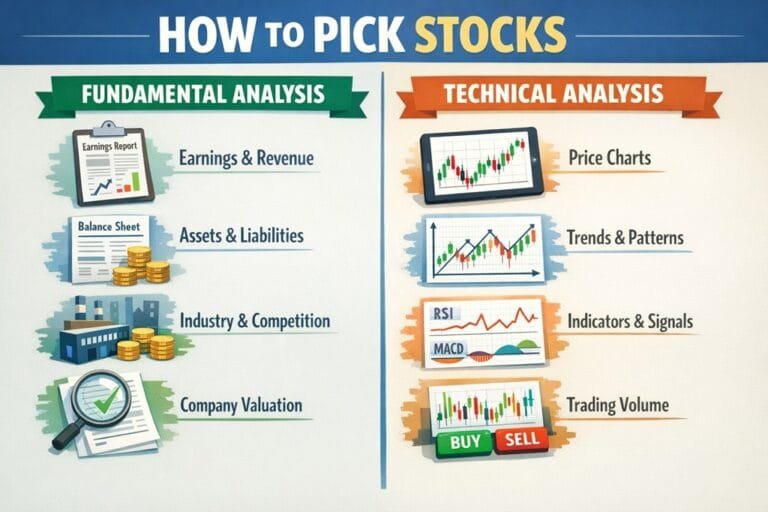
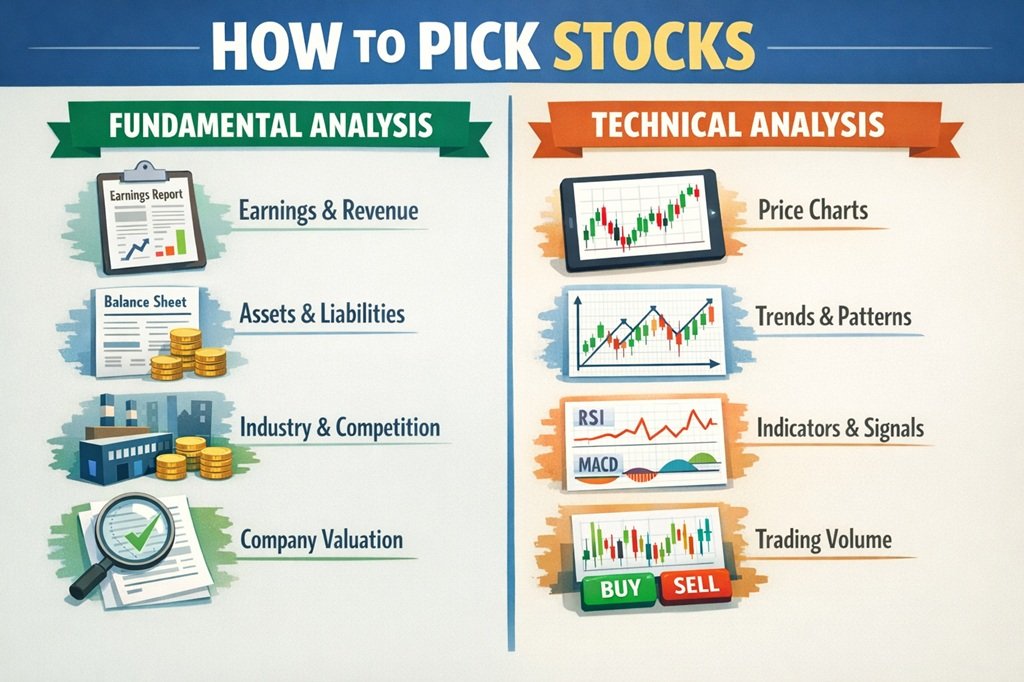
How to Pick Stocks: Fundamental Analysis vs. Technical Analysis

So, you’ve decided to invest in the stock market? Well, welcome aboard the rollercoaster of bull markets, bear markets, and everything in between! But hold your horses! Before you start throwing your hard-earned dollars into the stock market, you’ve got to figure out – How to Pick Stocks.

In the stock market arena, two gladiators often face off in the battle for supremacy: Fundamental Analysis and Technical Analysis. It’s like choosing between Batman and Superman – both have their strengths, but one might be more your style. In this wild west of finance, understanding these two approaches is crucial. So, let’s strap on our financial spurs and mosey on down the stock market street to explore the secrets of How to Pick Stocks: Fundamental Analysis vs. Technical Analysis!

Fundamental vs Technical Analysis

Fundamental Analysis:  

What is Fundamental Analysis?

Imagine you’re a detective, Sherlock Holmes style, piecing together clues to solve a mystery. That’s Fundamental Analysis for you – it’s the art of digging deep into a company’s financials to figure out its true value.

  1. Earnings Per Share (EPS): It’s like the protagonist in our financial story. How much moolah does each share of the company bring in? High EPS? Good. Low? Well, that’s a red flag!
  2. Price-to-Earnings (P/E) Ratio: Think of this as the suspense in our thriller. It tells you how much investors are willing to pay for a share relative to its earnings. A high P/E ratio could mean high expectations!
  3. Dividend Yield: Ah, the twist in the plot. How much cash are you getting back for just holding onto the stock? A juicy dividend yield can be music to your ears!

Why Choose Fundamental Analysis?

  • Long-Term Investing: If you’re in for the long haul, Fundamental Analysis is your trusty companion. It’s like planting seeds and waiting for a bountiful harvest!
  • Understanding the Business: Sherlock didn’t solve crimes without understanding the motives. Similarly, Fundamental Analysis helps you grasp a company’s ins and outs.
  • Value Investing: Ever heard of Warren Buffett? He’s like the Gandalf of investing, and he swears by Fundamental Analysis. It’s all about finding undervalued gems in the market.

Technical Analysis: 

What is Technical Analysis?

Now, if Fundamental Analysis is Sherlock Holmes, then Technical Analysis is the Jedi mind trick of stocks. It’s like looking at a stock’s historical data to predict its future moves. May the force be with you!

  1. Moving Averages: Picture this as the stock’s dance moves. It smoothens out the erratic price movements, helping you see the trend. Is the stock doing the cha-cha or the moonwalk?
  2. Relative Strength Index (RSI): This one’s like checking a stock’s heartbeat. Is it overbought and about to collapse, or oversold and ready to bounce back? RSI reveals the pulse of the market.
  3. Support and Resistance Levels: Think of these as the stock’s bodyguards. Support levels stop it from falling too low, while resistance levels prevent it from soaring too high. It’s like a stock’s personal security detail!

Why Choose Technical Analysis?

  • Short-Term Trading: If you’re more of a day-trading adrenaline junkie, Technical Analysis is your lightsaber. It helps you catch those short-term market waves.
  • Patterns and Trends: Remember that time your friend wore the same lucky socks for a week? Patterns matter, and Technical Analysis helps you identify trends that could lead to profits.
  • Psychology of the Market: Just like a Jedi reading minds, Technical Analysis delves into market psychology. It’s not just about numbers; it’s about understanding what makes traders tick.

Fundamental vs. Technical: The Showdown

Pros of Fundamental Analysis

  • Sturdy Foundation: Fundamental Analysis builds a solid foundation for long-term investments. It’s like constructing a financial fortress – strong and reliable.
  • Real Value: It focuses on a company’s intrinsic value, not just market sentiments. It’s the difference between real gold and fool’s gold.
  • Warren Buffett Approved: If the Oracle of Omaha gives it a thumbs up, it’s got to be onto something, right?

Cons of Fundamental Analysis

  • Time-Consuming: Like reading a 1000-page novel, Fundamental Analysis takes time. If you’re looking for quick wins, you might get bored waiting for the plot to unfold.
  • Market Sentiments Ignored: While it’s great for the long game, Fundamental Analysis might overlook short-term market sentiments. The market can be a moody beast!

Pros of Technical Analysis

  • Quick Wins: If you’re into short-term gains, Technical Analysis is your go-to guide. It’s like having a map for navigating the market’s twists and turns.
  • Visual Representation: Charts and graphs make it easy for visual learners. It’s like watching the stock market’s blockbuster movie in real-time!
  • Adaptable: The market is like a chameleon, changing colors on a whim. Technical Analysis adapts to these changes, helping you stay ahead of the curve.

Cons of Technical Analysis

  • Short-Term Focus: While it’s great for short-term gains, Technical Analysis might miss the forest for the trees when it comes to a company’s long-term potential.
  • Not Always Accurate: The market is as unpredictable as British weather. Technical Analysis might give false signals, leading you down the wrong financial path.

FAQs: Navigating the Stock Market Maze

Q1: Can I use both Fundamental and Technical Analysis?

Absolutely! It’s like having both Batman and Superman on your side. Use Fundamental Analysis for the long-term game plan and Technical Analysis for those quick, strategic moves.

Q2: Which is better for a beginner – Fundamental or Technical Analysis?

It depends on your style. If you’re patient and in it for the long run, Fundamental Analysis is a good start. For adrenaline junkies, Technical Analysis might be more appealing.

Q3: How much money do I need to start investing?

Start small, partner! You don’t need a Scrooge McDuck vault. Dip your toes with what you can afford to lose.

Q4: Is stock picking like gambling?

Not if you know the game! Stock picking requires research and strategy. Gambling is more like rolling dice and hoping for the best.

Q5: How often should I check my stocks?

No need to stalk your stocks like an overprotective parent. Check in regularly but avoid becoming a stock market helicopter mom.

Conclusion: Finding Your Stock Market Mojo

In the realm of stocks, it’s not a battle of good vs. evil; it’s a dance of different approaches. So, when pondering the age-old question – How to Pick Stocks: Fundamental Analysis vs. Technical Analysis – remember, there’s no one-size-fits-all answer.

Fundamental Analysis is your Sherlock Holmes, uncovering the hidden truths of a company’s financials. It’s a slow burn, but oh, the satisfaction of a well-solved mystery! On the flip side, Technical Analysis is your Jedi mind trick, navigating the market’s twists and turns with agility. It’s the adrenaline rush of quick wins and lightsaber-like precision.

In the end, it’s not about picking sides; it’s about finding your stock market mojo. Are you a patient detective, meticulously uncovering financial gems, or a swift Jedi, dancing through market fluctuations with finesse? The choice is yours, partner. May your stocks be ever in your favor! How to Pick Stocks: Fundamental Analysis vs. Technical Analysis – it’s your financial adventure waiting to unfold!