Blog Page 145

How to Start Your Own Profitable Babysitting Daycare Business

Are you the neighborhood’s go-to babysitter? Do kids love your company and parents trust you with their little ones? Well, it might be time to turn your knack for childcare into a profitable venture! Starting your own babysitting or daycare business can be a rewarding journey, both personally and financially. In this guide, we’ll take you through the ins and outs of launching a successful venture in the world of childcare. From creating a cozy space for little tots to managing the business side of things, we’ve got you covered!

Starting a babysitting or daycare business is not just about watching kids; it’s about creating a space where parents feel confident leaving their little ones and where children thrive in a supportive environment. In this article, we’ll explore the ins and outs of establishing a profitable babysitting or daycare service that not only meets regulatory standards but also exceeds the expectations of parents.
daycare business

Understanding the Market

Before diving into the business, it’s crucial to understand the local childcare landscape. Conduct thorough research on the childcare needs in your area, identify your target demographic, and assess the demand for specific services. This information will guide your business decisions and help you tailor your offerings to meet the needs of your community.

Legal Considerations

Navigating the legal aspects of starting a childcare business is vital. Check the licensing requirements in your jurisdiction, secure appropriate insurance coverage, and establish clear policies regarding liability. Complying with these legal considerations ensures the safety of the children in your care and protects your business from potential risks.

Creating a Business Plan

A well-thought-out business plan is the foundation of a successful childcare venture. Define the services you will offer, set a competitive pricing strategy, and outline your marketing and outreach plans. Consider your unique selling points and how you will differentiate your business from others in the market.

Setting Up a Safe Environment

Safety is paramount in childcare. Childproof your facilities, establish emergency protocols, and adhere to health and safety standards. Creating a secure environment not only ensures the well-being of the children but also builds trust with parents.

Staffing and Training

Hiring qualified and compassionate staff is key to providing quality childcare. Implement comprehensive training programs to equip your team with the skills needed to create a nurturing environment. A well-trained staff contributes significantly to the success and reputation of your business.

Technology in Childcare

Embrace technology to streamline your childcare operations. Utilize management software for administrative tasks, implement online scheduling and communication tools to keep parents informed, and explore digital solutions that enhance the overall childcare experience.

Building a Brand

Create a memorable brand for your childcare business. Design a unique logo and branding materials that reflect the nurturing and trustworthy nature of your services. Leverage social media platforms to promote your brand and connect with your community.

Attracting Clients

Launch promotions and discounts to attract initial clients, encourage word-of-mouth referrals through satisfied parents, and establish a strong online presence through a professional website and active social media accounts. Marketing plays a crucial role in building your client base.

Maintaining Customer Relationships

Effective communication with parents is essential. Addressing their concerns promptly, organizing events that involve both parents and children, and seeking feedback help in maintaining positive relationships. Happy parents are more likely to be loyal customers and recommend your services to others.

Financial Management

Implement sound financial practices from the start. Develop a budget, track expenses, and periodically review your pricing strategy based on market trends. Efficient financial management ensures the sustainability and growth of your childcare business.

Scaling Your Business

As your business grows, explore opportunities for expansion. Consider opening additional locations, expanding services, and collaborating with other businesses to offer complementary services. Scaling your business requires strategic planning and a focus on maintaining the quality of your childcare services.

Adapting to Trends

Stay updated on childcare trends and incorporate relevant advancements into your services. Whether it’s adopting new educational approaches or integrating technology, staying current ensures your business remains competitive and continues to meet the evolving needs of families.

Challenges and Solutions

Every business faces challenges. Be prepared to address staffing issues, navigate regulatory changes, and stay ahead of competition. Developing solutions to common challenges will strengthen your business and position you as a reliable childcare provider.

Celebrating Milestones

Take the time to celebrate your business achievements, express gratitude to your staff and clients, and set new goals for the future. Recognizing milestones not only boosts morale but also creates a positive and motivated work environment.

Conclusion

Starting your own babysitting or daycare business is a rewarding journey that requires careful planning and dedication. By understanding the market, complying with legal requirements, and focusing on creating a safe and nurturing environment, you can build a profitable and successful childcare venture.

Frequently Asked Questions

1. How long does it take to start a daycare business?

  The timeline varies, but it typically takes a few months to a year to navigate licensing, set up facilities, and launch marketing efforts.

2. What qualifications do I need to start a daycare?

  Requirements differ by location, but most jurisdictions require CPR certification, background checks, and completion of childcare training.

3. How can I attract parents to my childcare business?

Offering promotions, creating a strong online presence, and encouraging positive word-of-mouth through excellent service can attract parents.

4. What is the ideal staff-to-child ratio in a daycare?

Ratios vary based on age groups, but a common standard is one adult for every four infants and one adult for every ten preschool-aged children.

5. How do I stay informed about childcare trends?

Stay connected to industry publications, attend conferences, and join online communities to stay updated on the latest trends and best practices in childcare.
Digital Loan Scams: Tips to Avoid Them

0

In the ever-evolving landscape of the digital age, where convenience often meets complexity, the rise of digital loans has been nothing short of revolutionary. Need cash urgently? Just a few clicks, and you can have the funds in your account! However, with great convenience comes great responsibility, and unfortunately, it also attracts the attention of unscrupulous individuals seeking to exploit unsuspecting borrowers. In this article, we’ll dive deep into the world of digital loan scams, unraveling the schemes and providing you with actionable tips on how to steer clear of them.

digital loan scam

Unmasking the Digital Loan Scams

Digital Loan Scams: Here’s How You Can Avoid Them – but first, let’s understand what we’re up against. Scammers have become increasingly sophisticated in their tactics, preying on the desperate need for quick cash. From fake loan apps to phishing schemes, they’re leaving no stone unturned. Here’s a breakdown of the most common digital loan scams:

#1 Phishing

Imagine receiving an email or a text message promising an unbeatable interest rate on a digital loan. You click the link, thinking it’s a legitimate financial institution, only to find yourself on a well-crafted fake website. This is phishing at its finest, and it’s one of the primary tools scammers use.

How to Avoid Falling for Phishing Schemes:

  • Double-check the sender’s email address or phone number.
  • Scrutinize the website’s URL for any discrepancies.
  • Contact the financial institution directly to verify the offer.

#2 Fake Loan Apps

Digital Loan Scams: Here’s How You Can Avoid Them, especially when it comes to fraudulent loan apps lurking in app stores. These apps mimic legitimate ones, enticing users with promises of instant loans and minimal documentation. Once you submit your personal information, it’s a goldmine for scammers.

Red Flags to Spot Fake Loan Apps:

  • Check app reviews and ratings for inconsistencies.
  • Research the developer’s information before downloading.
  • Be wary of apps requesting excessive permissions.

#3 Upfront Payment Requests

Digital Loan Scams: Here’s How You Can Avoid Them – by staying vigilant when confronted with upfront payment requests. Legitimate lenders typically deduct fees from the loan amount, but scammers insist on payment before disbursing funds, vanishing once they receive your hard-earned money.

Protect Yourself from Upfront Payment Scams:

  • Refuse to pay any fees before receiving the loan.
  • Research the lender’s reputation and legitimacy.
  • Consult financial experts or friends before committing.

Navigating the Safe Waters: Tips to Protect Yourself

Now that you’re equipped with insights into the sinister world of digital loan scams, let’s focus on arming you with practical strategies to safeguard your financial well-being. Digital Loan Scams: Here’s How You Can Avoid Them, and here’s how you can do it effectively:

#1 Research

When considering a digital loan, the importance of thorough research cannot be overstated. Digital Loan Scams: Here’s How You Can Avoid Them by becoming a savvy researcher:

Steps for Effective Research:

  • Investigate the lender’s reputation online.
  • Read customer reviews and testimonials.
  • Verify the lender’s physical address and contact information.

#2 Scrutinize Terms and Conditions

The devil is in the details, they say, and in the world of digital loans, this holds true. Scammers often hide malicious clauses in the fine print. Digital Loan Scams: Here’s How You Can Avoid Them by being a meticulous reader:

Tips for Analyzing Terms and Conditions:

  • Look for hidden fees or excessive interest rates.
  • Understand the repayment schedule and penalties.
  • Clarify any ambiguous language with the lender.

#3 Keep Personal Information Guarded

Your personal information is your fortress, and guarding it should be a top priority. From your Social Security number to your bank details, scammers are on the lookout for any vulnerability. Digital Loan Scams: Here’s How You Can Avoid Them by being a guardian of your own data:

Best Practices for Protecting Personal Information:

  • Only provide necessary information to legitimate lenders.
  • Use secure and private Wi-Fi connections for online transactions.
  • Regularly monitor your financial statements for unusual activities.

#4 Trust Your Instincts

Intuition is a powerful tool, and if something feels off, it probably is. Digital Loan Scams: Here’s How You Can Avoid Them – by listening to your gut:

Signs Your Instincts Might be Right:

  • Pressure tactics to make hasty decisions.
  • Unprofessional communication or website design.
  • Lack of transparency regarding fees and terms.

FAQs: 

Q1: Can scammers replicate the websites of legitimate lenders convincingly?

Absolutely! Phishing scammers go to great lengths to create websites that mirror legitimate financial institutions. Always double-check the URL and contact the lender directly to verify authenticity.

Q2: How can I differentiate between a real and a fake loan app?

Pay attention to app reviews and ratings. Legitimate apps will have consistent positive feedback, while fake ones might have suspiciously glowing or overly negative reviews. Additionally, research the developer’s information before downloading.

Q3: Are all upfront payment requests a sign of a scam?

While not all upfront payment requests are scams, it’s a significant red flag. Legitimate lenders typically deduct fees from the loan amount, and they won’t ask for payment before disbursing funds.

Q4: Is it safe to apply for a loan online?

Yes, applying for a loan online can be safe if you take the necessary precautions. Research the lender, scrutinize terms and conditions, keep your personal information secure, and trust your instincts.

Conclusion:  

Digital Loan Scams: Here’s How You Can Avoid Them – by being proactive, informed, and vigilant. As the digital world continues to evolve, so do the tactics of scammers. However, armed with knowledge and a healthy dose of skepticism, you can navigate the online lending landscape safely.

Remember, if something seems too good to be true, it probably is. Don’t let the allure of quick cash blind you to potential dangers. By implementing the tips and strategies outlined in this article, you can protect yourself from falling victim to digital loan scams and ensure a secure financial future.

15 Common TA Trading Chart Patterns

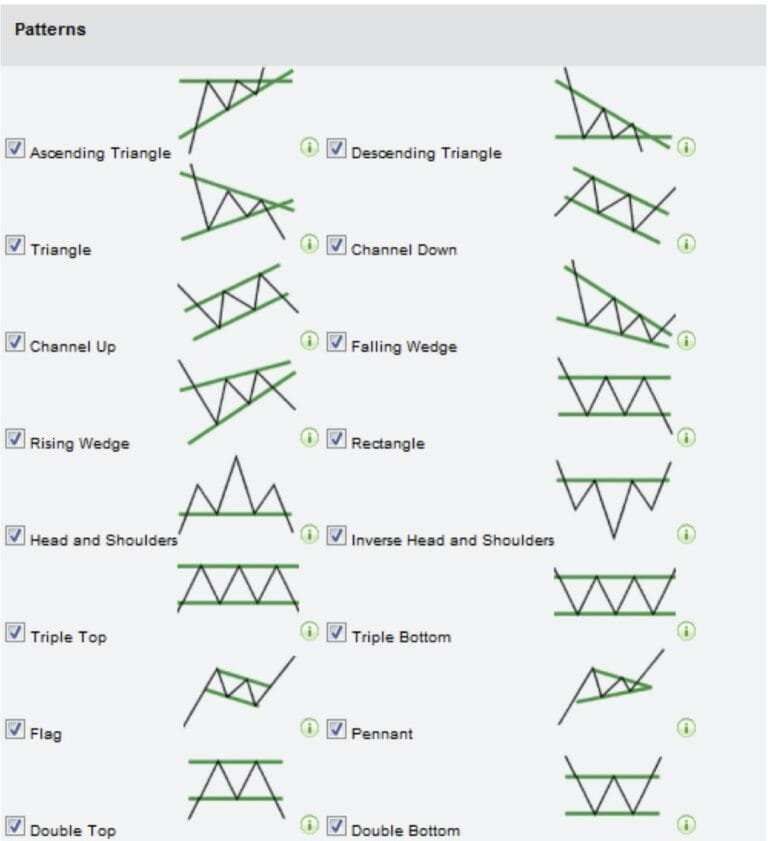
Chart patterns are a subset of technical analysis (TA). Delving into the intricacies of technical analysis (TA), chart patterns stand as a pivotal subset demanding attention for those navigating the complex terrain of the stock market. These patterns not only serve as a compass but also delineate the course of action one should undertake in the ever-shifting landscape of financial markets.

Embarking on a journey into the realm of chart patterns, it becomes evident that these graphical representations wield a profound influence on strategic decision-making. The amalgamation of short and extensive sentences mirrors the ebb and flow of market dynamics, a characteristic often more nuanced in human-authored content compared to its artificial counterpart.

Let us embark on a cerebral exploration of these enigmatic patterns, with a commitment to providing a comprehensive understanding of their nuances. As we navigate this labyrinth of financial insight, be prepared for a revelation that transcends the ordinary.

Technical Analysis Chart Patterns

15 Common Trading Chart Patterns

#1 Tringle

Triangles are among the most popular chart patterns used in technical analysis since they occur frequently compared to other patterns. The three most common types of triangles are symmetrical triangles, ascending triangles, and descending triangles. These chart patterns can last anywhere from a couple of weeks to several months.

#2 Ascending Triangle

An ascending triangle is a chart pattern used in technical analysis. It is created by price moves that allow for a horizontal line to be drawn along the swing highs and a rising trendline to be drawn along the swing lows.

#3 Descending Tringle

A descending triangle is a bearish chart pattern used in technical analysis that is created by drawing one trend line that connects a series of lower highs and a second horizontal trend line that connects a series of lows.

#4 Channel Down

The Channel Down pattern is identified when there are two parallel lines, both moving down to the right across respective peaks (upper line) and bottoms (lower line).

#5 Channel Up

The Channel Up pattern is identified when there are two parallel lines, both moving up to the right across respective peaks (upper line) and bottoms (lower line).

#6 Falling Wedge

Falling Wedge are drawn using two converging trendlines; however, a wedge is characterized by the fact that both trendlines are moving in the same direction, either up or down.

#7 Rising Wedge

The rising wedge pattern is a bearish chart pattern that signals an imminent breakout to the downside. It’s the opposite of the falling (descending) wedge pattern (bullish), as these two constitute a popular wedge pattern.

#8 Rectangle 

Rectangles, formations etched by parallel support and resistance levels, encapsulate a visual representation of market equilibrium—an intricate equilibrium within the financial confines.

#9 Head & Shoulders

Head & Shoulders pattern appears as a baseline with three peaks, where the outside two are close in height, and the middle is highest. The head and shoulders pattern forms when a stock’s price rises to a peak and then declines back to the base of the prior up-move

#10 Inverse Head & Shoulders 

An inverse head and shoulders, also called a head and shoulders bottom, is inverted with the head and shoulders top used to predict reversals in downtrends.

#11 Triple Top

The triple-top pattern occurs when the price of an asset creates three peaks at nearly the same price level. The triple top pattern, a trilogy of peaks converging at nearly identical altitudes, weaves a tale of market resistance, a trifecta of challenges for the discerning trader.

#12 Triple Bottom 

The triple bottom pattern means three equal lows followed by a breakout above the resistance. Conversely, the triple bottom pattern unfolds with three equidistant lows, culminating in a triumphant breakout above resistance—an allegory of resilience in the face of financial challenges.

#13 Flag

Flags are constructed using two parallel trendlines that can slope up, down, or sideways (horizontal). In general, a flag that has an upward slope appears as a pause in a down-trending market;

#14 Pennant 

Pennants are drawn with two trendlines that eventually converge. A key characteristic of pennants is that the trendlines move in two directions—that is, one will be a down trendline and the other an up trendline.

#15 Double Top & Double Bottom 

Double top and bottom patterns are chart patterns that occur when the prices of the stock move in a pattern that is similar to the letter “W”

In the realm of technical analysis, where precision meets complexity, an understanding of these chart patterns serves as a compass for navigating the labyrinthine landscape of the stock market. As we conclude this journey into the cryptic world of financial intricacies, may you find enlightenment in deciphering the enigmatic language of trading chart patterns.

Understanding the Cost Factors of Public Liability and General Liability Insurance

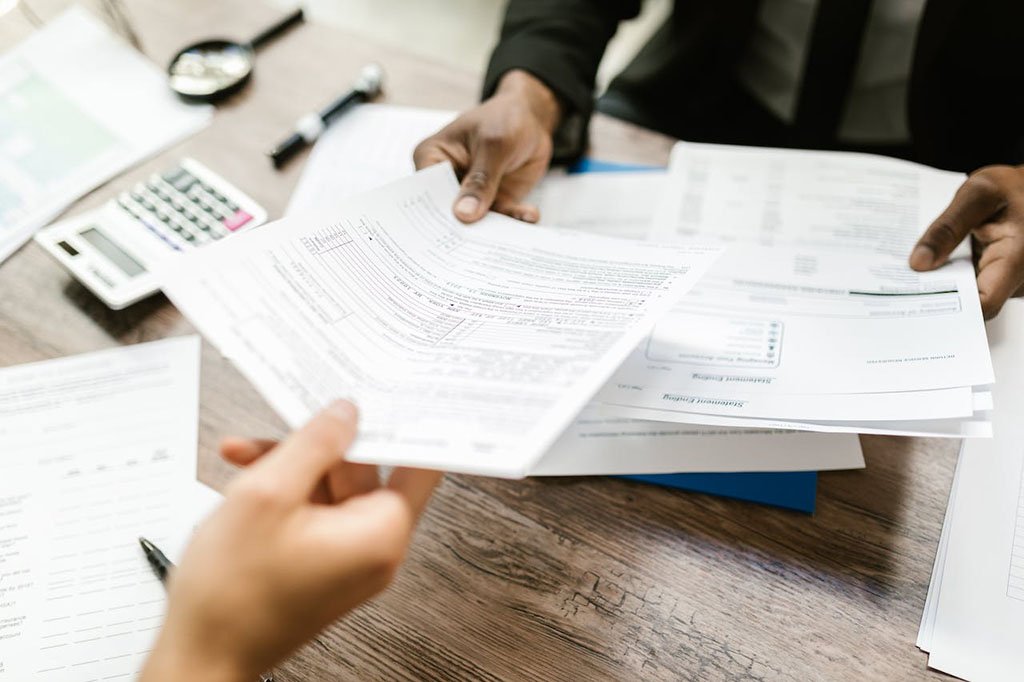
In the complex world of business, navigating through potential risks is an integral part of ensuring long-term success. Among the various risk management tools available, Public Liability Insurance and General Liability Insurance stand out as essential shields against unforeseen events. The difference between public and general liability insurance lies in their coverage scope and specific protections. These insurance policies offer protection from third-party claims arising due to property damage, bodily injury, or advertising injury. However, understanding the cost factors associated with these insurance types is crucial for businesses seeking comprehensive coverage without breaking the bank.

Lability Insurance

Coverage Scope and Limits

One of the primary determinants of the cost of both Public Liability and General Liability Insurance is the scope of coverage and the limits specified in the policy. Public Liability Insurance typically covers incidents where a third party (not an employee) suffers injury or property damage due to your business operations. On the other hand, General Liability Insurance is a broader policy that encompasses public liability but also includes coverage for product liability, completed operations, and advertising injury.

The extent of coverage you choose and the limits set in the policy significantly influence the premium. Higher coverage limits and broader coverage scope generally translate to higher premiums. It’s essential for businesses to assess their specific needs and risks to strike a balance between adequate coverage and cost-effectiveness.

Business Type and Industry Risk

The nature of your business and the associated industry risks play a pivotal role in determining insurance costs. Industries with inherently higher risks of accidents or injuries, such as construction or manufacturing, might incur higher insurance premiums compared to low-risk sectors. Insurers assess the likelihood of claims based on the historical data of similar businesses within the industry, and businesses operating in riskier environments can expect to pay more for coverage.

Moreover, the size and scale of your business matter. Larger enterprises with more extensive operations and a higher number of employees may face elevated risks, leading to increased insurance costs. Insurers often consider factors like annual revenue, payroll size, and the number of locations when calculating premiums.

Claims History and Risk Management Practice

Insurers evaluate a company’s claims history to gauge its risk profile. A business with a track record of frequent or high-cost claims may be viewed as a higher risk, resulting in higher insurance premiums. Conversely, companies with a clean claims history and robust risk management practices may qualify for discounts or lower premiums.

Implementing effective risk management strategies can positively impact insurance costs. This includes maintaining a safe work environment, conducting regular safety training, and adhering to industry best practices. By demonstrating a commitment to minimizing risks, businesses can not only enhance workplace safety but also potentially lower their insurance premiums over time.

Deductibles and Policy Add-Ons

Choosing a higher deductible can be a strategic move to reduce premium costs. A deductible is the amount the policyholder must pay before the insurance coverage kicks in. While opting for a higher deductible can result in lower premiums, it’s essential to carefully evaluate the financial implications for your business in the event of a claim.

Additionally, businesses should consider policy add-ons or endorsements that can enhance coverage based on specific needs. However, each add-on comes at an additional cost. It’s crucial to assess whether the benefits of additional coverage outweigh the extra expense, striking a balance that aligns with the business’s risk tolerance and financial capacity.

Geographical Location

The geographic location of a business plays a crucial role in influencing insurance costs, as it introduces regional disparities in risk factors. Businesses situated in regions susceptible to natural disasters, such as earthquakes or hurricanes, may experience elevated insurance premiums due to the heightened risk of property damage. Additionally, areas with a higher prevalence of legal actions could lead to increased liability insurance costs for businesses facing an elevated risk of lawsuits. Insurers meticulously analyze the local risk landscape, incorporating environmental and legal considerations, to accurately assess and determine insurance premiums tailored to the specific challenges of a given location.

Credit Score and Financial Stability

Surprisingly, a business’s insurance premiums can be impacted by its credit score and financial stability. Insurers often view the financial health of a business as a key indicator of its capacity to fulfill insurance obligations and manage potential claims effectively. A business with a higher credit score and robust financial stability may be rewarded with more favorable premium rates, reflecting the insurer’s confidence in its ability to navigate potential risks. This interplay between financial standing and insurance costs highlights the multifaceted factors that insurers consider when assessing and pricing coverage for businesses.

Final Thoughts

In the complex world of insurance, understanding the cost factors of Public Liability and General Liability Insurance is crucial for businesses aiming to safeguard their operations. By comprehending the elements that contribute to insurance premiums, businesses can make informed decisions that align with their risk management strategies and financial objectives.