Blog Page 100

How Uninsured and Underinsured Motorists Impact Your Car Accident Claim

car accident claim

Car accidents can lead to physical injuries, emotional trauma, and financial strain. Ideally, the at-fault driver’s insurance would cover your losses. But what happens when the driver responsible for the accident doesn’t have enough insurance—or any at all?

This is where uninsured and underinsured motorists complicate the process of filing a car accident claim.

If you’re facing this situation, working with a car accident lawyer can help you navigate these challenges.

Who Are Uninsured and Underinsured Motorists?

Uninsured motorists are drivers who operate a vehicle without any insurance coverage. Underinsured motorists, on the other hand, have insurance, but their coverage limits are too low to compensate for the damages they cause in an accident. The Insurance Information Institute reports that this is a widesfpread issue, with 12.6% of drivers in the U.S. lacking insurance.

For instance, if an accident leaves you with $50,000 in medical expenses and the at-fault driver’s insurance covers only $20,000, you would still face a $30,000 shortfall. This is where uninsured motorist (UM) and underinsured motorist (UIM) coverage can protect you.

The Impact of Uninsured and Underinsured Motorists on Your Claim

Uninsured and underinsured drivers make it harder to recover compensation after an accident. Without proper insurance coverage from the at-fault driver, you may face significant hurdles in covering your medical bills, lost wages, and property damage.

Challenges with Uninsured Motorists

  • Limited Recovery Options: With no insurance to file a claim against, your choices are limited to suing the at-fault driver or relying on your own UM coverage.
  • Financial Hardship: Even if you sue, uninsured drivers often lack the financial means to pay a court-ordered settlement.

Issues with Underinsured Motorists

  • Coverage Gaps: The at-fault driver’s insurance may only cover a portion of your expenses, leaving you to pay the rest.
  • Relying on UIM Coverage: Where you have UIM coverage, it can fill the gap between what the other driver’s insurance pays and your total damages, up to your policy limits.

The Role of Your Insurance Policy

Your insurance policy can help to protect you from the financial risks posed by uninsured and underinsured drivers.

Uninsured Motorist (UM) Coverage

UM coverage helps pay for:

  • Medical expenses
  • Lost wages
  • Pain and suffering

Underinsured Motorist (UIM) Coverage

UIM coverage steps in when the at-fault driver’s insurance isn’t enough to cover your damages. It bridges the gap between their policy limits and your total expenses, up to the limits of your UIM coverage.

Adding UM and UIM coverage to your car insurance policy is a proactive step that can save you from significant financial stress in the future.

Conclusion

Uninsured and underinsured motorists can complicate the process of recovering compensation after a car accident. Their lack of adequate insurance often leaves victims facing financial shortfalls. By securing UM and UIM coverage and seeking advice from a car accident lawyer, you can better protect yourself from these challenges.

Remember, preparation is key to navigating the aftermath of an accident. Review your insurance policy, increase your coverage limits if necessary, and stay informed about your rights to ensure you’re ready for any situation on the road.

Here’s Why Giving Recorded Statements to Adjusters is a Big No

Recorded Statement Adjusters

After an accident, you may receive a call from an insurance adjuster asking for a recorded statement about what happened. They might seem friendly and helpful, but their job is to protect the insurance company’s interests. It’s important to remember that what you say to an adjuster can have a significant impact on your claim.

The adjuster’s goal is to gather information that could weaken your case, even if you are truthful and careful with your words.

To protect your rights and ensure fair compensation, it’s best to avoid giving a recorded statement without first consulting a personal injury attorney. This legal professional can guide you on how to communicate with the insurance company and ensure your case is handled properly.

Below, we’ll discuss why giving a recorded statement is risky and what you should do instead.

Adjusters Can Twist Your Words

One of the biggest risks of giving a recorded statement is that adjusters can take your words out of context. Even if you’re being honest, a simple misstep could be used against you.

Consider the examples below.

  • Unclear wording: Statements like “I feel okay” can be interpreted as downplaying your injuries.
  • Assumptions: Speculating about details you’re unsure of might be framed as factual.
  • Admitting fault: Phrases like “I didn’t see the car” could be twisted to suggest you were responsible.

Insurance companies are trained to find ways to reduce or deny claims, and recorded statements give them a tool to do so.

You Might Not Know the Full Extent of Your Injuries

Right after an accident, it’s common not to know the full extent of your injuries. Some injuries, like whiplash or internal damage, can take days or weeks to appear. If you give a recorded statement too soon, you might inadvertently downplay your condition.

Later, if your injuries worsen, the adjuster may use your earlier statement to argue that the accident didn’t cause your condition.

It’s Their Job to Minimize Payouts

Insurance adjusters are not on your side, no matter how friendly or understanding they seem. Their job is to protect the insurance company’s bottom line. This includes:

  • Offering low settlements
  • Denying liability
  • Using your recorded statement to justify reducing your claim

By avoiding a recorded statement, you prevent them from having ammunition to undermine your case.

What Should You Do Instead?

If an adjuster asks for a recorded statement, you have the right to decline. Here’s what you should do:

  • Stay polite but firm: Decline the request for a recorded statement and let them know you’ll provide information in writing.
  • Refer them to your attorney: If you’ve hired a personal injury lawyer, direct all communication to them.
  • Document everything: Keep records of all conversations with the insurance company, including dates, times, and what was discussed.

Your attorney can handle communications with the adjuster and ensure your case is presented in the strongest possible light.

Why It’s Important to Hire an Attorney

A personal injury lawyer can protect your rights and prevent you from making mistakes that could harm your claim. They can:

  • Communicate with the insurance company on your behalf.
  • Ensure you provide accurate, carefully-worded information.
  • Advise you on what to say and what to avoid.

Most personal injury attorneys work on a contingency basis, meaning you won’t pay unless you win your case. Having a lawyer on your side can make all the difference in achieving a fair settlement.

Conclusion

Giving a recorded statement to an insurance adjuster might seem harmless, but it’s a risky move that can harm your claim. Adjusters are trained to use your words against you. Even a small mistake can reduce your chances of getting the compensation you deserve.

Instead of giving a statement, protect yourself by hiring a lawyer. With the help of an experienced personal injury lawyer, you can navigate the claims process confidently and avoid common pitfalls.

Remember, you have the right to seek fair compensation for your injuries—don’t let an adjuster take that away from you.

Portugal’s Tax on U.S. LLCs: Key Insights for Global Investors

0

In December 2024, Portuguese tax authorities issued Ruling No. 26925, offering groundbreaking clarity on how income from U.S. Limited Liability Companies (LLCs) is taxed under Portuguese law. This ruling is a significant step forward for U.S. expats, Non-Habitual Residents (NHRs), and global investors seeking to navigate the complexities of cross-border taxation between the United States and Portugal. It addresses key ambiguities that have historically surrounded the tax treatment of U.S. LLC income in Portugal, making it a milestone for those looking to optimize their financial strategies.

LLC Tax US

The Complex Landscape of U.S. LLC Taxation

To understand the significance of this ruling, it’s crucial to grasp the historical challenges surrounding the taxation of U.S. LLC income in Portugal. Tax systems in the U.S. and Portugal operate differently, creating inherent complexities:

  • In the U.S.: LLCs are treated as pass-through entities. Profits are taxed at the individual level rather than at the corporate level, offering tax efficiency to members.
  • In Portugal: Portuguese tax law does not automatically recognize the pass-through nature of LLCs, creating uncertainty over how this income should be classified and taxed.

A prior ruling in 2016 provided some clarity but left critical gaps, such as whether NHR status influenced taxation and how LLC ownership structures affected tax treatment. These unresolved issues have complicated tax planning for years.

The 2024 Ruling: A Milestone for Tax Clarity

The 2024 ruling has filled many of these gaps by providing detailed guidance. Here are its key highlights:

Ownership Structure

The ruling analyzed a Delaware-based U.S. LLC taxed as a partnership, owned equally (50:50) by:

  1. A U.S. citizen residing in the U.S.
  2. A Portuguese resident with NHR status.

Nature of Income

The LLC’s income is derived from IT services, with both members actively contributing to the operations. Portuguese authorities classified this income as capital income from a foreign source, explicitly distinguishing it from dividends. Instead, it is categorized as “other income.”

Implications for NHRs

The most impactful takeaway is the confirmation that individuals with NHR status can claim a full exemption on this foreign-sourced income in Portugal, provided the LLC’s management is conducted outside Portugal. This is a game-changer for expats and investors leveraging NHR tax benefits.

Why This Ruling Matters

The 2024 ruling offers unprecedented clarity and consistency, making it easier for taxpayers to plan their finances effectively. Let’s explore the broader implications:

  1. Reinforcement of NHR Benefits

The ruling reinforces the significant tax advantages available under Portugal’s NHR regime. NHR status exempts qualifying foreign income, such as U.S. LLC income, from Portuguese taxation. For many expats, this means substantial tax savings.

  1. Alignment with Prior Precedents

While the 2016 ruling laid the groundwork, its lack of detail left room for interpretation. The 2024 ruling builds on this foundation, offering more detailed guidance that ensures consistency and reliability for taxpayers.

  1. Certainty for Investors

This clarity benefits not only individual taxpayers but also global investors exploring Portugal as a destination for relocation or investment. The ability to predict tax outcomes reduces risk and encourages investment.

Key Considerations: Effective Management and Permanent Establishment

The ruling does not explicitly address the concepts of effective management or permanent establishment. However, when read in conjunction with the 2016 decision, for income to qualify as foreign-sourced (and thus eligible for NHR benefits), the LLC’s management must be conducted outside Portugal.

This raises an important point for taxpayers: ensuring that the operational and managerial decisions of the LLC are demonstrably carried out in the U.S. or another jurisdiction outside Portugal. Failure to do so could jeopardize the favorable tax treatment.

Why This Ruling Is a Game-Changer

For U.S. expats and global investors, the 2024 ruling delivers:

  1. Transparency: Detailed guidance on how U.S. LLC income is taxed under Portuguese law.
  2. Tax Optimization: Confirmation of the NHR exemption for foreign-sourced income.
  3. Certainty: Reduced ambiguity in cross-border taxation, enabling better financial planning.

Leveraging Professional Guidance for Maximum Benefits

Navigating the intricacies of cross-border taxation requires specialized expertise. Consulting with tax professionals who understand the nuances of U.S. and Portuguese tax laws is crucial. Such guidance ensures compliance, maximizes tax benefits, and minimizes risks.

The 2024 ruling on U.S. LLC income taxation in Portugal is a landmark development that offers much-needed clarity and consistency. For U.S. expats, NHRs, and global investors, this is an opportunity to optimize financial strategies and take full advantage of Portugal’s favorable tax regime.

Whether you’re an expat planning to move to Portugal or an investor exploring opportunities in the country, staying informed about tax regulations is essential. By leveraging expert guidance and adopting best practices, you can navigate the complexities of cross-border taxation with confidence.

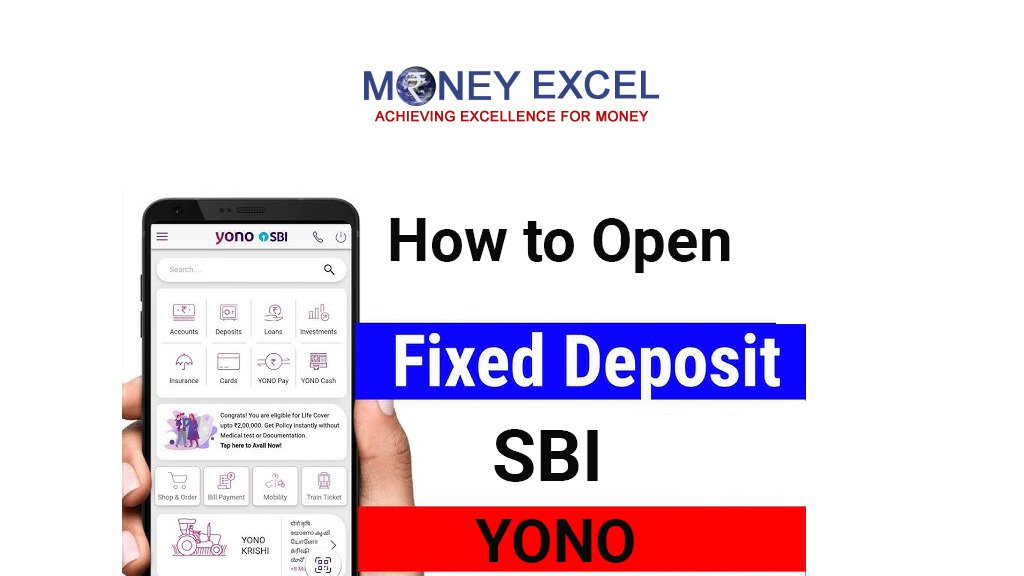
How to Open a Fixed Deposit Using the SBI YONO App

0

Are you ready to put your money to work? A fixed deposit (FD) is a fantastic way to earn steady returns while keeping your funds secure. Thanks to the YONO app—short for “You Only Need One”—from State Bank of India (SBI), opening an FD has never been easier. No more waiting in long bank queues or dealing with piles of paperwork. Everything you need is right at your fingertips. Let’s walk through the process step-by-step so you can get started on your savings journey today.

Open YONO Fixed Deposit

Why Choose the YONO App for Fixed Deposits?

First off, why should you even bother with the YONO app? Here’s the deal:

  • Convenience: You can open, manage, and close your FD from anywhere, anytime.
  • Quick Process: The entire setup takes just a few minutes.
  • Paperless: Say goodbye to physical forms—everything is digital.
  • Attractive Interest Rates: SBI offers competitive rates to grow your savings.
  • Customizable Tenure: Choose an FD term that suits your financial goals.

Sound good? Let’s dive into the nitty-gritty details of how to get started.

Step-by-Step Guide to Open an FD Using the YONO App

Step 1: Download and Log In to the YONO App

First things first, make sure you have the YONO app installed on your smartphone. If you haven’t downloaded it yet, it’s available on both the Google Play Store and the Apple App Store. Once it’s installed, log in using your SBI internet banking credentials or register as a new user.

Pro Tip: Don’t forget to set up MPIN for quick and secure access!

Step 2: Navigate to the Fixed Deposit Section

Once you’re logged in, here’s what you need to do:

  1. On the home screen, tap on the Deposits section.
  2. You will be able to see the Deposit Calculator, Fixed Deposits, Recurring Deposits, My Dreams, and Other Deposits section.
  3. From the list of options, select Fixed Deposit.
  4. You’ll be directed to a page that gives you an overview of your existing FDs (if any) and an option to create a new one.

Step 3: Choose the FD Type

YONO offers a variety of FD options tailored to different needs. Some popular ones include:

  • Regular FD: A standard option with fixed returns.
  • Tax-Saving FD: Lock your money for 5 years and enjoy tax benefits under Section 80C.
  • Senior Citizens FD: Higher interest rates for individuals aged 60 and above.

Select the one that aligns with your financial goals.

Step 4: Open Fixed Deposit

Now click on Open Fixed Deposit and Enter the Details –

  1. Enter the amount you want to deposit. (Most FDs require a minimum of ₹1,000.)
  2. Choose the tenure (in days, months, or years). The app will display the interest rate applicable based on your chosen tenure.
  3. Pick the interest payout option:
    • Cumulative: Interest is compounded and paid at maturity.
    • Non-Cumulative: Receive interest monthly, quarterly, or annually.

Step 5: Nominate a Beneficiary

Adding a nominee is optional but highly recommended. This ensures your funds go to the right person in case of any unforeseen circumstances. Simply enter the nominee’s name and relationship with you.

Step 6: Confirm and Submit

Double-check all the details you’ve entered. Once you’re satisfied, hit the Submit button. You’ll receive a one-time password (OTP) on your registered mobile number for verification. Enter the OTP to complete the process.

Step 7: Receive Confirmation

And that’s it! You’ll receive an on-screen confirmation as well as an email/SMS with all the details of your new FD. Sit back and watch your money grow!

How to open a Fixed Deposit using SBI Internet Banking?

To open an online FD in SBI via net banking, depositors should go to SBI’s official website and log into their SBI account. There, they can choose the fixed deposit option and pick the kind of deposit account. Depositors must enter the amount they intend to deposit and choose the term deposit option, such as Term Deposit Receipt (non-cumulative) or Special Term Deposit Receipt (cumulative). The bank subsequently inquires about the duration for which the depositor wishes to open the FD. Upon specifying the deposit term, they must choose the maturity instructions for the term deposit account (auto-renew principal and pay interest/pay back principal and interest) and proceed to submit the application. Depositors may also check the information prior to finalizing the application.

Things to Keep in Mind

  1. Minimum and Maximum Limits: Check the minimum and maximum deposit limits for your selected FD type.
  2. Premature Withdrawal: Some FDs allow you to withdraw funds before maturity, but penalties may apply.
  3. Auto-Renewal: Opt for auto-renewal if you want your FD to roll over automatically upon maturity.
  4. Interest Rates: Rates vary based on the tenure and FD type. Always check the latest rates on the app.

Advantages of Using YONO for FDs

If you’re still on the fence about using YONO, here’s a quick recap of its advantages:

  • User-Friendly Interface: Intuitive design makes navigation a breeze.
  • 24/7 Access: Open an FD even at midnight if you feel like it!
  • Instant Updates: Get real-time notifications about your deposits.
  • Secure Transactions: Your data is protected with advanced encryption.

Common FAQs

1. Can I open multiple FDs through the YONO app?

Yes, absolutely! You can open as many FDs as you like, provided you meet the minimum deposit requirements for each.

2. What is the minimum amount required to open an FD?

The minimum deposit amount is usually ₹1,000, but it may vary depending on the FD type.

3. Can I close my FD early?

Yes, but premature withdrawals often come with penalties. Check the terms and conditions before proceeding.

4. Is it safe to use the YONO app for financial transactions?

Yes, the app uses advanced encryption and secure login methods to protect your data and transactions.

5. What happens if I don’t choose auto-renewal?

If you opt out of auto-renewal, the maturity amount will be credited directly to your linked savings account upon completion of the FD tenure.

Opening an FD through the YONO app is as easy as ordering pizza online. So why wait? Take a few minutes today to secure your financial future. Trust us—your future self will thank you!