Blog Page 99

How to Get a Pre-Approved SBI Personal Loan on the YONO App

You can easily get a Pre-Approved SBI personal loan using the YONO App. The YONO (You Only Need One) app from the State Bank of India (SBI) has transformed banking by providing personal loans that are pre-approved and simple to obtain, process, and disburse. The era of limitless paperwork and protracted approvals is over. Curious?

Let’s explore the specifics of how you can access a pre-approved SBI personal loan via the YONO app.

pre approved personal loan yono app sbi

Why Choose an SBI Personal Loan on YONO?

Imagine needing funds urgently, whether it’s for a wedding, a medical emergency, or even a long-overdue vacation. Waiting around for traditional loan approvals just doesn’t cut it anymore, right?

That’s where SBI’s YONO app comes to your rescue –

  1. Speedy Process: Everything is digital, from application to disbursement.
  2. Pre-Approved Offers: If you’re an existing SBI customer, you might already qualify without needing additional documentation.
  3. Competitive Interest Rates: SBI’s interest rates are some of the best in the market.
  4. No Hidden Costs: Transparent terms and conditions keep you in the loop.
  5. 24/7 Accessibility: Apply for a loan anytime, anywhere!

Eligibility for Pre-Approved Loans on YONO

Before we dive into the how-to, let’s discuss eligibility. Pre-approved loans aren’t suitable for everyone; they are usually provided to SBI clients who have a solid credit history and maintain an active account.

Here are some key factors –

  • Existing Relationship with SBI: Savings or salary account holders are usually eligible.
  • Good Credit Score: Your CIBIL score plays a big role.
  • Regular Transactions: Consistent account activity increases your chances.
  • Income Stability: A stable source of income adds brownie points.

If you tick these boxes, you might already have a pre-approved offer waiting for you in the YONO app!

How To Find If I Am Eligible For SBI Pre-Approved Personal Loan?

The pre-approved personal loan is mainly accessible to current SBI bank account holders. The loan sum, interest rate, repayment period, and additional conditions are set individually for each case.

To find your eligibility, you need to send an SMS from your registered mobile number to 567676. Here is the format – 

“PAPL XXXX” – XXXX is the last 4 digits of your SBI Savings Bank Account number 

The SBI Pre-Approved Personal Loan is available through the SBI YONO app. This is a digital product focused on customers that provides immediate disbursement. It is a far more straightforward and convenient method to obtain a loan than conventional approaches. There is no need to go to any branch or provide any documents.

No paperwork or visits to branches are necessary. You can finish the whole application process from the convenience of your home with only a few clicks. The whole procedure only requires a few minutes and is entirely digital. The funds will be immediately accessible in your account after approval.

Step-by-Step Guide to Avail of a Pre-Approved Loan on YONO

Ready to grab that loan? Here’s a simple, step-by-step guide to help you through:

Step 1: Download and Log In to YONO

If you haven’t already, download the YONO app from Google Play Store or Apple App Store. Log in using your SBI net banking credentials or register as a new user. Ensure your mobile number is linked to your SBI account for seamless integration.

If you have already registered at YONO app login using MPIN or SBI net banking credentials.

Step 2: Check Your Loan Eligibility

Once logged in, navigate to the “Loans” section. Here, you’ll find various sections. Home Loan, Car Loan, Personal Loan, Gold Loan, Education Loan and Loan Against Mutual Funds. You will also get the option to apply for a personal loan.

Step 3: Review the Offer

Click on the loan offer to see all the details, including:

  • Loan amount
  • Interest rate
  • Tenure
  • Monthly EMIs (Equated Monthly Installments)

Take your time to review these terms.  

Step 4: Select the Loan Amount and Tenure

Now decide how much you need and for how long. Use the sliders provided in the app to customize the loan amount and repayment period. The EMI calculator will automatically adjust to show you the corresponding monthly payments.

Step 5: Accept the Terms and Conditions

Once you’re satisfied, click on “Proceed” and accept the terms and conditions. Make sure to read them carefully—no one likes surprises when it comes to money matters!

Step 6: Verify with OTP

You’ll receive a One-Time Password (OTP) on your registered mobile number. Enter the OTP to confirm your application.

Step 7: Disbursement

And that’s it! If all goes well, the loan amount will be credited to your account within minutes. It’s as simple as ordering a pizza online.

Note – You need to submit the necessary documents for the loan, including your PAN Card and Aaddhar Card. A Bank executive or official initiates a background check and may ask for Xerox copies of additional documents like employment history, salary slip, and moveable or immovable assets. Make sure to get these documents ready. In the case, of a business person bank may ask for income tax returns, company balance sheets , sales, and purchase records.

Pro Tips for a Smooth Loan Application

  1. Keep Your Details Updated: Ensure your mobile number, email, and account information are up-to-date in SBI’s records.
  2. Maintain a Good Credit Score: Pay your bills on time and avoid unnecessary debt.
  3. Use the EMI Calculator: Don’t overborrow; use the EMI calculator to find a repayment amount you’re comfortable with.
  4. Read the Fine Print: Always check for additional charges like processing fees.
  5. Avoid Multiple Applications: If you’re pre-approved, stick to one application to avoid complications.

Benefits of Taking a Loan Through YONO

Still on the fence? Here are some reasons why the YONO app is a game-changer:

  • Paperless Process: No documents to upload or submit physically.
  • Instant Disbursement: Funds in your account within minutes.
  • User-Friendly Interface: Even first-time users find it easy to navigate.
  • Customized Offers: The app shows you loan amounts tailored to your profile.
  • Secure Transactions: End-to-end encryption ensures your data is safe.

Common Mistakes to Avoid

  1. Ignoring Loan Terms: Skipping the fine print can cost you later.
  2. Overestimating Repayment Ability: Don’t stretch your finances too thin.
  3. Delaying Payments: Late EMIs can hurt your credit score.
  4. Not Comparing Rates: While SBI offers competitive rates, it’s worth comparing with other lenders.

Conclusion

There you go—a comprehensive guide to obtaining a pre-approved SBI personal loan through the YONO app. Thanks to its ease of use, rapid processing, and convenience, YONO simplifies the loan acquisition process. Whether you require money for an urgent situation or a personal endeavor, SBI’s pre-approved options are designed to simplify your life. So, what are you waiting for? Access the YONO app and discover what awaits you today!

FAQs

1. How do I know if I’m eligible for a pre-approved loan on YONO? SBI usually sends notifications via SMS or email to eligible customers. Alternatively, you can check the “Pre-approved Loan” section in the YONO app.

2. What’s the maximum loan amount I can get? The maximum amount varies depending on your credit profile, account history, and income. The YONO app will display your personalized limit.

3. Are there any additional charges? Yes, SBI may charge a processing fee, which will be clearly mentioned in the loan terms.

4. Can I prepay the loan? Yes, SBI allows prepayment of personal loans. However, there might be a small prepayment charge.

5. Is the YONO app secure for loan applications? Absolutely! The YONO app uses advanced encryption to ensure all your transactions and data are secure.
Why Choose ADSS? Top Features and Reviews from UAE Traders

When it comes to selecting the right broker in the competitive world of CFD trading, ADSS stands out as a prominent name in the UAE and across the GCC region. Known for its regulatory credibility and advanced trading solutions, ADSS has built a strong reputation among traders seeking reliability and cutting-edge tools. This review will highlight the top features that make ADSS a preferred choice for traders and provide insights based on feedback from the UAE trading community.

UAE Traders

Regulatory Excellence: A Foundation of Trust

One of the biggest draws of ADSS is its regulatory compliance. The broker is licensed and regulated by the Securities and Commodities Authority (SCA) in the UAE, a respected regulatory body ensuring high standards of security, transparency, and accountability.

This regulation sets ADSS apart from offshore brokers, offering peace of mind to traders by safeguarding their funds and ensuring fair trading practices. UAE traders particularly value this regulatory backing, which reinforces trust and confidence in the platform.

Diverse CFD Offerings Across Asset Classes

ADSS specializes in Contracts for Difference (CFDs), providing traders with the ability to speculate on a variety of financial instruments without owning the underlying assets. The broker’s range of CFD offerings includes:

  • Forex: Access to major, minor, and exotic currency pairs for dynamic trading opportunities.
  • Equities: Speculate on global stocks and ETFs across multiple industries and regions.
  • Commodities: Trade popular commodities like crude oil, gold, and natural gas.
  • Indices: Gain exposure to global indices, including the S&P 500 and FTSE 100.
  • Cryptocurrencies: Stay ahead in the market with CFDs on leading digital assets like Bitcoin and Ethereum.

This diversity appeals to traders looking to build versatile portfolios, allowing them to capitalize on opportunities in multiple markets.

User-Friendly Trading Platforms

The proprietary ADSS platform has been tailored for ease of use and functionality, making it suitable for both beginners and experienced traders. With real-time data, advanced charting tools, and seamless execution, it’s a reliable solution for those seeking a modern trading experience.

The mobile version of the platform ensures traders can stay connected to the markets from anywhere, offering flexibility without sacrificing features.

MetaTrader 4 (MT4)

For traders who prefer a traditional trading interface, ADSS also supports MetaTrader 4 (MT4). This platform is globally renowned for its robust analytical tools, custom indicators, and algorithmic trading capabilities. Experienced traders often gravitate toward MT4 for its ability to support automated trading strategies and detailed market analysis.

Both platforms reflect ADSS’s commitment to meeting the varied preferences of its clients, ensuring a tailored experience for every trader.

Account Options Designed for UAE Traders

ADSS offers three primary account types, catering to the needs of different trading styles and expertise levels:

  • Classic Account: Ideal for beginners, offering competitive spreads and a straightforward trading experience.
  • Elite Account: Suited for intermediate traders, this account features tighter spreads and enhanced benefits, including dedicated account management.
  • Pro Account: Designed for high-volume traders, providing premium perks, the tightest spreads, and personalized support.

The variety of account types ensures that traders can find an option that matches their experience level and trading objectives.

Key Features Highlighted by UAE Traders

As a UAE-based broker, ADSS offers multilingual customer support tailored to the needs of the region. Traders can rely on prompt assistance for account setup, platform navigation, and technical issues, making it an attractive option for those new to CFD trading.

ADSS provides a wealth of educational tools, including webinars, market insights, and trading guides. These resources are designed to empower traders with knowledge about market trends, technical analysis, and trading strategies, helping them improve their skills and confidence.

Many UAE traders commend ADSS for its competitive spreads, which directly impact profitability. The ability to access tight spreads across various asset classes is a significant advantage for those focused on cost efficiency.

How Does ADSS Compare to Competitors?

ADSS distinguishes itself from competitors through its regional expertise, robust regulation, and emphasis on CFD trading. While some brokers may offer direct investment options or additional asset classes, ADSS’s focus on CFDs provides specialized tools and resources for active traders.

Its proprietary platform offers a modern, localized alternative to global options like MT4, making it a strong choice for those seeking a broker with both global reach and regional insight.

Final Thoughts on ADSS

For traders in the UAE and GCC region, ADSS offers a compelling combination of regulatory credibility, advanced trading platforms, and diverse CFD offerings. Whether you’re a novice looking for educational resources or an experienced trader seeking tight spreads and personalized support, ADSS has something to offer.

Its focus on Contracts for Difference ensures flexibility and accessibility, catering to traders who want to capitalize on global markets without the complexities of asset ownership.

If you’re considering a reliable and user-friendly broker for your trading journey, ADSS is worth exploring. To learn more, check out this comprehensive ADSS trading guide for further insights into their features and services.

Digital Currency – Features Pros & Cons, and Future Uses

Digital currency is sweeping across the globe. From Bitcoin to CBDCs (Central Bank Digital Currencies), these forms of currency are transforming our perception of money. The world is moving towards digital currency. Even India has developed CDBC – Digital Rupee or E-Rupee.

However, US President Donald Trump has issued a new executive order (EO) aimed at strengthening the country’s leadership in digital financial technology. The order prohibits the creation and issuance of central bank digital currency (CBDC), while also directing the establishment of a federal regulatory framework for digital assets such as cryptocurrencies and stablecoins.

But what exactly is digital currency? Why do they matter, and where are they headed? Let’s explore key features, advantages, disadvantages, and potential future applications of digital currency.

Digital Currency

What is Digital Currency?

At its essence, digital currency refers to any type of currency that exists solely in digital or electronic format. Currencies that are only accessible with computers or mobile phones. In contrast to physical money—the cash and coins you carry—digital currencies lack any tangible form. They exist solely in digital form and can be utilized for online purchases or, with the appropriate technology, in certain brick-and-mortar shops.

Digital currencies rely on technology for their creation, storage, and transfer. They’re often built on blockchain or distributed ledger technology, but not always. Think of them as the evolution of money—tailored for our increasingly digital world.

Types of Digital Currencies

Digital currencies aren’t one-size-fits-all. They come in various forms, each with unique characteristics and purposes. Here’s a quick breakdown:

1. Cryptocurrencies

These are decentralized digital currencies that operate on blockchain technology. Cryptocurrencies like Bitcoin, Ethereum, and Litecoin are the pioneers of this space.

  • Decentralized: No single entity controls them.
  • Secure: Transactions are verified using cryptography.
  • Borderless: They can be sent anywhere in the world without intermediaries.

2. Stablecoins

Stablecoins are digital currencies pegged to a stable asset like the US dollar or gold. Examples include Tether (USDT) and USD Coin (USDC). Their value doesn’t fluctuate as wildly as cryptocurrencies.

  • Stability: Designed to minimize price volatility.
  • Practicality: Useful for everyday transactions.

3. Central Bank Digital Currencies (CBDCs)

These are digital currencies issued and regulated by central banks. Unlike cryptocurrencies, CBDCs are centralized and backed by the government. Examples include China’s digital yuan and the pilot programs for digital euro.

  • Government-backed: They’re official legal tender.
  • Highly regulated: Controlled by a central authority.

4. Utility Tokens

Utility tokens are a type of digital currency that grants access to a product or service. For example, Filecoin allows users to pay for decentralized storage services.

  • Purpose-driven: Designed for specific applications.
  • Non-monetary: Not typically used as a medium of exchange.

5. Digital Fiat Currencies

This refers to traditional fiat money in digital form. For instance, your online bank balance represents digital fiat currency. Though not blockchain-based, it’s still a form of digital money.

Features of Digital Currency

Digital currencies boast several defining traits that set them apart from traditional money. Here are some key characteristics:

  1. Digital-Only: No physical form—it exists purely in electronic formats.
  2. Global Accessibility: Accessible from anywhere with an internet connection.
  3. Programmability: Can include smart contracts to automate transactions or enforce conditions.
  4. Decentralized vs. Centralized: Some digital currencies are decentralized (cryptocurrencies), while others are centralized (CBDCs).
  5. Transparency: Many digital currencies offer transparent transaction histories, thanks to blockchain technology.
  6. Anonymity or Pseudonymity: Users can transact without revealing their identities fully, depending on the currency.

Pros of Digital Currencies

Why are digital currencies so popular? Here are the advantages:

1. Speedy Transactions

Gone are the days of waiting for days for a bank transfer to clear. Digital currencies enable near-instant transactions.

2. Lower Costs

With no need for intermediaries like banks, transaction fees are significantly reduced. That’s especially useful for cross-border payments.

3. Global Reach

Digital currencies know no borders. Whether you’re in New York or Nairobi, you can send and receive money seamlessly.

4. Financial Inclusion

For the unbanked and underbanked populations, digital currencies offer access to financial services without needing a traditional bank account.

5. Security and Transparency

Blockchain technology ensures secure transactions, making fraud nearly impossible. Plus, transaction histories are often publicly accessible, ensuring transparency.

Cons of Digital Currencies

It’s not all sunshine and rainbows, though. Digital currencies have their drawbacks:

1. Volatility

Cryptocurrencies, in particular, are infamous for their price swings. What’s worth $50,000 today could plummet to $30,000 tomorrow.

2. Regulatory Uncertainty

Governments are still figuring out how to regulate digital currencies, leading to an uncertain legal environment.

3. Energy Consumption

Some digital currencies, like Bitcoin, consume massive amounts of energy for mining. That’s a significant environmental concern.

4. Potential for Illicit Use

The anonymity of digital currencies makes them appealing for illegal activities, though law enforcement is getting better at tracking such transactions.

5. Technological Barriers

Not everyone is tech-savvy. Understanding and using digital currencies can be daunting for some people.

Future Uses of Digital Currency

What does the future hold for digital currencies? Here are some promising possibilities:

1. Global Financial Systems

CBDCs could revolutionize global banking, making transactions faster and more efficient while reducing costs for cross-border payments.

2. Decentralized Finance (DeFi)

DeFi platforms built on blockchain could eliminate the need for traditional banks, offering decentralized loans, insurance, and savings accounts.

3. Tokenized Assets

Imagine owning a fraction of a Picasso painting or real estate property. Digital currencies can tokenize assets, making investment opportunities more accessible.

4. Smart Contracts

Smart contracts could automate everything from insurance payouts to rental agreements, making transactions smoother and more reliable.

5. Universal Basic Income (UBI)

Governments could use digital currencies to distribute UBI efficiently, ensuring everyone receives their share promptly and transparently.

Conclusion

Digital currencies are more than a temporary fad; they represent a major advancement in the development of money. Due to their various forms, distinct features, and numerous advantages, it’s evident why they are becoming increasingly popular. Absolutely, there are obstacles to address—such as fluctuations and regulations—but the possibilities are vast. Digital currencies have become a permanent fixture, revolutionizing financial systems and facilitating new business models. Whether you’re an investor, a technology lover, or simply curious, this is the perfect moment to jump in and discover this thrilling realm.

FAQs

Q1: Are digital currencies safe to use? Yes, but it depends on the type. Cryptocurrencies are secure due to blockchain technology, but you need to watch out for scams and use trusted platforms.

Q2: How do I get started with digital currencies? Start by researching, choosing a reliable platform, and setting up a digital wallet. Buy a small amount to get familiar before diving deeper.

Q3: What’s the difference between digital currency and cryptocurrency? All cryptocurrencies are digital currencies, but not all digital currencies are cryptocurrencies. Digital currencies include CBDCs, stablecoins, and more, while cryptocurrencies are decentralized and blockchain-based.

Q4: Can digital currencies replace traditional money? Not entirely—at least not yet. They complement traditional money but face challenges like adoption, regulation, and infrastructure development.

Q5: What are some popular digital currencies? Bitcoin, Ethereum, Tether, and the digital yuan are some well-known examples. Each serves different purposes and audiences.

Forex Card Vs Credit Card – Which one will help with Currency Changes?

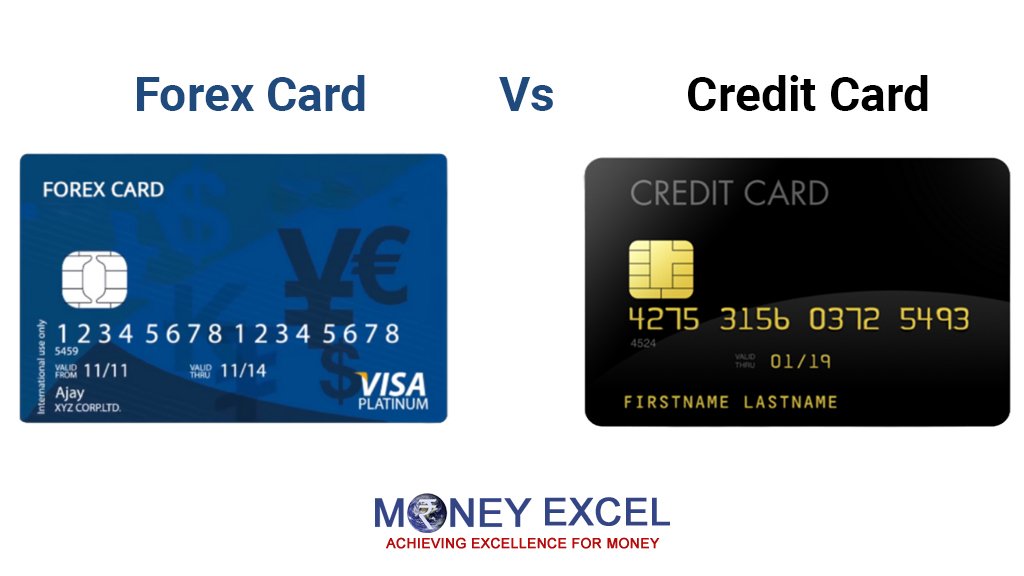
Forex Card vs Credit Card – When organizing an international journey, there are countless aspects to consider: flights, lodging, attractions, and definitely, finances. Currency exchange plays an essential role in your travel preparations, and you might have wondered: Is it better to use a Forex card or remain with a reliable credit card? Indeed, you’re not the only one—this is a frequent problem for travelers. Let’s analyze it and determine which option is better for your budget and your wallet.

Forex Card vs Credit Card

What’s a Forex Card?

Before we explore the advantages and disadvantages, let’s clarify what a forex card is. In simple terms, it’s a prepaid card filled with foreign money. You can add funds in the currency of your travel destination, and use it like a debit or credit card to buy items or take out cash from ATMs overseas. Consider it as a travel companion that effortlessly manages your currency requirements abroad.

What’s a Credit Card?

At this point, credit cards require no introduction. They’re your preferred choice for shopping, settling bills, and even gaining rewards. Although you can use them overseas, they have their own fees and peculiarities when utilized for currency exchanges. In contrast to forex cards, credit cards impose a foreign transaction fee for each purchase you conduct in a different currency. What about the conversion rates? They don’t always work out for you.

So, which one’s the better pick for currency changes? Let’s checkout.

Forex Card vs Credit Card – What’s Cheaper?

When it comes to spending money abroad, cost plays a big role. Here’s how forex cards and credit cards stack up:

Forex Cards

  1. Fixed Exchange Rates: When you load a forex card, you lock in the exchange rate. This means no surprises if the currency fluctuates while you’re abroad. For example, if you load 1,000 euros at a specific rate today, that’s the rate you’ll stick with.
  2. No Foreign Transaction Fees: Unlike credit cards, forex cards don’t slap on a 2-3% fee for every international transaction. That’s a win for your budget!
  3. ATM Withdrawal Costs: While forex cards do allow ATM withdrawals, they often come with a small fee. It’s usually much lower than what you’d pay with a credit card.

Credit Cards

  1. Dynamic Exchange Rates: Credit cards use the exchange rate on the day of the transaction, which can be a double-edged sword. If the currency strengthens against your home currency, you’ll pay more than expected.
  2. Foreign Transaction Fees: These fees can add up quickly. On a $1,000 spend, a 3% fee equals $30. Over the course of a trip, this can be a significant extra expense.
  3. ATM Withdrawals Are a No-No: Using a credit card to withdraw cash abroad can be a costly mistake. High withdrawal fees and interest rates kick in immediately, making this option a last resort.

Forex Card vs Credit Card – What’s Easier to Use?

Traveling can be stressful, so convenience matters. Here’s how these cards compare:

Forex Cards

  • Widely Accepted: Forex cards are accepted at most international retailers, restaurants, and ATMs. Just make sure the card network (Visa, MasterCard, etc.) aligns with where you’re traveling.
  • Reload Options: If you run out of funds, you can reload your forex card online. It’s a quick and easy process.
  • Multi-Currency: Planning a multi-country trip? Some forex cards support multiple currencies on one card, so you won’t have to juggle different cards.

Credit Cards

  • Universal Usage: Credit cards are accepted almost everywhere, making them super convenient for spontaneous purchases.
  • No Reload Needed: Your spending limit depends on your credit limit, so you don’t have to worry about reloading funds.
  • Emergency Backup: If you face unexpected expenses, your credit card can be a lifesaver. Plus, many credit cards offer emergency assistance services.

Forex Card vs Credit Card – Which One’s Safer?

Nobody wants to deal with fraud or theft, especially while traveling. Let’s talk security:

Forex Cards

  • PIN Protection: Forex cards are PIN-enabled, adding a layer of security.
  • Limited Loss: If your forex card is lost or stolen, the damage is limited to the loaded amount. You can block the card instantly to prevent unauthorized use.
  • Not Linked to Your Bank Account: This makes forex cards a safer choice in case of theft, as your main bank account remains untouched.

Credit Cards

  • Fraud Protection: Most credit cards come with zero-liability protection, so you won’t be held accountable for unauthorized charges.
  • Instant Blocking: You can block your card with a quick phone call or app notification if it’s lost or stolen.
  • Linked to Your Credit: If fraud occurs, it could temporarily affect your credit limit until the issue is resolved.

Rewards and Benefits: Any Extras?

Who doesn’t love perks? Here’s how forex and credit cards compare when it comes to extras:

Forex Cards

  • Minimal Perks: Forex cards are pretty no-frills. Their main appeal is cost-effectiveness, not rewards.
  • Occasional Offers: Some forex cards come with limited-time discounts on travel bookings or shopping.

Credit Cards

  • Rewards Galore: From cashback to air miles, credit cards often offer attractive rewards for spending.
  • Travel Insurance: Many premium credit cards include travel insurance, which can be a handy backup if your trip goes sideways.
  • Lounge Access: If you’re flying, credit cards with lounge access can add a touch of luxury to your journey.

Scenarios: Which One Should You Use?

Still undecided? Here’s a cheat sheet for common travel scenarios:

  1. Short Trips: A forex card is ideal for short vacations since you can pre-load a specific amount and avoid overspending.
  2. Long-Term Travel: If you’re planning a long trip or studying abroad, a forex card’s locked-in rates can save you money in the long run. Pair it with a credit card for emergencies.
  3. Frequent Flyer: Credit cards that offer air miles and travel perks are a better choice if you travel often and want to rack up rewards.
  4. Multi-Destination Trips: Forex cards supporting multiple currencies are your best bet for hassle-free travel across several countries.

Final Thoughts

So, what’s the verdict? The choice between a forex card and a credit card depends on your travel habits, budget, and needs. Forex cards are perfect for cost-conscious travelers who want to avoid hefty fees and lock in exchange rates. On the other hand, credit cards offer unmatched convenience, rewards, and emergency support.

If you’re still unsure, why not take both? Use a forex card for everyday expenses and a credit card as a backup. This way, you get the best of both worlds and can focus on enjoying your trip instead of worrying about currency changes.

FAQs

1. Can I use a forex card for online transactions in a foreign currency? Yes, forex cards can be used for online payments in the currency loaded on the card. Just ensure the website accepts the card’s network (e.g., Visa or MasterCard).

2. What happens if I have leftover money on my forex card? You can either withdraw the remaining amount in your home country (fees may apply) or request a refund from the issuing bank.

3. Are there any hidden fees with forex cards? Forex cards typically have transparent fee structures, but watch out for inactivity fees, ATM withdrawal charges, or fees for reloading funds.

4. Do all credit cards charge foreign transaction fees? No, some credit cards offer zero foreign transaction fees. Check with your card issuer to confirm.

5. Which is safer to carry—a forex card or a credit card? Both are safe if used responsibly. Forex cards limit your exposure to theft, while credit cards offer robust fraud protection. It’s wise to carry both for added security.