Blog Page 53

How to Request a Refund Reissue for Your Income Tax Refund

0

Getting a tax refund can feel like a nice bonus after filing your income tax return (ITR). It’s the money the government owes you back if you’ve paid more taxes than you needed to. But sometimes, things don’t go as planned. Your refund might not land in your bank account even after weeks of waiting. That’s when you might need to ask for a refund reissue. This happens if the first attempt to send the refund fails for some reason.

In this guide, I’ll walk you through everything you need to know about requesting a refund reissue. We’ll cover why refunds fail, how to fix common problems, and step-by-step instructions on how to make the request online. I’ll also add some real-life examples to make it clearer. Think of this as your go-to resource if you’re dealing with a delayed or failed refund from the Income Tax Department in India. Normally, refunds take about 4 to 5 weeks to show up in your account after your ITR is processed. If it’s been longer, check your email or the tax portal for any messages from the department or the refund banker, like the State Bank of India (SBI). They might tell you the refund bounced back.

Let’s start with the basics. What exactly is an income tax refund? When you file your ITR, you calculate how much tax you owe based on your income, deductions, and exemptions. If you’ve paid extra through TDS (Tax Deducted at Source), advance tax, or self-assessment tax, the excess comes back as a refund. For the financial year 2024-25 (assessment year 2025-26), millions of people in India file ITRs, and many get refunds. But issues like bank details mismatches can stop the money from reaching you.

Imagine you’re a salaried employee in Mumbai. Your company deducts TDS from your salary every month. At the end of the year, you claim deductions for things like house rent allowance (HRA) or investments under Section 80C. If your total tax paid is Rs. 50,000 more than what you owe, you should get that back. But if your bank account isn’t set up right on the tax portal, the refund won’t go through. That’s where reissue comes in. You can request it easily online through the e-filing portal. No need to visit any office or send papers by post. It’s all digital now, thanks to the government’s push for online services.

Over the years, the Income Tax Department has made things simpler. Back in the early 2000s, refunds came by cheque in the mail, which could take months and often got lost. Now, it’s direct bank transfer, but that means your bank details must be spot on. If not, you’ll get an email saying the refund failed, and you can re-request it. This process is free, and you don’t lose any interest on the refund amount. The department adds interest at 0.5% per month if the delay is on their side, as per Section 244A of the Income Tax Act.

Income Tax Refund Reissue

Why Does an Income Tax Refund Fail?

Refunds don’t always fail, but when they do, it’s usually because of small errors that are easy to fix. Let’s look at the common reasons in detail. Understanding these can help you avoid problems in the first place.

First, your bank account might not be pre-validated. From assessment year 2022-23, it’s mandatory to validate your bank account on the e-filing portal before you can get a refund. Pre-validation means the department checks if the account is active and linked to your PAN (Permanent Account Number). Without this, the refund can’t be processed. For example, suppose you switched jobs and opened a new salary account but forgot to update it on the portal. The old account might be dormant, leading to failure.

Second, there’s a mismatch between your name on the bank account and your PAN card. Banks are strict about KYC (Know Your Customer) rules. If your PAN says “Raj Kumar Singh” but your bank account has “Raj K Singh” because you used a shortened name, it won’t match. This is common with middle names or initials. Take Mrs. Priya Sharma’s case. Her PAN has her maiden name, but after marriage, her bank account uses her married name. She didn’t update her PAN, so the refund failed. To fix this, update your PAN details or ensure the bank name matches exactly.

Third, an invalid IFSC (Indian Financial System Code) code can cause issues. Banks merge or change branches, updating IFSC codes. If you have an old code, like from a bank that merged with another, the transfer bounces. For instance, if you had an account with Vijaya Bank, which merged with Bank of Baroda in 2019, your old IFSC won’t work anymore. Always check the latest IFSC on your bank’s website or app.

Fourth, the account you mentioned might be closed. Maybe you closed an old savings account after opening a new one, but the tax portal still has the old details. This happens a lot with students or young professionals who move cities and switch banks. If the department tries to deposit into a closed account, it fails automatically.

Fifth, your PAN isn’t linked to Aadhaar, or the bank account isn’t linked to PAN. The government made Aadhaar-PAN linking mandatory in 2017 to prevent fraud. If not linked, refunds can’t be issued. Also, ensure your bank has your PAN on record. Without it, the transaction gets rejected.

Other rare reasons include technical glitches on the bank’s side or if the refund amount is very small (under Rs. 100), but those are less common. In 2023, the Income Tax Department reported that about 10-15% of refunds fail initially due to these issues. But most get resolved with a reissue request.

To prevent failures, double-check your details when filing ITR. Use Form 26AS (your tax credit statement) to see if everything matches. If you’re unsure, consult a chartered accountant or use online tools like ClearTax to file accurately.

How to Pre-Validate Your Bank Account: A Step-by-Step Guide

Pre-validation is like a security check for your bank account. It ensures the department can safely transfer money to you. Here’s how to do it in detail. This step is crucial before requesting a reissue, as only validated accounts show up for refunds.

Start by logging into the Income Tax e-filing portal at www.incometax.gov.in. Use your PAN as the user ID and your password. If you forgot the password, click “Forgot Password” and reset it using Aadhaar OTP or other methods. Once logged in, you’ll see the dashboard. It’s the main page with options like “File ITR,” “View Returns,” and more.

From the dashboard, click on “Profile” in the top menu, then select “My Bank Account.” This page lists all bank accounts you’ve added. If none are there, click “Add Bank Account.” Enter details like account number, IFSC code, bank name, and account type (savings or current). Make sure the name matches your PAN exactly.

After adding, click “Validate.” The portal will send a request to your bank via NPCI (National Payments Corporation of India) for verification. This might take a few minutes to a day. You’ll get an email or SMS when it’s done. If successful, you’ll see a green tick next to the account with “Validated” written.

What if validation fails? Common reasons: Wrong account number, inactive account, or name mismatch. Fix the error and try again. For example, Mr. Amit Patel tried validating but failed because his account was joint with his wife. He had to add a sole account instead.

You can add multiple accounts, but choose one as primary for refunds. From AY 2023-24, e-verification using net banking is also an option for validation. This makes it faster. Always validate before the refund season (usually July to December) to avoid delays.

If you’re new to this, practice on a demo account or watch YouTube tutorials. It’s straightforward, but taking time here saves headaches later.

Step-by-Step: How to Make a Refund Reissue Request Online

Now, let’s get to the main part—requesting the reissue. This is simple if your bank is validated. Follow these steps carefully.

Step 1: Log in to the portal. Go to incometax.gov.in and enter your PAN and password. If you’re using Aadhaar, link it first for seamless login.

Step 2: Navigate to the request section. After login, click on “Services” in the top menu. Scroll down to “Refund Reissue.” It might be under “Other Services” in some versions. Select the assessment year (AY) for the failed refund. AY is the year after the financial year, like FY 2024-25 is AY 2025-26.

Step 3: View pending refunds. The page will show a list of refunds that failed for different AYs. Each one has details like amount, date of failure, and reason (if mentioned). Click the “Refund Re-issue” button on the relevant card.

Step 4: Create the request. Click “Create New Request.” You’ll see a form. Select the validated bank account from the dropdown. Only pre-validated ones appear here. If none show, go back to the profile section and validate one.

Step 5: Submit and verify. Review the details—amount, AY, bank info. Click “Submit.” You’ll get an OTP on your registered mobile or email for verification. Enter it to confirm.

A success message pops up, like “Your refund reissue request has been submitted successfully. Reference number: XXXXX.” Note this number for tracking.

Let’s look at an example. Suppose Ms. Neha Gupta filed ITR for AY 2024-25 and expected Rs. 20,000 refund. It failed due to wrong IFSC. She logs in, goes to Services > Refund Reissue, selects AY 2024-25, picks her validated HDFC account, submits, and gets confirmation. Within 2-3 weeks, the money is in her account.

Common mistakes: Choosing the wrong AY or not validating the bank first. If you have multiple failed refunds, request them one by one. No fee, and you can do it anytime, but sooner is better to get your money fast.

If you’re facing issues like portal downtime (rare but happens during peak times), try late at night or early morning. Also, keep your browser updated—Chrome or Firefox works best.

How to Check the Status of Your Refund Reissue Request

After submitting, you want to know what’s happening. Checking status is easy and helps you follow up if needed.

Step 1: Log in to the portal again.

Step 2: Go to “My Account” > “Service Request.” Select “Request Type” as “View Request” and “Request Category” as “Refund Reissue.”

Step 3: Click “Submit.” You’ll see a list of your requests with status like “Pending,” “Processed,” or “Rejected.” If processed, the refund should be on its way.

For example, if it’s pending for over a month, contact the helpline at 1800-103-0025 or email them. Status updates usually come via email too.

You can also check overall refund status under “My Account” > “Refund/Demand Status.” Enter PAN and AY to see if it’s issued.

Additional Tips for Smooth Refund Processing

To make sure your refunds don’t fail in the future, here are some extra tips. Always file ITR on time—by July 31 for non-audit cases. Late filing means no interest on refund. Use accurate forms: ITR-1 for simple salaries, ITR-2 for capital gains, etc.

Claim all deductions. For instance, under Section 80D, you can deduct up to Rs. 25,000 for health insurance. Keep records like Form 16 from employer.

If you’re a senior citizen, opt for the old tax regime if it benefits you more. And remember, refunds over Rs. 2 lakhs might trigger scrutiny, so be honest.

In case of large refunds, the department might ask for more docs. Respond quickly via the portal.

Frequently Asked Questions

What happens if I don’t verify my ITR within 30 days?

Your return is treated as not filed. You’ll face penalties under Section 234F—Rs. 5,000 for late filing—and might lose deductions. For example, if you uploaded ITR on July 1 but forgot to verify, it’s invalid after July 31. Verify using Aadhaar OTP, e-sign, or by sending physical ITR-V to CPC Bangalore.

How long does a reissued refund take?

Usually 2-4 weeks after request, but it can vary. If it’s delayed, check status or call helpline.

Can I request reissue for old AYs?

Yes, up to 7 years back, but check if the refund is still valid. Old refunds might be adjusted against demands.

What if my bank account is with a foreign bank?

For NRIs, use an Indian bank account. Foreign accounts need special approval.

Is there a limit on refund amount for reissue?

No, but large amounts (> Rs. 50 lakhs) go through RTGS, smaller via NEFT.

My refund failed due to Aadhaar not linked. What now?

Link Aadhaar to PAN on the portal, then re-validate bank and request reissue.

Can I change bank account after failure?

Yes, add and validate a new one, then select it in the reissue request.

What if I get a defective return notice?

Fix it within 15 days, or your ITR is invalid, and refund stops.

How do I know if refund is credited?

Check bank statement or get SMS from bank. Also, portal shows “Refund Issued.”

If refund is less than expected?

It might be adjusted for old dues. Check intimation under Section 143(1).

These FAQs cover common doubts. If yours isn’t here, search the portal’s help section or consult a tax expert.

In conclusion, requesting a refund reissue is straightforward if you follow the steps. With digital tools, it’s faster than ever. Stay updated on tax rules, and you’ll handle refunds like a pro. If you need help filing ITR, platforms like ClearTax offer guided services. Remember, taxes are part of life—handle them wisely!

Salary Hike Calculator Guide to Smarter Pay Negotiations

0

If there’s one thing that gets every working professional’s heart racing, it’s the phrase “salary hike.” Whether you’re waiting for your annual appraisal, planning a job switch, or simply curious about what a fair raise looks like, the big question always pops up: “How much of a hike should I expect?”

That’s exactly where a Salary Hike Calculator for India comes in handy. It takes the guesswork out of pay hikes, giving you a clear idea of what your new salary could look like after increments. From freshers dreaming about their first big raise to seasoned professionals negotiating at the table, this tool is becoming a go-to resource.

In this article, we’ll break down everything you need to know about salary hike calculators, why they matter in India’s evolving job market, and how you can use one to take control of your career.

Salary Hike Calculator

What is a Salary Hike Calculator?

A Salary Hike Calculator is a simple tool that helps you figure out your revised salary after an increment. All you do is enter your current salary and the percentage hike offered, and voilà — you instantly get your new package details.

Think of it as your personal appraisal buddy that tells you:

  • Your updated monthly salary
  • Your new annual package (CTC)
  • The exact amount of your increment

No more pulling out calculators, scribbling numbers on paper, or stressing over “percentage math.” It’s fast, accurate, and convenient.

Why Do You Need a Salary Hike Calculator?

In India’s dynamic job market, pay hikes aren’t just about numbers; they reflect your growth, skill value, and market demand. But figuring out hikes can be tricky. Here’s why using a calculator makes sense:

  • Saves time: No manual calculations or second-guessing.
  • Clear comparisons: Helps compare offers between companies.
  • Negotiation power: Walk into salary discussions with confidence.
  • Financial planning: Know exactly how much extra you’ll take home.
  • Transparency: Understand the difference between gross pay, CTC, and in-hand.

When employers throw around terms like “15% hike” or “CTC structure”, a calculator translates that jargon into real numbers you can relate to.

How Does a Salary Hike Calculator Work?

The logic behind it is surprisingly simple, though most people hate doing the math. Let’s break it down.

Formula:

New Salary = Current Salary + (Current Salary × Hike % / 100)

For example:

  • Current Salary: ₹50,000 per month
  • Hike: 20%

New Salary = 50,000 + (50,000 × 20 / 100) 

New Salary = 50,000 + 10,000 = ₹60,000 per month

Your annual package instantly jumps from ₹6,00,000 to ₹7,20,000. Not bad, right?

A Salary Hike Calculator for India automates this math, giving you instant results without errors.

Common Scenarios Where a Salary Hike Calculator Helps

Here’s where you’ll find this tool incredibly useful:

  1. Annual Appraisals

Wondering if that 7% hike is worth celebrating? Plug in the numbers and see your real growth.

  1. Job Switches

Got an offer letter in hand? Compare it with your current CTC and check the real hike percentage.

  1. Promotions

A promotion often means a bigger hike. Use the calculator to set realistic expectations.

  1. Salary Negotiations

When HR asks, “What hike are you looking for?”, you’ll know the exact figure instead of guessing.

  1. Financial Planning

Your future goals — buying a car, saving for a house, or even a vacation — depend on accurate income projections.

Factors That Influence Salary Hikes in India

Not all hikes are created equal. Several factors determine how much of a raise you’ll get:

  • Industry growth: IT, fintech, and e-commerce often give higher hikes.
  • Company performance: Strong profits usually mean better increments.
  • Skill demand: Hot skills like AI, data science, and cybersecurity fetch bigger raises.
  • Experience level: Entry-level hikes may be modest, while mid-senior professionals often get double-digit increments.
  • Location: Metro cities like Bengaluru, Mumbai, and Delhi generally offer higher packages.
  • Performance reviews: Your past year’s work is often the biggest deciding factor.

Knowing these factors helps you set realistic expectations before you even use a calculator.

Average Salary Hikes in India (2025 Outlook)

According to reports, average increments in India are expected to hover around 9–10% in 2025. But this number varies widely:

  • Top performers: 15–20% hikes
  • Average performers: 7–10% hikes
  • Job switchers: 25–35% hikes (sometimes even higher in niche skills)

With a Salary Hike Calculator for India, you can instantly check where you stand against these benchmarks.

Step-by-Step: How to Use a Salary Hike Calculator

Using a calculator is straightforward, but let’s lay it out step by step:

  1. Enter your current salary (monthly or yearly).
  2. Enter the hike percentage (say, 10%, 20%).
  3. Hit calculate.
  4. Instantly see:
    • Revised monthly salary
    • Revised annual salary
    • Increment amount

That’s it — quick, clean, and hassle-free.

Salary Hike Calculator for India: Practical Examples

Let’s look at a few real-world scenarios:

Example 1:

  • Current Salary: ₹30,000/month
  • Hike: 12%

New Salary = ₹30,000 + (30,000 × 12/100) = ₹33,600

Example 2:

  • Current Salary: ₹15,00,000/year
  • Hike: 18%

New Salary = ₹17,70,000/year

Example 3: Job Switch Scenario

  • Current CTC: ₹8,00,000
  • New Offer: ₹10,40,000

Hike % = (New – Old) ÷ Old × 100
= (10,40,000 – 8,00,000) ÷ 8,00,000 × 100 = 30%

This way, you can calculate both forward (expected hike) and backward (percentage hike from offers).

Advantages of Using a Salary Hike Calculator

Still wondering if you should try it? Here’s what makes it a must-use tool:

  • Accuracy: Zero chance of human error.
  • Speed: Instant results.
  • Clarity: Breaks down hike amounts in plain numbers.
  • Versatility: Works for monthly or annual salaries.
  • Confidence: Helps in career discussions.

In short, it’s your career cheat sheet during appraisal season.

Limitations of Salary Hike Calculators

Of course, no tool is perfect. A salary hike calculator has its limits:

  • Doesn’t account for tax changes.
  • Ignores bonuses, perks, and allowances.
  • Assumes the hike applies to your full salary (which may not always be true).
  • Can’t predict company-specific policies.

So, while it’s super useful, take the results as a guide — not gospel truth.

Tips to Maximize Your Salary Hike in India

Knowing your numbers is great, but how can you actually push for a bigger raise?

  1. Upskill regularly: Learn trending tools, technologies, or certifications.
  2. Track your achievements: Maintain a record of your contributions.
  3. Do market research: Compare salaries in your industry.
  4. Be flexible: Sometimes perks or bonuses compensate for a lower hike.
  5. Negotiate smartly: Use the Salary Hike Calculator to quote realistic figures.
  6. Switch strategically: Job changes often bring the highest increments.

FAQs 

Q1. Is a Salary Hike Calculator accurate?
Yes, it’s accurate for basic increment math, but it won’t account for tax or variable pay.

Q2. Can I calculate hikes for job switches?
Absolutely! Just compare your old CTC with the new offer.

Q3. Does it show take-home salary changes?
Not always. Most calculators only show gross or CTC figures.

Q4. How much hike should I expect in 2025?
On average, 9–10%. But it depends on performance, skills, and industry.

Q5. Is it useful for freshers?
Yes! Even freshers can check how a 10–20% hike changes their starting pay.

Conclusion

A Salary Hike Calculator for India isn’t just about crunching numbers — it’s about clarity, confidence, and control over your career journey. In a country where pay hikes vary widely across industries and roles, this tool ensures you’re never in the dark.

Whether you’re gearing up for an appraisal, weighing a job offer, or just planning your financial future, knowing the exact impact of a salary hike can be a game-changer.

So, the next time someone throws a “10% hike” your way, don’t just nod. Fire up the calculator, crunch the numbers, and see how much your paycheck will actually grow. After all, your career deserves more than guesswork — it deserves precision!

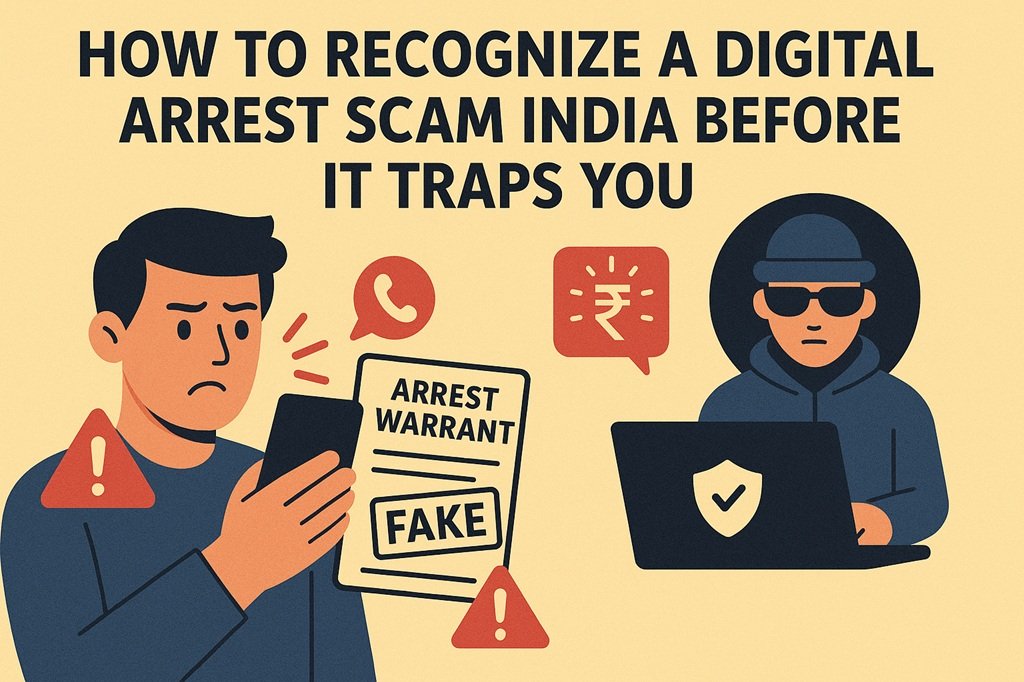
How to Spot a Digital Arrest Scam Before It Traps You

Hey there, have you ever gotten a call that made your heart race, claiming you’re in big trouble with the law? Well, imagine this: You’re sipping your morning coffee when your phone buzzes. On the other end, a stern voice says you’re under “digital arrest” for some shady crime you know nothing about. Sounds like a plot from a thriller movie, right? But nope, it’s a real scam hitting folks left and right, especially in places like India where tech-savvy crooks are getting bolder. This article dives deep into how to recognize a Digital Arrest scam, breaking it down so you can spot these digital bandits from a mile away. We’ll chat about what they are, how they pull off their tricks, and arm you with tips to stay safe. By the end, you’ll feel like a pro at dodging these cyber traps – no cape required!

Running rampant in our connected world, these scams prey on fear and urgency. Scammers, often hiding behind fake uniforms and badges on video calls, convince innocent people they’re about to be “arrested” digitally. That means no real cuffs, but plenty of pressure to cough up cash to make it go away. Yikes! With reports showing thousands falling victim each year, losing millions, it’s high time we talk about it. Stick around as we unpack the signs, share some wild stories (made up but based on real patterns), and wrap up with FAQs and a solid conclusion. Let’s get into it, shall we?

Digital Arrest

What Exactly is a Digital Arrest Scam?

First off, let’s clear the air on what we’re dealing with here. A Digital Arrest scam isn’t some futuristic jail cell in the cloud – though that does sound kinda sci-fi! Instead, it’s a sneaky fraud where bad guys pretend to be law enforcement officers. They contact you through calls, messages, or even video chats, threatening to “arrest” you digitally. What does that even mean? Basically, they claim they’ll freeze your accounts, ruin your reputation, or haul you in virtually unless you pay up right away.

These scams exploded in popularity around 2024, hitting headlines as more people went online for everything from banking to shopping. Scammers love this because it’s all remote – no need to show up at your door with real handcuffs. They bank on your panic, making you think you’re wrapped up in money laundering, drug trafficking, or some other serious crime. Before you know it, you’re transferring money to “clear your name.” Sneaky, huh?

But here’s the kicker: Real arrests don’t happen over the phone or Zoom. Law enforcement shows up in person or sends official papers through proper channels. If someone’s demanding money to avoid a Digital Arrest, that’s your first red flag waving wildly. These fraudsters often target seniors or folks who’ve just come into some cash, like retirees with hefty payouts. Why? Because they’re seen as easier marks, less tech-savvy maybe, and more likely to have savings stashed away.

How Digital Arrest Scams Evolved

Back in the day, scams were simple – think email princes from Nigeria. But as tech got smarter, so did the crooks. Digital Arrest scams kicked off with basic phone calls but quickly leveled up to video conferences where scammers don fake police outfits and wave around phony documents. They’ve even started using AI to mimic voices or create deepfakes, making it harder to tell what’s real.

In places like India, where digital payments are everywhere, these scams have become a nightmare. Reports from banks and cyber cells show a spike, with victims losing anywhere from a few thousand to lakhs of rupees. It’s not just about money, though; the emotional toll is huge. People feel violated, scared, and sometimes even ashamed for falling for it. Transitioning from old-school fraud to this high-tech hustle, scammers have adapted to our always-online lives, turning our devices against us.

Tactics Behind a Digital Arrest Scam

Okay, let’s peel back the layers on how these scams actually work. It’s like a well-rehearsed play, with acts designed to hook you in and reel you out of your cash. Understanding the steps can help you spot the script early and hang up before the curtain falls.

Step-by-Step Breakdown of How It Unfolds

  1. The Initial Hook: It all starts with a call or message from someone claiming to be from a courier service or bank. They might say a package in your name was seized with illegal stuff inside – drugs, fake IDs, you name it. This plants the seed of doubt and fear.
  2. Escalation to Authority: Next, they “transfer” you to a supposed police officer or cyber crime unit. Suddenly, you’re on a video call with a guy in a uniform, badges gleaming, spouting legal jargon. They accuse you of being linked to a big crime ring.
  3. Building the Pressure: Here’s where the Digital Arrest comes in. They threaten to issue a digital warrant, freezing your assets or publicly shaming you online. Fake documents pop up on screen – arrest warrants, court orders – all looking legit but totally bogus.
  4. The Money Demand: To “resolve” this, they demand payment. It could be for bail, fines, or to “verify” your accounts. They push for quick transfers via UPI, wire, or even gift cards – anything untraceable.
  5. Isolation Tactics: They tell you not to tell anyone, claiming it’s confidential. This keeps you from seeking help while they drain your wallet.

Whew, exhausting just thinking about it! But knowing this sequence is like having a cheat sheet. If a call follows this pattern, bail out fast.

Common Tools and Tricks Scammers Use

Scammers aren’t dummies; they’ve got an arsenal. They spoof phone numbers to look official, use apps like WhatsApp for video, and even create fake websites mimicking government portals. Sometimes, they hack into your social media for personal details, making their story more convincing. Ever heard of “vishing”? It’s voice phishing, and it’s their bread and butter.

Dangling the threat of immediate action, they create urgency – “Pay now or face arrest!” But remember, real cops don’t ask for money over the phone. That’s a dead giveaway.

How to Recognize a Digital Arrest Scam in Action

Alright, now for the meat and potatoes – the signs that scream “scam!” Pay attention to these, and you’ll be way ahead of the game. It’s all about trusting your gut and questioning everything.

Unsolicited Contacts and Urgency

If you didn’t reach out first, why are they calling you? Scammers love cold calls because they catch you off guard. And that rush? “Act now or else!” – classic ploy to skip your common sense. Real emergencies from authorities come with time to verify.

  • Unexpected Calls: From “police” or “agencies” you never contacted.
  • High-Pressure Tactics: Demands to decide on the spot, no time to think.
  • Threats of Immediate Harm: Like account freezes or public exposure.

Watch out! If they’re pushing too hard, it’s probably a Digital Arrest scam in disguise.

Fake Credentials and Documents

These guys are pros at forgery. They’ll flash badges, send PDFs of warrants, but a quick check reveals flaws – wrong spellings, outdated logos, or mismatched details.

  • Phony Uniforms: On video, but the background looks like a basement, not a station.
  • Bogus Emails or Links: Leading to malware or fake sites.
  • Requests for Personal Info: Like OTPs, bank details – never share!

Informal chats turning serious? Hang up and call the real authorities using numbers from official sites.

Unusual Payment Methods

Here’s a biggie: Legit law enforcement doesn’t take gift cards or crypto. If they’re asking for odd payments, it’s a scam.

  • Demands for Quick Transfers: Via apps or wires to unknown accounts.
  • No Receipts or Traces: They avoid anything trackable.
  • Promises of Refunds: After “verification,” but it never happens.

Exclamations like “Just pay this small fee!” should set off alarms. Don’t bite!

Real-Life (But Imagined) Stories: Victims of Digital Arrest Scams Share Their Tales

To make this hit home, let’s imagine some stories based on common patterns. These aren’t real people, but the scenarios? Spot on from what we’ve seen in reports.

Grandma’s Close Call

Picture this: Mrs. Patel, a retired teacher in Mumbai, gets a call while baking cookies. “Ma’am, your name’s on a drug parcel!” the voice booms. Shocked, she listens as they escalate to a video with a “cop” threatening Digital Arrest. Heart pounding, she almost transfers 50,000 rupees. But wait – she remembers reading about these scams and hangs up. Phew! Calling her son, they report it, saving her savings.

The Busy Executive’s Blunder

Rushing to a meeting, Mr. Singh picks up a call. “You’re involved in money laundering!” they claim. On video, fake officers show documents. Under pressure, he pays 2 lakhs to avoid “digital handcuffs.” Later, realizing it’s a Digital Arrest scam, he feels foolish but alerts the bank, recovering some funds. Lesson learned: Never act in haste.

The Student’s Scare

Young Aisha, studying online, gets messaged about a “cyber crime link.” They video call, demanding payment or face Digital Arrest. Skeptical, she asks for proof – they fumble. She blocks them and tells friends, turning it into a group laugh. Smart kid!

These tales show how anyone can get targeted, but quick thinking saves the day.

Prevention Tips to Avoid Digital Arrest Scams

Prevention’s better than cure, right? Here’s how to build your defenses against these digital wolves.

Educate and Verify

  • Stay informed: Read up on scams from trusted sources like bank websites or cyber police portals.
  • Verify callers: Hang up and dial official numbers yourself.
  • Use apps: Like Truecaller to flag spam calls.

Secure Your Digital Life

  • Strong passwords: Change ’em often, use managers.
  • Two-factor auth: Extra layer against hacks.
  • Avoid sharing: Personal deets on social media.

Community and Reporting

  • Talk about it: Share with family, spot signs together.
  • Report suspicious activity: To cyber cells or hotlines like 1930 in India.
  • Join forums: Like Reddit threads for real-time tips.

By doing this, you’re not just protecting yourself but helping shut down these operations.

What If You’re Already in the Crosshairs? Steps to Take

Caught in a Digital Arrest scam? Don’t panic – act smart.

  1. Hang Up Immediately: Cut the call, block the number.
  2. Don’t Pay or Share: Anything – info, money, nothing!
  3. Report It: To police, banks, and cyber authorities.
  4. Monitor Accounts: Check for unauthorized activity.
  5. Seek Support: Talk to friends or counselors for emotional help.

Remember, recovering money is possible if you act fast.

FAQs 

Got questions? We’ve got answers. Here are some common ones to clear up any confusion.

What is the main goal of a Digital Arrest scam?

It’s all about scaring you into paying money. They create fake urgency around legal troubles to extort cash.

How can I tell if a call is a real police inquiry?

Real cops don’t threaten over phone or ask for payments. They’ll meet in person or send official notices.

Are Digital Arrest scams only in certain countries?

Mostly big in India, but spreading globally as tech advances. Anyone online is at risk.

What if I’ve already paid? Can I get my money back?

Report immediately – banks can freeze transfers, and police might recover funds. Act quick!

How do scammers get my personal info?

From data breaches, social media, or public records. Be careful what you share online.

Is there a way to test if it’s a scam?

Ask for their badge number and station, then verify independently. Scammers hate that!

Why do they use video calls?

To seem more legit with uniforms and props, building trust fast.

Can kids or teens fall for Digital Arrest scams?

Sure, if they’re online a lot. Educate them early.

Conclusion

Wrapping this up, we’ve journeyed through the shadowy world of Digital Arrest scams, from what they are to how to spot ’em and fight back. It’s a wild ride in our digital age, where crooks lurk behind screens, but armed with knowledge, you can outsmart them every time. Don’t let fear rule – question, verify, and report. If we all stay vigilant, these scams will lose their grip. Stay safe out there, folks! Remember, the best defense is a sharp mind and a skeptical eye. If you’ve got stories or tips, share ’em in the comments – together, we can beat this.

Tax Audit – 10 Mistakes That Invite Income Tax Notices and Scrutiny

0

Filing your income tax return in India isn’t just a routine task you do once a year. It’s a serious matter that demands care, honesty, and a good understanding of the rules. Get it wrong, and you could end up facing questions from the Income Tax Department, or worse, penalties that hit your pocket hard. Many people think tax filing is simple—plug in some numbers, claim deductions, and hit submit. But small slips can lead to big problems. The department uses advanced tools like Form 26AS, the Annual Information Statement (AIS), and the Taxpayer Information Summary (TIS) to check everything. If something doesn’t match, a notice might land in your inbox.

Think about it: every year, thousands of taxpayers receive notices because of avoidable errors. These aren’t just random checks; they’re triggered by red flags in your return. A notice means extra work—gathering documents, explaining yourself, and sometimes paying fines. In severe cases, it could lead to a full audit, where officials dig deep into your finances. No one wants that stress. The good news is, most issues come from common mistakes. By knowing them, you can steer clear and file with confidence.

Income Tax Mistakes

Tax Audit – 10 Mistakes That Invite Income Tax Notices and Scrutiny

Underreporting or Omitting Income

This is probably the biggest blunder people make. You might think forgetting a small bank interest or a one-time freelance payment isn’t a big deal, but it is. The Income Tax Department has eyes everywhere through digital records. They cross-check your filed income against reports from banks, employers, and investment platforms. If there’s a gap, even a tiny one, it raises suspicions of hiding money.

For example, imagine you’re a salaried employee earning Rs 10 lakh a year. You have a fixed deposit that earns Rs 20,000 in interest, but you forget to include it because the bank didn’t send a reminder. Or perhaps you sold some shares and made a profit of Rs 50,000, but you skip reporting the capital gains, thinking it’s not worth mentioning. Another common case: rental income from a property you own but rent out informally. If the tenant pays in cash and you don’t declare it, the department might spot it through other channels, like utility bills or property records.

Why does this trigger a notice? It’s seen as an attempt to evade tax. Penalties can be up to 200% of the tax due, plus interest. To dodge this, always start by downloading your Form 26AS and AIS from the tax portal. These list all reported incomes. Match them with your bank statements and investment summaries. Use apps or spreadsheets to track everything. If you’re unsure, consult a tax advisor early. Double-check before filing—it’s better to over-report and explain than to underreport and regret.

Claiming Excessive or Unsupported Deductions

Deductions are great—they reduce your taxable income. But pushing them too far without proof is like waving a red flag. Sections like 80C for investments, 80D for health insurance, and 80G for donations have limits, and claims that seem too high compared to your salary often get flagged.

Take a young professional earning Rs 8 lakh. They claim Rs 1.5 lakh under 80C for life insurance and mutual funds—that’s fine. But if they inflate house rent allowance (HRA) by submitting fake rent receipts for Rs 2 lakh when they actually pay Rs 1 lakh, trouble brews. Or someone donates Rs 10,000 to charity but claims Rs 50,000 without receipts. Home loan interest is another hotspot: claiming Rs 3 lakh when your loan is only for Rs 20 lakh doesn’t add up.

The department asks for evidence during verification. No proof? Your claim gets disallowed, and you pay extra tax plus penalties. To stay safe, keep all documents organized. Scan receipts for investments, get proper donation certificates with PAN details, and ensure medical bills are from registered providers. If your deductions look high, add a note in your return explaining why. Tools like tax software can help calculate limits accurately. Remember, honesty saves money in the long run.

Poor Maintenance of Books and Records

If you’re running a business or freelance work, keeping records isn’t optional—it’s required if your turnover crosses certain limits, like Rs 2 crore for businesses. Many skip this, thinking handwritten notes or memory will suffice. But messy books lead to doubts about your honesty.

Picture a small shop owner with Rs 50 lakh turnover. They don’t keep invoices for purchases or sales ledgers. When audited, they can’t prove expenses like Rs 10 lakh on stock. Or a doctor who mixes personal and professional bank accounts, making it hard to separate fees from family spending. During scrutiny, officials question every entry, leading to added taxes on unproven claims.

Weak records suggest possible fraud, triggering deeper checks. Fix this by using simple accounting apps like Tally or QuickBooks. Scan all bills and vouchers monthly. Keep separate accounts for business. For professionals, log client payments with dates and amounts. Retain records for at least 6 years. This not only avoids notices but also helps in business planning. Start small—dedicate one day a month to organizing.

Mismatch in TDS or Tax Credits

Tax Deducted at Source (TDS) is money your employer or clients hold back and pay to the government. You claim credit for it in your return. But if your claim doesn’t match Form 26AS or AIS, it’s a direct invite for queries.

Suppose your salary TDS is Rs 1 lakh, but Form 26AS shows Rs 80,000 because your employer filed late. You claim the full amount, and your refund gets stuck. Or a freelancer gets TDS from multiple clients, but one client enters the wrong PAN, causing a mismatch. Refunds are withheld until fixed, and repeated issues lead to scrutiny.

This happens due to others’ errors or your oversight. Always check Form 26AS before filing. If there’s a discrepancy, contact the deductor (like your boss or client) to correct their TDS return. Use the tax portal’s grievance section if needed. Track TDS certificates (Form 16 or 16A) throughout the year. This simple step ensures smooth processing and quick refunds.

Engaging in Large or Frequent Cash Transactions

Cash is convenient, but in tax eyes, it’s suspicious. Deposits over Rs 10 lakh or payments above Rs 2 lakh in cash can trigger reports to the department. They want to know the source—is it undeclared income?

Consider buying a car for Rs 15 lakh in cash. The dealer reports it, and if you can’t explain where the money came from, expect a notice. Or a business owner depositing Rs 5 lakh cash weekly without records— it looks like unaccounted sales. Property deals are common too: paying Rs 20 lakh cash for land without banking proof.

With digital India, cash raises eyebrows. Always use cheques, UPI, or bank transfers for big amounts. For unavoidable cash, keep source proofs like withdrawal slips or sale deeds. If depositing large cash, add an explanation in your return. Limit cash to small daily needs. This reduces risk and makes tracking easier.

Showing Unexplained Swings in Income or Losses

Your tax return tells a story. Sudden jumps or drops without reason make the department curious. A big loss one year followed by high profits might seem like manipulation.

For instance, a trader shows Rs 10 lakh profit in year 1, then Rs 2 lakh loss in year 2 due to market crash—but no proof. Or a salaried person claims huge deductions suddenly for medical emergencies without bills. Consecutive losses in business could be genuine, like during a pandemic, but without documents, it’s flagged.

They suspect tax dodging. Back up changes with evidence: market reports for losses, bills for expenses. Compare with past years’ returns. Add notes explaining trends, like “Loss due to inventory write-off from fire—insurance claim attached.” Maintain consistent filing habits. This builds trust over time.

Misusing the Presumptive Taxation Scheme

Sections 44AD and 44ADA let small businesses declare income at a fixed rate (like 8% of turnover) without detailed books. It’s easy, but abusing it—understating turnover or claiming extra perks—backfires.

A shop with Rs 1 crore turnover declares only Rs 50 lakh to stay under limits, or claims expenses on top of presumptive income. Or switching schemes yearly to minimize tax without qualifying.

This leads to audits and fines up to Rs 1.5 lakh. Check eligibility: turnover under Rs 2 crore for 44AD. Stick to rules—no extra claims. If opting out, maintain full books. Consult a CA to decide the best scheme. It’s meant to simplify, not cheat.

Non-Transparent Related-Party Transactions

Dealing with family or linked firms? If not at market rates, it looks like shifting income to save tax.

Example: Lending Rs 5 lakh interest-free to a relative’s business, or selling goods to your sister’s company at half price. Without agreements, it’s seen as evasion.

Document everything: loan agreements with interest rates, valuation for assets. Justify business need. Use arm’s length pricing—compare with market. Keep records separate. This protects you during checks.

Missing Tax Audit Requirements or Filing Late

If your business turnover exceeds Rs 1 crore (or Rs 10 crore with mostly digital payments), you need a tax audit under Section 44AB. Skipping it or filing ITR without the report invites penalties up to Rs 1.5 lakh.

A consultant earns Rs 60 lakh but forgets the audit. Or files late, losing loss carry-forward. Late filing also means interest on due tax.

Track deadlines: September 30 for audits, October 31 for ITR. Hire a CA early. Use reminders. Coordinate uploads. Timely filing avoids attention.

Failing to Disclose Foreign Assets or Income

With global ties, many have overseas bank accounts, stocks, or jobs. Not reporting them in Schedule FA or foreign income is a major oversight.

Say you have a US bank account with Rs 2 lakh interest, or own shares in a foreign company. Forgetting to declare invites black money suspicions.

Penalties are steep—up to Rs 10 lakh per year. Use the tax portal’s foreign asset section. Report even if no income. Gather statements yearly. If unsure, seek expert help.

In conclusion, these mistakes are avoidable with planning and care. Start early, use technology, and double-check. If in doubt, get professional advice. Clean filing means peace of mind—no notices, quick refunds. Stay compliant, and taxes become less daunting.