Blog Page 52

Lease Calculator: A Simple Tool to Simplify Your Leasing Journey!

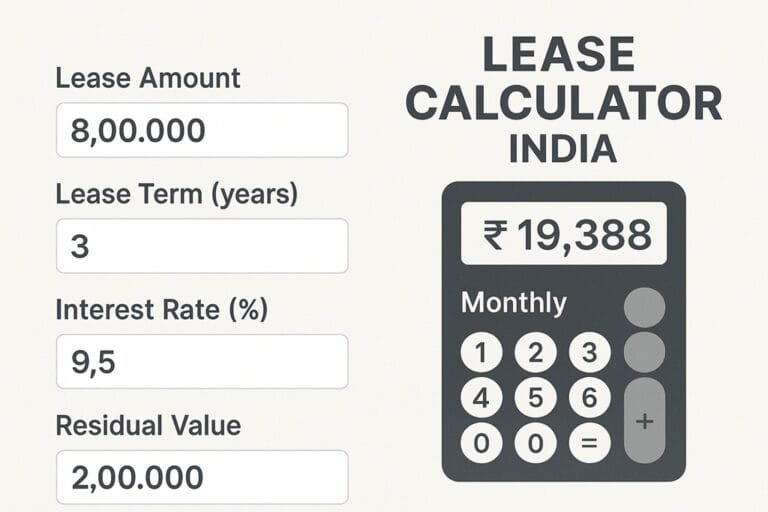
Ever wondered how much you’ll actually end up paying for that new car, office space, or industrial equipment you’re planning to lease? Well, that’s where a Lease Calculator India steps in!

In a country where leasing is gaining momentum — from startups renting office furniture to companies leasing cars for employees — understanding the math behind lease payments can save you from hidden surprises. A lease calculator acts like your personal financial assistant, crunching numbers in seconds and helping you make better leasing decisions.

But here’s the thing — most people dive into leasing without truly knowing what they’re signing up for. The terms sound fancy — “residual value,” “lease term,” “interest rate” — but they can quickly become confusing. That’s why this article will break everything down in plain, simple language and show you how a Lease Calculator India can make the entire process smooth as butter.

So, ready to decode leasing like a pro? Let’s get started!
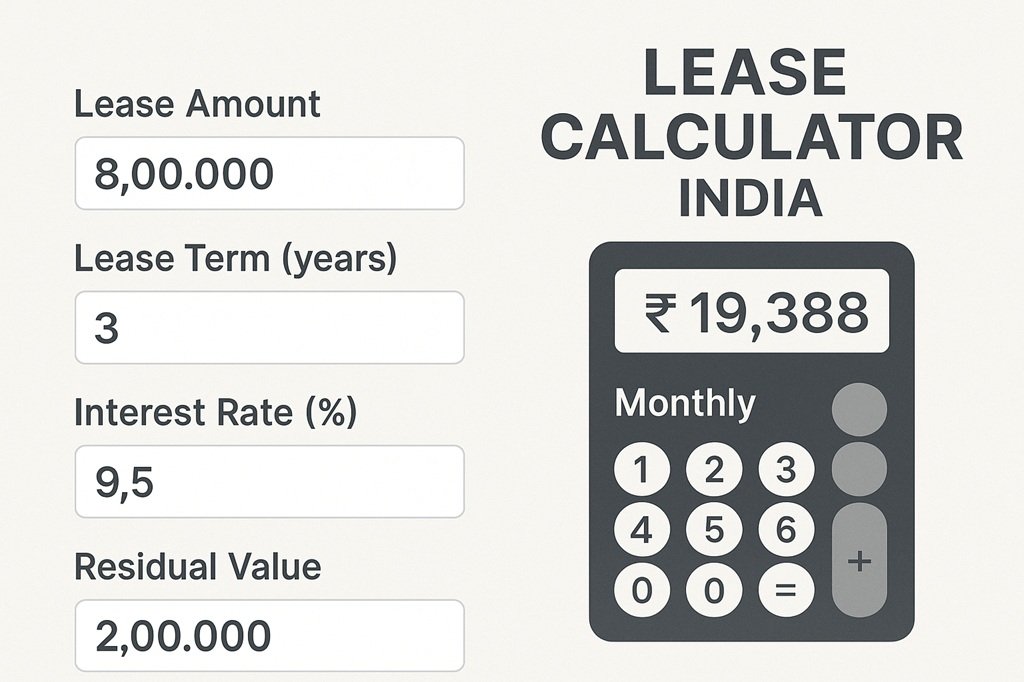
Lease Calculator India


What Is a Lease Calculator?

A Lease Calculator is an online or digital tool that helps you estimate how much you’ll need to pay every month for a lease. Whether it’s for a car, machinery, or commercial property, this calculator uses a few key inputs like:

  • Asset cost (price of the vehicle, property, or equipment)
  • Lease tenure (duration)
  • Interest rate or money factor
  • Residual value (the item’s estimated worth at the end of the lease)

Once you plug in these numbers, the calculator instantly shows your monthly lease payment, total cost, and interest portion — giving you complete clarity before signing any deal.

It’s like having a financial crystal ball that lets you peek into the future of your payments!

Why Leasing Is Getting Popular in India

Before we dive deeper into the calculator, let’s talk about why leasing itself is booming in India.

Earlier, most Indians believed in owning everything — be it cars, houses, or even laptops. But times are changing fast! Here’s why leasing is becoming the preferred choice:

  1. Lower Upfront Costs:
    You don’t have to pay the full amount of an asset; just a fraction of it in installments.
  2. Tax Benefits:
    Businesses can often deduct lease expenses, reducing their taxable income.
  3. Flexibility:
    At the end of the lease, you can return, upgrade, or buy the asset — depending on what suits you best.
  4. No Worries About Depreciation:
    You don’t have to stress over the asset losing value over time — that’s the lessor’s problem!

With such perks, leasing feels like the modern way to own things — without actually owning them.

How Does a Lease Calculator India Work?

You might be thinking, “Alright, sounds good — but how exactly does a lease calculator work?” Let’s unpack it step by step.

Step 1: Input the Basic Details

Most calculators will ask you for:

  • Asset Price (Cost Price) – say ₹10,00,000 for a car.
  • Lease Term (Tenure) – maybe 3 years (36 months).
  • Interest Rate (or Money Factor) – say 10% annually.
  • Residual Value – maybe ₹4,00,000 after 3 years.

Step 2: Calculation in Action

The Lease Calculator India uses a mathematical formula that factors in depreciation, financing cost, and tenure to estimate your monthly installment.

In essence:

Monthly Lease Payment = Depreciation Fee + Finance Fee

Where:

  • Depreciation Fee = (Asset Cost – Residual Value) ÷ Lease Term
  • Finance Fee = (Asset Cost + Residual Value) × Money Factor

Step 3: Get Instant Results

Once you hit “Calculate,” the tool displays:

  • Monthly Lease Payment
  • Total Lease Cost
  • Interest Cost Over Time

Voila! You get all the key numbers in seconds — no spreadsheets, no manual math, just clarity!

Benefits of Using a Lease Calculator India

Using a Lease Calculator India isn’t just about convenience; it’s about making smarter financial choices. Let’s dive into why it’s such a game-changer.

  1. Accurate Estimates

Say goodbye to guesswork! A lease calculator provides exact figures so you know what you’re getting into before signing any agreement.

  1. Helps Compare Different Deals

Leasing offers vary — some may seem cheaper upfront but costlier long-term. The calculator helps you compare multiple options side by side.

  1. Time-Saver

Instead of crunching complex numbers manually, the calculator gives you instant, precise results in seconds.

  1. Financial Transparency

You can clearly see how much you’re paying for depreciation, interest, and other charges.

  1. Perfect for Businesses and Individuals

Whether you’re a small business leasing equipment or an individual leasing a car, the Lease Calculator India fits all use cases.

Types of Leases You Can Calculate

Different leasing types come with different terms. Here’s a quick overview of what the Lease Calculator India can handle:

  1. Operating Lease

Used when you want short-term use of an asset without ownership. The calculator helps figure out periodic payments for the lease duration.

  1. Finance Lease

If you plan to eventually own the asset, this calculator helps estimate total cost and EMI-like payments.

  1. Vehicle Lease

For car leasing — one of the most popular forms in India — the Lease Calculator India can tell you monthly payments, residual values, and interest costs easily.

  1. Equipment Lease

Perfect for businesses leasing machinery, tech devices, or production tools.

  1. Property Lease

Commercial leasing of offices, warehouses, or shops can also be estimated using modified lease calculators.

Car Leasing in India and How the Lease Calculator Helps

Car leasing is catching fire in India, especially among professionals who love driving new models every few years. But before you drive off into the sunset, let’s see how the Lease Calculator India makes this process seamless.

Let’s Take an Example:

  • Car Price: ₹15,00,000
  • Lease Term: 4 years
  • Interest Rate: 9%
  • Residual Value: ₹6,00,000

Using a Lease Calculator India, you can quickly see:

  • Monthly Payment ≈ ₹22,000 (approx.)
  • Total Lease Cost ≈ ₹10,56,000

This tells you exactly what you’ll spend during the lease period — no hidden surprises!

Difference Between Lease and Loan Calculators

Many people confuse lease calculators with loan calculators. But here’s the key difference:

Feature

Lease Calculator

Loan Calculator

Ownership

You don’t own the asset

You own the asset

Payment Covers

Depreciation + Interest

Principal + Interest

End of Term

Option to buy/return

Full ownership

Monthly Cost

Usually lower

Usually higher

Depreciation Risk

Lessor bears it

You bear it

So, while a Loan Calculator helps with ownership, a Lease Calculator India helps with affordability and flexibility.

Factors That Affect Lease Calculations

Before you jump in, keep an eye on these crucial factors that can influence your lease payment:

  1. Interest Rate

Even a 1% change in rate can significantly alter your total cost.

  1. Tenure

Longer tenures mean smaller monthly payments but a higher total outflow.

  1. Residual Value

The higher the residual value, the lower your monthly lease payments.

  1. Down Payment

Paying a bit upfront reduces your monthly load.

  1. Taxes and Fees

Some leases include maintenance, insurance, or GST — all of which impact the final amount.

How to Use a Lease Calculator India Effectively

Here are some quick tips to get the most accurate results:

  1. Gather All Details — Know the asset cost, expected life, and residual value.
  2. Use Realistic Interest Rates — Don’t underestimate!
  3. Compare Multiple Scenarios — Change the tenure or down payment to see what suits your budget.
  4. Include Hidden Costs — Always factor in taxes, insurance, and processing fees.

Doing this ensures your Lease Calculator India results mirror real-world figures closely.

Advantages of Leasing Over Buying

Still confused whether to buy or lease? Here’s a simple breakdown:

  • Lower Monthly Payments: Leasing usually costs less per month.
  • Access to Latest Models: Upgrade easily when the lease ends.
  • No Depreciation Worries: You don’t lose money on resale.
  • Maintenance Included: Many leases cover service costs.
  • Tax Savings: Especially useful for businesses.

Clearly, leasing makes sense if flexibility and affordability top your list!

When Not to Lease

Leasing isn’t always ideal. Avoid it if:

  • You plan to use the asset for many years.
  • You prefer full ownership.
  • You drive or use the asset excessively (higher usage = penalties).
  • You want to customize or modify the asset.

FAQs

  1. Is a Lease Calculator accurate?

Yes! It gives a close estimate based on your provided data. However, actual rates and charges may vary slightly depending on your lender or leasing company.

  1. Can I use a Lease Calculator for personal and business purposes?

Absolutely. Whether you’re leasing a car for personal use or machinery for your company, the Lease Calculator India works perfectly in both cases.

  1. What’s the difference between EMI and lease payment?

An EMI includes repayment of principal plus interest, while a lease payment mostly covers depreciation and financing cost — not ownership.

  1. Can I negotiate lease terms after using the calculator?

Yes, and you should! Once you have the figures, use them to negotiate better rates or terms with the lessor.

  1. Do lease calculators include taxes?

Some do, some don’t. Always check whether GST or other charges are factored in for accurate results.

Conclusion

Leasing is no longer a fancy financial trick reserved for big corporations — it’s for everyone who values convenience, flexibility, and smart money management. And at the heart of this new leasing wave lies the Lease Calculator India — your trusty companion that simplifies complex math, saves time, and ensures you never pay more than you should.

So next time you’re considering leasing a car, equipment, or property, don’t just rely on verbal promises or fancy brochures. Fire up a Lease Calculator India, punch in the numbers, and let the data speak for itself. Because when you understand your lease, you control your finances — and that’s true financial freedom!

What to Know Before Buying a Private Health Insurance Policy

private health insurance

Buying private health insurance isn’t something you do lightly. The policy you choose affects your health, your finances, and your peace of mind. With so many health insurance plans available, it’s easy to feel overwhelmed.

A better approach is to focus on what matters most. When you know which details to compare and what questions to ask, you’ll be able to choose a policy that fits your needs, supports your lifestyle, and helps you avoid costly mistakes.

Your Health Needs

Start by looking at what you need most. Your age, medical history, and family situation all matter. If you’re young and healthy, affordability may be your top priority. If you’re managing chronic conditions, coverage for prescriptions and specialists is key. Think about both now and the future. Even if you don’t need much care today, your needs could change.

If you’re covering loved ones, family health insurance plans may provide broader protection at a better value than individual policies.

Treatment Coverage

On paper, many insurance options look the same. But once you look closely, you’ll see that coverage varies widely. Some plans emphasize hospital care, while others lean on preventive care, doctor visits, or outpatient treatment. Unlike public health insurance like Medicaid plans or employer-sponsored coverage, private policies offer more flexibility, but they also require more careful review.

Your lifestyle matters, too. If you move often for work, you may run into problems with state-specific plans or narrow networks. In these cases, an independent insurance agency can be a big help. For example, they can point you toward tailored private health plans such as the best private health insurance for travel nurses. Expert guidance makes the process easier and gives you confidence that your medical insurance plan matches your real needs.

Costs Beyond Premiums

Premiums may grab your attention first, but they’re only part of the bigger picture. Other charges often determine what you’ll actually spend during the year:

  • Deductible: The amount you pay before insurance starts sharing costs.
  • Co-pay: A flat fee you pay at the time of service, like a doctor’s visit or prescription.
  • Coinsurance: The percentage you pay for covered services after meeting your deductible.

Together, these expenses form your out-of-pocket costs. Every plan also sets an out-of-pocket maximum, which is the most you’ll ever pay in a year for covered care. After you hit that limit, insurance pays 100% of eligible expenses.

For example, a plan with a low monthly premium may look affordable until you realize it comes with a high deductible. That means you’ll pay a lot before your insurance even starts covering expenses. On the other hand, a higher premium plan may cost more upfront but reduce what you owe for prescriptions or doctor’s visits.

The right balance depends on how often you expect to use your plan. Carefully comparing premiums against expected medical costs helps you avoid unpleasant surprises down the road.

Provider Networks

Every insurance plan relies on a network of doctors, clinics, and hospitals. These networks decide where you can go for affordable care. If your preferred doctor isn’t part of the network, you may end up paying much more or even losing access altogether. Out-of-network care can sometimes double or triple your bill.

Make a list of the providers you already trust and want to keep seeing. Then compare that list with the plan’s network to avoid surprises. If you travel often or move around, a national network is especially valuable. It makes it easier to access a wide range of healthcare services without adding unexpected costs.

Prescription Drug Coverage

If you take medications regularly, this is an important feature to review. Each insurer has a formulary, or drug list, that shows which prescriptions are covered and at what cost. Some drugs may require higher co-pays or prior approval.

prescription drug

Before signing up, compare the formulary against the prescription drugs you use now. Even if you’re not taking any medication today, it’s smart to choose a plan with reliable prescription drug coverage so you’re prepared if your needs change.

Exclusions and Limits

Not every service or treatment is automatically included. Some plans exclude alternative therapies, limit coverage for fertility treatments, or impose waiting periods on pre-existing conditions. These rules can cause major problems if you don’t know about them.

Always read the fine print. Ask direct questions about what isn’t covered before you commit. Understanding exclusions upfront saves you from costly surprises later.

Additional Benefits

The basics are important, but extras can add real value to your policy. Depending on the plan, you may find coverage for:

  • Dental and vision care: Some plans cover dental cleanings, routine eye exams, or glasses.
  • Maternity benefits: Coverage for prenatal visits, childbirth, and newborn care, which is especially valuable if you’re planning to start your family.
  • Mental health benefits: Access to counseling, therapy, or support programs.
  • Telehealth services: Virtual visits that save you time and reduce costs.
  • Wellness programs: Perks like gym discounts, nutrition coaching, or smoking cessation support.

Don’t overlook these plan benefits. They may seem secondary, but they can save you money and improve your quality of care.

Insurer Reputation

Even the best plan loses value if the insurer has poor customer service. Look into how quickly they process claims, how they handle disputes, and how satisfied current members are. Independent ratings and customer reviews can help you spot potential red flags.

You should also weigh financial stability. A strong provider is more likely to support you in the long term. Choosing a reliable insurance company gives you confidence that your coverage will be there when you need it.

Conclusion

Buying private health insurance deserves thoughtful planning. When you understand your needs, compare coverage closely, and factor in more than just premiums, you set yourself up for better care and fewer financial surprises.

With the right policy in place, you’ll spend less time stressing about costs and more time focusing on living a healthier, more secure life.

Stock Average Calculator Your Smart Guide to Smarter Investing

Hey, have you ever jumped into the stock market, buying shares here and there, only to scratch your head later wondering what your average cost really is? Well, that’s where a stock average calculator comes in handy, especially in a bustling market like India’s. Picture this: you’re investing in hot stocks on the NSE or BSE, dipping in at different prices over time. Without crunching those numbers properly, you might end up flying blind. But with a stock average calculator, it’s like having a trusty sidekick that simplifies everything. In this article, we’ll dive deep into what makes this tool a game-changer for Indian investors. From the basics to pro tips, we’ll cover it all in a fun, straightforward way. And trust me, by the end, you’ll be itching to try one out yourself!

India’s stock market has been on a rollercoaster ride lately, hasn’t it? With indices like the Sensex hitting new highs and then dipping unexpectedly, keeping track of your investments isn’t just smart – it’s essential. A stock average calculator helps you figure out the average price you’ve paid for a stock, factoring in multiple buys. This isn’t some fancy jargon; it’s a simple concept that can save you from costly mistakes. Whether you’re a newbie trading via apps like Zerodha or Groww, or a seasoned player with a diversified portfolio, understanding this tool can make your financial journey smoother. So, let’s get started, shall we? We’ll break it down step by step, throwing in some real-life examples along the way.

Stock Average Calculator

What Exactly is a Stock Average Calculator?

Alright, let’s cut to the chase. A stock average calculator is basically a nifty tool that helps you compute the average cost of your shares when you’ve bought them at different prices over time. You know, like when you snag some Reliance Industries stock at ₹2,500 one month and then grab more at ₹2,300 the next – it averages that out for you. In India, where market volatility is as common as chai stalls, this calculator becomes your best friend.

Think about it: without one, you’d be scribbling numbers on paper or fumbling with spreadsheets, prone to errors. But pop those details into a stock average calculator, and bam! You get an instant readout. It’s not rocket science; it’s just smart math tailored for investors. And here’s the cool part – many online versions are free and super user-friendly, designed with Indian users in mind, complete with rupee symbols and local stock tickers.

 How Does a Stock Average Calculator Work?

 The calculator uses a simple formula:

Average Price = (Total Cost of All Shares) ÷ (Total Number of Shares)

Here’s a step-by-step breakdown:

  1. Multiply the price you paid per share by the number of shares bought.
  2. Do the same for each purchase.
  3. Add up the total cost.
  4. Add up the total number of shares.
  5. Divide the total cost by the total number of shares.

Example:

  • Bought 100 shares at ₹300 = ₹30,000
  • Bought 50 shares at ₹250 = ₹12,500
  • Bought 50 shares at ₹350 = ₹17,500

Total Cost = ₹60,000 | Total Shares = 200

Average Price = ₹60,000 ÷ 200 = ₹300

So, even though you bought at three different prices, your average comes to ₹300.

Step-by-Step: Using a Basic Stock Average Calculator

If you’re new to this, don’t sweat it. Here’s a quick guide:

  1. Gather Your Data: Jot down each purchase – date, shares bought, price per share, and any extras like STT (Securities Transaction Tax).
  2. Input the Numbers: Plug in your buys one by one. The calculator does the heavy lifting.
  3. Review Results: It’ll show your weighted average cost. Compare it to the current market price to gauge your position.
  4. Adjust for Extras: If there’s a dividend or rights issue, some advanced calculators factor those in too.

See? Using a stock average calculator is a breeze. And if you’re tech-savvy, you can even build a simple one in Excel – but why bother when free ones are everywhere?

Benefits of Using a Stock Average Calculator in India

Wow, where do I even start? The perks are endless. First off, it helps with tax time. In India, capital gains tax depends on your holding period and cost basis. A stock average calculator ensures your average is spot-on, avoiding IRS – er, Income Tax Department – headaches.

Then there’s the psychological boost. Knowing your true average keeps you from panic-selling during dips. Remember the 2020 crash? Many who used these tools held on and reaped rewards when markets bounced back.

Top Advantages for Everyday Investors

  • Better Decision-Making: Spot when to average down – buying more at lower prices to pull your average cost south.
  • Portfolio Tracking: Manage multiple stocks without losing your mind. It’s like herding cats, but easier!
  • Cost Efficiency: Factor in hidden fees, ensuring your calculations are realistic.
  • Learning Tool: For beginners, it teaches investing basics through hands-on use.

And let’s not forget, in a country with over 10 crore demat accounts, staying ahead means using tools like the stock average calculator smartly.

Tips to Avoid These Blunders

  • Double-check inputs: Typos happen, especially with big numbers.
  • Use historical data: Pull accurate prices from NSE/BSE sites.
  • Review regularly: Markets change; so should your calculations.

By steering clear of these, your stock average calculator becomes a powerhouse, not a headache.

Real-Life Examples 

Let’s make this relatable with stories. Imagine Raj, a Mumbai IT guy. He buys 50 Infosys shares at ₹1,800, then 50 more at ₹1,600 during a dip. Using a stock average calculator, his average is ₹1,700. When it hits ₹2,000, he sells for a tidy profit. Simple, right?

Or take Priya from Bangalore. She’s into SIPs but for stocks. Over a year, she averages down on Adani Ports amid volatility. Her calculator shows she’s ahead, boosting her confidence.

These aren’t fairy tales; they’re everyday wins in India’s market.

Advanced Strategies with the Stock Average Calculator

Once you’re comfy, level up! Use it for rupee-cost averaging – buying fixed amounts regularly, regardless of price. It’s like dollar-cost but in rupees. In volatile times, it shines.

Combine with technical analysis: If your average is below support levels, hold tight. Tools like TradingView pair well with calculators for this.

And for pros? Portfolio rebalancing. Calculate averages across holdings to spot over/under weights.

FAQs 

Got questions? We’ve got answers!

What is the difference between simple and weighted average in a stock average calculator? Simple is just mean price; weighted factors in quantities bought. Always use weighted for accuracy!

Can I use a stock average calculator for mutual funds too? Absolutely! Many tools handle NAV averaging for SIPs.

Is there a free stock average calculator app for Android in India? Yep, like Groww or Zerodha – download and go.

How does tax treatment work with averaged costs? In India, use FIFO for short-term gains, but averaging helps track long-term holdings. Consult a CA, though!

What if I sell partial shares? Does the calculator adjust? Most do; input sales to update your remaining average.

Are there any limitations to online stock average calculators? They rely on your inputs, so garbage in, garbage out. Plus, no advice – that’s on you.

Conclusion

The Stock Average Calculator is more than just a number-crunching tool—it’s a sanity check for every investor navigating India’s unpredictable stock market. It helps you figure out your true average cost, keeps emotions at bay, and empowers you to make smarter buy-sell decisions.

But remember, no calculator can replace research, discipline, and a long-term vision. Think of it as a compass—it points you in the right direction, but you still have to walk the journey.

So next time the market dips or spikes, don’t panic—just pull out your calculator, punch in the numbers, and let clarity replace confusion.

The Impact of Inflation on Precious Metals

Inflation has always been a wild card in the financial world. As someone who’s spent decades trading in international banks, I’ve watched it turn markets upside down. Think about the chaos of 2022-2023 when U.S. inflation spiked above 9%, pushing precious metals like gold and silver to new heights. People flocked to them as a shield against eroding purchasing power.

inflation metals

Fast forward to September 2025, and inflation sits at 2.7% year-over-year for July, based on the latest Consumer Price Index data. That’s down from peaks but still enough to keep investors on edge. Precious metals, including gold, silver, and platinum, often shine during inflationary periods because they hold intrinsic value unlike fiat currencies.

This article dives into how inflation drives these assets. We’ll cover the basics, historical patterns, current market vibes, risks with strategies, and what’s next. From my experience at places like JPMorgan, I’ve seen inflation act as rocket fuel for metals, but it’s not always straightforward.

Theoretical Foundations: How Inflation Affects Precious Metals

Inflation erodes money’s value, making tangible assets appealing. Precious metals serve as a hedge because their supply is limited, unlike printed currency.

There are types of inflation: demand-pull from strong consumer spending, cost-push from rising production costs, and monetary from excess money supply. Each impacts metals differently. Gold thrives in monetary inflation as a store of value. Silver and platinum, with industrial uses, react more to cost-push due to demand in electronics or autos.

The correlation is key. Historically, gold’s price tracks inflation with a coefficient around 0.7. Real returns formula helps: Real Return = Nominal Return – Inflation Rate. If inflation hits 5% and gold rises 7%, you net 2%.

From my trading desk, I’ve noticed metals outperform when inflation expectations rise, even before actual spikes. It’s like a fire alarm going off early.

Historical Examples and Case Studies

History shows inflation’s power over metals. In the 1970s stagflation era, with U.S. inflation averaging 7-10%, gold surged from $35 to over $800 per ounce, a 24-fold increase.

The 2008 financial crisis offers another lesson. Inflation fears from quantitative easing drove gold up 25% in 2009 alone. Silver jumped even more, over 50%, thanks to industrial rebound.

More recently, 2022-2025 post-COVID inflation pushed gold past $2,000, peaking near $3,500. Silver hit $50 briefly in 2023. Platinum lagged but gained from supply chain issues.

In my time at Credit Suisse, I traded through the Turkish lira crisis in 2023, where hyperinflation sent locals to gold, spiking global demand. These cases prove metals act as safe havens, but timing matters.

Current Trends and Market Analysis

As of September 2025, inflation hovers at 2.7%, with core at 3.1%. This moderate level supports metals without panic buying. Gold trades around $3,481 per ounce, silver near $39, and platinum at $1,200.

Geopolitical tensions and Fed rate cut expectations add fuel. The XAU/USD live price reflects this, sitting above $3,500 amid dollar weakness.

Crypto competes as “digital gold,” but traditional metals hold steady. Emerging markets like China boost demand.

Here’s a snapshot table:

Metal Correlation with Inflation (1970-2025) Average Growth During Inflation >5% Current Price (September 2025)
Gold 0.72 +15-20% yearly $3,481/oz
Silver 0.65 +25-30% yearly $39/oz
Platinum 0.58 +10-15% yearly $1,200/oz

From Bloomberg and TradingView data, these figures show gold’s steady hedge role. Silver’s volatility ties to industry, while platinum follows auto sector trends.

In Q4 2025, expect metals to rise if PCE data confirms sticky inflation.

Risks, Strategies, and Alternatives

Inflation hedging with metals isn’t risk-free. If deflation hits, prices drop as in 2008’s brief dip. Volatility can swing 10-20% monthly.

Storage costs and no yield make them less ideal for low-inflation times. Over-reliance exposes you to market corrections.

Strategies I’ve used: Allocate 5-10% of portfolios to metals via ETFs like GLD or SLV. Futures for short-term bets on inflation data releases. Diversify with physical holdings for long-term.

Alternatives include TIPS bonds, which adjust for inflation, or crypto like Bitcoin. But these carry higher risk. Real estate offers hedges too, though less liquid.

Balance is key. In my career, mixing metals with bonds smoothed returns during volatile inflation.

Conclusion

Inflation shapes precious metals’ fate, turning them into go-to assets for protection. From 1970s spikes to recent trends, they’ve proven resilient.

Looking ahead, with 2025 inflation at 2.7% and potential Fed moves, metals could climb further. Gold might test $3,600 if rates fall.

As a trader, I advise monitoring CPI and PCE closely. Start small, diversify, and use metals wisely. In uncertain times, they preserve wealth like nothing else.