Blog Page 54

Income Tax Audit Rules – Types, Limits & Compliance

0

Have you ever wondered why some businesses and professionals need to go through an extra check on their finances before filing taxes? It’s all about the income tax audit. This process helps make sure everything is above board when it comes to reporting income and paying taxes. In India, the rules come from the Income Tax Act, mainly under Section 44AB. The idea is to keep things transparent and accurate. If you’re running a business or working as a professional, knowing about tax audits can save you from headaches like penalties or legal issues down the line.

In this article, we’ll dive deep into what a tax audit really means, why it’s done, who has to do it, and how it all works. We’ll also look at the different types, thresholds, forms, and even some real-life examples to make it easier to understand. By the end, you’ll have a clear picture of how to stay on the right side of the law. Let’s break it down step by step, using simple words so anyone can follow along.
Tax Audit

What Exactly Is a Tax Audit?

At its heart, a tax audit is like a thorough review of your financial books. It’s when an expert looks over your records to confirm that your income, expenses, deductions, and taxes are all reported correctly. Think of it as a health check-up for your finances—it spots any problems early.

Under the Income Tax Act, this audit isn’t optional for everyone. It’s mandatory for certain people and businesses. The auditor, usually a chartered accountant, goes through your accounts to ensure they match what you’ve declared in your tax returns. This isn’t just about catching mistakes; it’s about building trust with the tax authorities.

For example, imagine you own a small grocery store. You’ve kept track of daily sales, purchases from suppliers, and expenses like rent and electricity. A tax audit would verify if these numbers add up and if you’ve claimed the right deductions, like for spoiled goods or employee salaries.

The Main Objectives of a Tax Audit

Why bother with all this paperwork? The objectives are straightforward and practical. First, it verifies that your books are kept properly and certified by a qualified auditor. This certification acts like a stamp of approval.

Second, the audit helps spot any oddities or errors during the review. If something doesn’t add up, like an expense that seems too high, the auditor notes it down.

Third, it provides key info to the tax department, such as how you’ve calculated depreciation on assets or if you’ve followed all tax rules.

Finally, it makes it easier for the authorities to check your returns. They can quickly see if your total income is accurate, if deductions are valid, and if everything complies with the law.

Take a freelance graphic designer as an example. Their objectives in an audit might include confirming that client payments are recorded right and that home office expenses are deducted fairly. This way, they avoid overpaying or underpaying taxes.

Why Do We Need Tax Audits in the First Place?

The big reason is to follow the Income Tax Act’s rules. It ensures businesses and professionals stick to the guidelines set by the government. Once the audit is done, filing your returns becomes smoother because everything is already double-checked.

Audits also catch errors early. By examining your accounts, they make sure you’re sharing all the required details. This prevents surprises during tax assessments. Plus, audited returns are easier for the Income Tax Department to process, which speeds things up for everyone.

In real terms, suppose a manufacturing company has complex transactions, like importing raw materials. An audit ensures all customs duties and input tax credits are handled correctly, avoiding disputes later.

Who Has to Get a Tax Audit? The Mandatory Categories

Not everyone needs a tax audit—it’s based on your income levels and type of work. Let’s look at who must do it.

For businesses, if your total sales, turnover, or gross receipts cross Rs. 1 crore in a financial year, you’re in. But there’s a twist: thanks to changes in the Finance Act 2021, this limit jumps to Rs. 10 crore if your cash transactions are less than 5% of total receipts and payments. This helps digital-heavy businesses skip the audit.

Professionals, like doctors, lawyers, engineers, architects, or interior decorators, need an audit if receipts exceed Rs. 50 lakh. If 95% of your receipts are digital, the limit rises to Rs. 75 lakh. The full list of professions is in Rule 6F of the Income Tax Rules, 1962.

Then there are cases under presumptive taxation schemes, like Section 44AD for businesses or 44ADA for professionals. If you’ve opted in but your profits are below the set rate (say, less than 8% for businesses or 50% for professionals), you need an audit to justify it. Also, if your turnover exceeds Rs. 2 crore while under these schemes, an audit is required.

For instance, a consultant who opts for presumptive taxation shows profits at 40% instead of 50%. They’ll need an audit to explain why, perhaps due to high marketing costs.

If you’re carrying forward losses from previous years and want to offset them, or if you’re in certain sectors like trading where turnover is high but margins low, audits might apply too.

Recent Updates to Tax Audit Thresholds

The rules keep evolving to make things easier, especially for small players. Starting April 1, 2021, the business threshold went up to Rs. 10 crore for low-cash businesses. This was a big relief during the pandemic when digital payments surged.

For professionals, the digital receipt boost to Rs. 75 lakh came in recently too. These changes aim to reduce compliance burdens.

Picture a online seller on platforms like Amazon. If 98% of their payments are via UPI or cards, and turnover is Rs. 8 crore, they might not need an audit anymore.

Who Conducts the Tax Audit?

Only qualified chartered accountants (CAs) or CA firms can do this. There’s a cap: each CA can handle up to 60 tax audits per year to ensure quality. For firms, this limit applies per partner.

The auditor reviews your books, verifies transactions, and prepares a report. They don’t prepare your accounts—that’s your job—but they check for accuracy.

In practice, a CA might visit a retail store, sample invoices, check bank statements, and interview the owner to understand operations.

The Turnover Limit Explained in Detail

Turnover is key here. For businesses, it’s the total value of sales or services before deductions. If it hits over Rs. 1 crore (or 10 crore with low cash), audit time.

For professionals, it’s gross receipts—money received for services.

Other scenarios: If you run multiple businesses, combine their turnovers. Same for professions. If you have both a business and profession, treat them separately.

Example: A lawyer who also runs a coaching center. Lawyer receipts: Rs. 40 lakh (no audit). Coaching turnover: Rs. 1.2 crore (audit needed for business part).

Types of Income Tax Audits

Tax audits aren’t one-size-fits-all. While the main one is under Section 44AB, there are variations based on context.

  1. Compulsory Tax Audit: This is the standard one for those exceeding thresholds. It’s required by law to ensure compliance.
  2. Audit under Presumptive Taxation: If you’re under Sections 44AD, 44ADA, or 44AE (for transport businesses), and you declare lower profits or exit the scheme, this type kicks in.
  3. Audit for Specific Sections: Sometimes, audits are needed under other parts, like Section 44BBB for foreign companies or Section 92E for transfer pricing in international deals.
  4. Voluntary Audit: Even if not mandatory, some choose it for credibility, like when seeking loans. Banks often trust audited accounts more.

For types based on forms: Audits use Form 3CA if your accounts are already audited under another law (like companies), or Form 3CB otherwise, along with Form 3CD for details.

Example: A trucking company under 44AE owns 5 vehicles. Presumed income is Rs. 7,500 per ton per month. If they claim less due to downtime, audit required.

The Tax Audit Process: Step by Step

Getting audited isn’t as scary as it sounds. Here’s how it usually goes.

  • First, appoint a CA early in the year. Share all your records: ledgers, invoices, bank statements, vouchers.
  • The auditor plans the audit, perhaps using sampling for large volumes of transactions.
  • They check for compliance: Are depreciations correct? Are TDS deductions made on time?
  • Any issues? They discuss with you and note observations.
  • Finally, they issue the report electronically via the e-filing portal.

A bakery owner might provide purchase bills for flour and sugar, sales registers, and employee payroll. The auditor verifies if GST inputs match income tax claims.

Forms and Reporting Requirements

The reports are standardized. Form 3CA is for entities already audited under other laws, like companies under the Companies Act. It references that audit.

Form 3CB is for others, where the CA certifies the accounts based on their examination.

Both come with Form 3CD, a detailed statement with 41 clauses covering everything from depreciation to loans.

For international transactions, Form 3CEB is used.

Example: In Form 3CD, Clause 18 asks about depreciation. If you bought a computer for Rs. 50,000, the auditor notes the rate (40%) and allowance (Rs. 20,000).

Due Dates for Tax Audits

For most, the deadline is September 30 of the assessment year. For AY 2025-26 (FY 2024-25), it’s September 30, 2025. If you have transfer pricing, it’s October 31.

Extensions happen sometimes, like during COVID, but don’t count on it.

Missing the date? You can still file, but penalties apply.

Penalties for Non-Compliance

Skipping a required audit hurts. Under Section 271B, the penalty is 0.5% of your turnover or receipts, up to Rs. 1.5 lakh.

But if you have a good reason—like a natural disaster, strike, or auditor quitting—under Section 273B, you might avoid it.

Example: A shop with Rs. 2 crore turnover skips audit. Penalty: Rs. 1 lakh (0.5% of 2 crore). If they prove documents were lost in a flood, penalty waived.

Benefits of Getting a Tax Audit

Beyond avoiding fines, audits offer perks. They improve your bookkeeping, spot inefficiencies, and build credibility with lenders or partners.

For a startup, audited accounts can help secure funding. Investors see you’re serious about compliance.

Audits also help in accurate tax planning, like maximizing deductions.

Common Mistakes to Avoid in Tax Audits

Many trip up on simple things. Not maintaining proper books—vouchers missing or ledgers messy—is common.

  • Underreporting turnover, especially cash sales, is another red flag.
  • Forgetting to report related-party transactions in Form 3CD can lead to issues.
  • A restaurant might forget to include catering income, leading to discrepancies.

To avoid this, keep digital records and consult your CA regularly.

How to Prepare for a Tax Audit

Start early. Organize documents: sales invoices, purchase bills, expense receipts, bank passbooks.

Use accounting software for accuracy.

Track depreciable assets and loans.

If under presumptive scheme, document why profits are low—maybe higher fuel costs.

A software developer preparing might list all client contracts, freelance payments, and software purchase receipts.

Real-Life Examples and Case Studies

Let’s look at a few scenarios.

Case 1: Raj runs a hardware store. Turnover: Rs. 1.5 crore, all cash. He needs an audit. Auditor finds overstated expenses; corrects it, saving Raj from future notices.

Case 2: Dr. Priya, a dentist, has Rs. 60 lakh receipts, 90% digital. Since under 95%, she needs audit. It confirms her equipment depreciation claims.

Case 3: A firm under 44AD shows 6% profit instead of 8% due to market slump. Audit verifies with competitor data and expense proofs.

These show how audits protect and clarify.

Frequently Asked Questions 

Q: Can I do the audit myself? No, only CAs can.

Q: What if my turnover is exactly Rs. 1 crore? Still need audit if over.

Q: Are there audits for salaried people? Usually no, unless business income.

Q: How much does it cost? Varies, Rs. 10,000 to 50,000 based on size.

Wrapping It Up

Income tax audits might seem like extra work, but they’re crucial for fair taxation in India. By understanding the rules, thresholds, types, and processes, you can handle them smoothly. Whether you’re a small business owner or a busy professional, staying compliant avoids penalties and brings peace of mind.

Remember, consult a CA for personalized advice. With digital tools and clear rules, audits are more manageable than ever. If your finances are growing, plan ahead—it’s better to be prepared than caught off guard.

RD Calculator India Maximize Your Savings Easily

Hey there, folks! Ever found yourself scratching your head over how much your monthly savings could grow over time? Well, if you’re in India and dipping your toes into the world of recurring deposits, an RD calculator might just be your new best friend. Picture this: you’re stashing away a fixed amount every month, watching it balloon into a hefty sum thanks to compound interest. But crunching those numbers manually? What a headache! That’s where the RD calculator India comes in, making it a breeze to forecast your maturity amount without breaking a sweat.

In this article, we’re diving deep into everything you need to know about RD calculators tailored for the Indian market. Whether you’re a newbie saver or a seasoned investor looking to fine-tune your strategy, we’ve got you covered. We’ll explore how these nifty tools work, why they’re a game-changer, and even toss in some real-life tips to get you started. And hey, by the end, you’ll be equipped to make smarter financial decisions – no fancy degree required! So, let’s jump right in and unravel the magic behind the RD calculator.

Before we get into the nitty-gritty of the RD calculator India, let’s back up a bit. A recurring deposit, or RD as it’s commonly called, is like that reliable old friend who helps you build wealth steadily. Offered by banks and post offices across India, it lets you deposit a fixed amount monthly for a set period – say, from 6 months to 10 years. The beauty? You earn interest on your deposits, compounded quarterly in most cases, turning small contributions into something substantial.

Think about it: in a fast-paced world where expenses sneak up on you, an RD forces you to save regularly. It’s perfect for short-term goals, like funding a vacation or buying a gadget. But here’s the kicker – without knowing how much you’ll end up with, it’s like shooting in the dark. That’s precisely why the RD calculator steps in, helping you visualize the future value of your investments.

RD Calculator India

Now, you might be wondering, why RD when there are fixed deposits or mutual funds? Good question! RDs shine for their flexibility and low risk. Unlike stocks that can tank overnight, RDs are backed by government guarantees up to Rs. 5 lakhs per bank via DICGC. Plus, they’re super accessible – even if you’re earning a modest salary, you can start with as little as Rs. 100 a month.

  • Steady Growth: Interest rates hover around 6-8% annually, depending on the bank.
  • Tax Perks: Interest is taxable, but you can claim deductions under Section 80C for post office RDs.
  • Premature Withdrawal: Possible, though with penalties – better than being locked in completely.

Dangling a carrot for disciplined savers, RDs encourage habit-building. And with an RD calculator India at your fingertips, you can tweak amounts and tenures to see what fits your budget best.

Demystifying the RD Calculator: How It Works

Alright, let’s cut to the chase – what makes an RD calculator tick? Essentially, it’s an online tool that uses a simple formula to predict your RD’s maturity value. The magic happens with compound interest, calculated quarterly. The basic formula? M = P * (1 + r/n)^(nt) – wait, don’t glaze over! Here, M is maturity amount, P is monthly installment, r is annual interest rate, n is compounding frequency (4 for quarterly), and t is tenure in years.

But who wants to juggle spreadsheets? Enter the RD calculator India, plugging in these variables for you instantly. You input your monthly deposit, interest rate, and tenure, and voila! It spits out the total investment, interest earned, and final amount.

Key Inputs for Accurate Calculations

To get spot-on results, feed the RD calculator with the right details. Skimping here could lead to surprises down the line.

  1. Monthly Installment: How much you’re comfy depositing each month. Start small if needed!
  2. Interest Rate: Varies by bank – check current rates from SBI, HDFC, or ICICI.
  3. Tenure: From 6 months to 120 months; longer means more interest, but tie up your money.
  4. Compounding Frequency: Usually quarterly, but confirm with your provider.

Oh, and some advanced RD calculators even factor in taxes or inflation. Talk about a smart upgrade!

Common Pitfalls to Avoid When Using an RD Calculator

Even the best tools can trip you up if you’re not careful. For instance, forgetting to update interest rates – they fluctuate, you know? Or assuming rates stay constant over long tenures, which isn’t always the case in India’s dynamic economy.

Another gotcha: not accounting for penalties on missed payments. Some banks charge for defaults, shrinking your returns. And hey, if you’re using a generic calculator not tuned for India, it might ignore local norms like TDS on interest over Rs. 40,000. Stick to reliable ones from bank websites or trusted apps to steer clear of these blunders.

Benefits of Using an RD Calculator in Your Financial Planning

Why bother with an RD calculator India, you ask? Well, it’s like having a crystal ball for your savings! First off, it empowers you to set realistic goals. Dreaming of a down payment on a house? Plug in numbers and see if your plan adds up.

Transitionally speaking, it also promotes discipline. Seeing projected growth motivates you to stick with deposits – no more skipping months! Plus, in a country where inflation nibbles at savings, an RD calculator helps you outpace it by choosing optimal tenures.

Empowering Women and Young Savers

Interestingly, RDs appeal big time to women in India, offering security without market risks. An RD calculator levels the playing field, letting homemakers or young professionals forecast independently. Imagine a young grad using it to plan for higher studies – empowering, right?

And for families, it’s a tool to teach kids about saving. “Hey junior, let’s calculate how your pocket money grows!” Exclamations aside, it’s practical magic.

Integrating RD Calculator with Other Financial Tools

Don’t stop at RD alone. Pair it with EMI calculators for loans or SIP tools for mutual funds. This holistic view ensures your portfolio balances risk and reward. For instance, if RD returns seem low, maybe shift some to equities – but only after calculating!

Step-by-Step Guide to Using an RD Calculator

Ready to give it a whirl? Here’s a straightforward walkthrough, keeping things simple.

  1. Enter Monthly Amount: Say, Rs. 5,000 – whatever suits your wallet.
  2. Input Interest Rate: Current average? Around 7%.
  3. Select Tenure: Let’s say 3 years for starters.
  4. Hit Calculate: Boom! See total deposit (Rs. 1,80,000), interest (about Rs. 20,000), and maturity (Rs. 2,00,000-ish).

Adjust as needed – maybe bump up the amount for bigger dreams. Easy peasy!

Customizing for Personal Scenarios

Life’s not one-size-fits-all, so tweak away. Planning a wedding? Factor in rising costs. Or if you’re a senior, check senior citizen rates (often higher). The RD calculator India adapts, helping you navigate twists like job changes or bonuses.

Real-Life Stories: How RD Calculators Changed the Game

Nothing beats hearing from real people. Take Raj from Mumbai – he used an RD calculator to plan his kid’s education fund. “I was clueless at first,” he says, “but seeing the numbers grow motivated me to save more!” By year 5, he had enough for tuition, no loans needed.

Or Priya in Delhi, a freelancer with irregular income. She relied on the tool to simulate varying deposits. “It took the guesswork out,” she exclaims. Now, her RD cushions slow months.

These tales show the RD calculator isn’t just math – it’s a life enhancer, turning aspirations into reality.

Comparing RD Returns Across Indian Banks

Curious how banks stack up? Using an RD calculator India, we can compare apples to apples. Assume Rs. 10,000 monthly for 5 years at current rates.

  • SBI: ~7.1% interest – Maturity around Rs. 6,90,000.
  • HDFC: ~7.25% – Slightly higher at Rs. 6,95,000.
  • Post Office: Fixed 7.5% – Tops at Rs. 7,00,000.

See? Small rate differences add up. Always shop around!

Factors Influencing RD Rates in India

Rates aren’t static – RBI policies, inflation, and economy play roles. Post-pandemic, they dipped but are rebounding. An RD calculator helps you lock in at peaks, maximizing gains.

Tax Implications and RD Calculators

Taxes – ugh, right? But an RD calculator often includes them. Interest is added to income, taxed per slab. For seniors, TDS kicks in over Rs. 50,000. Tools like those from Income Tax portals simulate net returns, keeping you compliant.

Form 15G/H can waive TDS if income’s low. Plug these into your calculator for true pictures.

FAQs

What is the minimum amount for an RD in India? It varies, but many banks start at Rs. 100-500 monthly. Check your bank’s policy!

Can I use an RD calculator for post office schemes? Absolutely! Most tools support it, or use India Post’s official one.

Is interest on RD compounded monthly or quarterly? Quarterly in most cases, boosting growth over time.

What if I miss a deposit? Penalties apply, reducing interest. Some banks allow catch-up.

Are RD calculators accurate? Yes, if inputs are correct. But they’re estimates – actuals may vary slightly.

How does inflation affect RD returns? It reduces real value. Aim for rates above inflation for positive gains.

Can NRIs use RD calculators? Sure, but tax rules differ. Use NRI-specific tools.

What’s the difference between RD and FD calculators? RD for monthly deposits; FD for lump sums. Both calculate interest similarly.

Conclusion

Wrapping it up, the RD calculator India is more than a gadget – it’s your ally in building a secure future. From demystifying calculations to inspiring disciplined saving, it simplifies what once seemed daunting. Whether you’re plotting a dream vacation or nesting an emergency fund, harnessing this tool puts you in the driver’s seat.

Remember, saving isn’t about hoarding; it’s about smart growth. So, grab an RD calculator today, play around with scenarios, and watch your money work for you. Who knows? That small step could lead to big leaps! Stay savvy, folks – your financial freedom awaits.

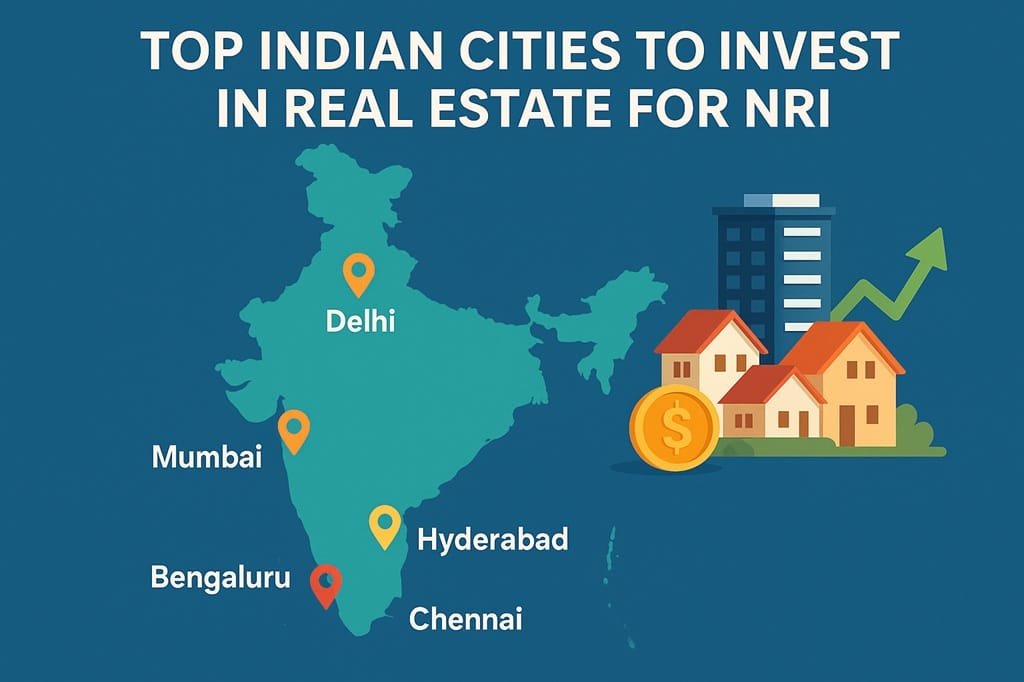
Top Indian Cities for NRI Real Estate Investment 2025

0

India has always been a land of opportunities, and when it comes to property, the story is no different. For decades, Non-Resident Indians (NRIs) have been pouring money into Indian real estate—sometimes for emotional reasons, sometimes for financial growth, and often for both. But as we step into 2025, the investment landscape looks more exciting than ever.

Folks, the numbers don’t lie. NRIs poured in over $13 billion last year, and experts predict it’ll climb even higher this year. Why? Because cities across India are transforming faster than you can say “metro line extension.” From Bengaluru’s startup frenzy to Mumbai’s never-sleep vibe, these spots aren’t just homes—they’re gold mines for rental yields and appreciation. But hold on, it’s not all smooth sailing; you’ve got to navigate taxes, regulations, and picking the right neighborhood. That’s where this guide comes in, like a trusty old friend whispering secrets over chai.

In the pages ahead, we’ll zoom in on the top Indian cities for NRIs to invest in real estate in 2025. We’ll chat about what makes each one tick, from sizzling ROIs to hidden gems you might overlook. Whether you’re eyeing a cozy 2BHK for rental income or a swanky villa for family visits, we’ve got the lowdown. And hey, we’ll toss in some real-talk tips, FAQs, and a wrap-up to tie it all together. Ready to turn those overseas savings into Indian bricks and mortar? Let’s roll!

NRI Investment Real Estate

Why NRIs Are Rushing to Invest in Real Estate in India 2025

Let’s face it—being an NRI means juggling two worlds, and investing in real estate back home feels like a warm hug from the past while padding your future. But why now, in 2025? Well, the stars are aligning in ways that’d make even the most cautious investor crack a smile. First off, the rupee’s softer stance against global currencies means your foreign earnings buy more square footage. Add to that India’s GDP chugging along at 7% plus, and you’ve got a recipe for properties that appreciate like fine wine.

Don’t get me wrong, it’s not just about the moolah. Many NRIs tell me it’s about legacy—building something tangible for kids who might one day call India home full-time. Or heck, just parking funds in a stable spot amid global jitters. Rental yields? They’re hitting 4-8% in hot spots, way better than some bonds gathering dust. And with RERA keeping builders honest, the wild west days of shady deals are mostly gone.

The Big Perks of Investing in Real Estate as an NRI

  • Tax Breaks Galore: No capital gains tax if you hold for over two years, and repatriation up to $1 million a year? Sweet deal!
  • Diversification Magic: Spread those eggs—Indian properties hedge against overseas market dips.
  • Rental Goldmine: Tech hubs mean expats and young pros snapping up leases, filling your pockets monthly.
  • Emotional Payoff: That vacation home in Goa? It’s more than ROI; it’s memories waiting to happen.

Of course, hurdles like FEMA rules or picking a power of attorney exist, but they’re surmountable with a bit of homework. Bottom line? 2025 is prime time to invest in real estate if you’re an NRI eyeing growth without the guesswork.

Bengaluru: The Tech Titan Beckoning NRIs to Invest in Real Estate

Ah, Bengaluru—the city that never sleeps, unless it’s raining, which it does a lot. Nicknamed India’s Silicon Valley, this garden city’s got more startups than you can shake a USB at, drawing in techies like moths to a flame. For NRIs, investing in real estate here isn’t just smart; it’s like hitting the jackpot on a scratch card. With 24% of NRI investments flowing in last year, it’s no wonder folks from Silicon Valley (the California one) are snapping up pads.

What makes Bengaluru a no-brainer? The IT boom, for starters. Areas like Whitefield and Electronic City are buzzing with offices from Google to Infosys, ensuring sky-high rental demand. Imagine your 3BHK pulling in ₹50,000 a month—easy peasy. And appreciation? It’s clocked nearly 79% since 2020, with experts eyeing 10-12% more in 2025 thanks to metro expansions and airport upgrades.

Hotspots and Hidden Treasures in Bengaluru

Wandering through Sarjapur Road feels like stepping into the future—gleaming towers amid coffee plantations. Here’s the scoop:

  1. Whitefield: The OG tech enclave. Properties here yield 4-7% rentals, perfect for long-term flips.
  2. Devanahalli: Near the airport, it’s exploding with affordable villas. ROI? Up to 15% if you time it right.
  3. Indiranagar: Trendy vibes for the young crowd. Not the cheapest, but resale values soar.

But watch out—traffic can test your patience, and water woes pop up now and then. Still, for NRIs wanting to invest in real estate with a side of culture (think endless pubs and parks), Bengaluru’s your bet. Pro tip: Go for ready-to-move-in from reputed builders to skip construction headaches.

Diving deeper, let’s chat ROI. A ₹1 crore investment could net you ₹4-7 lakhs yearly in rent, plus appreciation pushing it to ₹1.1-1.2 crore by year’s end. Not bad, eh? NRIs love it for the lifestyle too—weekend treks to Nandi Hills from your balcony-view flat? Priceless.

Pune: The Education Oasis Where NRIs Love to Invest in Real Estate

If Bengaluru’s the wild party, Pune’s the chill cousin—educated, laid-back, and full of promise. Dubbed the Oxford of the East, this Maharashtra gem pulls in 19% of NRI cash, thanks to its mix of IT parks, top-notch colleges, and that unbeatable Marathi hospitality. Investing in real estate here feels like planting a money tree in fertile soil; it grows steady without the Mumbai madness.

Pune’s charm? It’s got the jobs (think Hinjewadi’s tech sprawl) but none of the overcrowding. Rental yields hover at 2.5-6.3%, but pair that with 8-12% annual appreciation, and you’re golden. Infrastructure’s on fire too—metro lines snaking through, plus the Pune-Mumbai expressway slashing travel time. For NRIs, it’s a safe harbor: properties double in value every five years, ideal for that family getaway or passive income stream.

Pune’s Prime Picks for Savvy Investors

Kharadi’s got that new-kid-on-the-block energy, with malls and offices popping up like mushrooms after rain. Bullet points for the win:

  • Hinjewadi: IT central. A 2BHK here rents for ₹30,000-40,000, with 10% ROI potential.
  • Baner: Green and posh. Villas for the win if you’re thinking legacy.
  • Wakad: Affordable entry, high growth—perfect for first-time NRI buyers.

One downside? Monsoons turn roads into rivers, but hey, character-building! NRIs rave about the schools—your kids could study at Symbiosis while you sip shiraz on the balcony. In 2025, with GDP contributing 13% to Maharashtra, investing in real estate in Pune is like buying low, selling high, on repeat.

Real story time: My pal Raj, an NRI from Dubai, snagged a flat in Kharadi two years back. Now? It’s rented to a startup whiz, and he’s eyeing a second. “It’s not just money,” he says, “it’s roots with returns.”

Hyderabad: Pearls of Wisdom for NRIs Eyeing Real Estate Investments

Hyderabad—where biryani meets billion-dollar deals. This Deccan Plateau darling, with 12% NRI inflows, blends old-world charm (think Charminar sunsets) with new-age hustle in HITEC City. For NRIs itching to invest in real estate, it’s a breath of fresh air: affordable prices, rock-solid infrastructure, and returns that sparkle like the city’s famed pearls.

Why the hype? Pharma and IT giants like Dr. Reddy’s and Microsoft fuel demand, pushing appreciation to 10-15%. Rental yields? A comfy 3.9-5%, especially in Gachibowli where expats flock. Metro Phase II and expressways are turbocharging growth, making suburbs like Tellapur hot tickets. NRIs dig the value—your ₹80 lakh buy could flip to ₹1 crore by 2026.

Standout Spots in Hyderabad’s Skyline

Gachibowli’s skyline rivals Dubai’s, minus the desert. Let’s list ‘em:

  1. Kondapur: Buzzing with offices. Yields up to 5%, great for quick rentals.
  2. HITECH City: The heart of it all. Appreciation? 12% projected.
  3. Miyapur: Emerging, budget-friendly—ideal for diversified portfolios.

Cons? Summers sizzle, but ACs are everywhere. For NRIs, the ease of repatriation and low entry barriers make investing in real estate here a cinch. Imagine video-calling your tenant from Toronto—modern problems, sorted!

ROI breakdown: Invest ₹1 crore, pocket ₹4 lakhs rent yearly, watch it grow 12%. With stable policies, it’s a low-risk thrill.

Mumbai: The Glamour Guru Guiding NRIs to Invest in Real Estate

Mumbai, the city of dreams—or traffic jams, depending on the hour. As India’s financial heartbeat, it snares 14% of NRI investments, luring with Bollywood bling and boardroom buzz. Investing in real estate here? It’s like owning a slice of eternity—prices might dip, but they always bounce back stronger.

Suburbs steal the show: Thane and Navi Mumbai offer bang-for-buck without the Bandra premiums. Yields sit at 3.5-4%, but 10-12% growth? That’s the Mumbai magic. Coastal Road and Metro Line 5 are game-changers, turning Panvel into a powerhouse. NRIs flock for the prestige—a sea-view flat screams success.

Mumbai’s Money-Making Neighborhoods

Navi Mumbai’s got that planned-city polish. Highlights:

  • Thane: Family-friendly, 4% yields, 11% appreciation.
  • Panvel: Airport proximity—ROI rockets to 12%.
  • Powai: Lakeside luxury for the high-rollers.

Downside: Sky-high stamp duties, but waivers help. NRIs love the connectivity—fly in, crash at your investment, fly out. In 2025, with population swelling, demand outstrips supply, making it prime to invest in real estate.

Anecdote alert: Priya from London bought in Thane pre-pandemic. Post? Doubled her money. “Mumbai’s chaos is my calm,” she laughs.

Delhi-NCR: The Power Corridor for NRI Real Estate Investments

Delhi-NCR—where politics meets progress. Clocking 16% NRI shares, this sprawl from Gurgaon to Noida is a beast for investors. Why? Metro webs, expressways, and corporate influx mean 10-15% growth and 4-8% yields. For NRIs, it’s strategic: close to the capital, yet worlds away from the hustle.

Gurgaon’s glass towers house MNCs, while Noida’s greens appeal to families. Dwarka Expressway? It’s flipping suburbs into suburbs-no-more. Investing in real estate here hedges bets—luxury for resale, affordable for rent.

NCR’s Next Big Things

Sector 150 in Noida whispers opportunity. Top picks:

  1. Gurgaon (Dwarka Expressway): 8% yields, 14% growth.
  2. Greater Noida: Budget buys, high upside.
  3. Golf Course Road: Posh, perennial demand.

Cons: Pollution peaks, but green belts help. NRIs swear by the schools and malls—your portfolio’s a lifestyle upgrade.

ROI realness: ₹2 crore in? ₹8-16 lakhs rent, plus 12% bump. Solid.

Chennai: The Steady South Star for NRIs to Invest in Real Estate

Chennai—beaches, autos, and now, booming real estate. With 10% NRI pie, it’s the underdog that bites back. Stable 7-10% growth, thanks to IT and manufacturing. OMR’s the artery, pulsing with sea-view condos. For NRIs, affordability shines—entry at ₹60 lakhs, yields steady.

ECR’s villas scream vacation rental. Metro and port upgrades fuel it. Investing in real estate here? Low volatility, high heart.

Chennai’s Coastal Cash Cows

OMR’s got vibe. List:

  • Guindy: Central, 5% yields.
  • Sholinganallur: Emerging, 9% growth.
  • ECR: Views = value.

Hot? Summers, but sea breezes cool. NRIs dig the culture—festivals from afar.

Ahmedabad: The Business Buzz for Smart NRI Investments

Ahmedabad—Gujarat’s gem, 8-10% growth via GIFT City. Affordable, business-savvy. SG Highway’s modern. For NRIs, it’s diversification done right—yields 4-6%.

Prahlad Nagar’s commercial-resi mix wins. Metro? Coming soon.

Ahmedabad Aces

  • Bopal: Green, growing.
  • Vastrapur: Amenities galore.

Stable, sans drama.

Tips for NRIs Ready to Invest in Real Estate in 2025

Jumping in? Here’s the playbook:

  1. Vet the Developer: RERA-registered only.
  2. Power of Attorney Wisely: Trusty rep on ground.
  3. Tax Savvy: Long hold = low tax.
  4. Diversify Cities: Mix metros and emerging.
  5. Virtual Tours: Zoom your way in.

Currency plays? Lock rates now.

FAQs 

Q: What’s the best city for quick ROI in 2025? A: Hyderabad or Pune—10-15% appreciation, hands down.

Q: Can NRIs buy agricultural land? A: Nope, stick to residential/commercial.

Q: How’s the rental market looking? A: Robust in IT hubs, 4-8% yields average.

Q: Any 2025 policy changes? A: More repatriation ease, watch RBI updates.

Q: First-time tips? A: Start small, consult pros.

Conclusion

Whew, what a whirlwind tour of India’s real estate wonders! From Bengaluru’s tech tango to Mumbai’s monetary mambo, these top Indian cities scream opportunity for NRIs in 2025. Investing in real estate isn’t just about numbers—it’s reclaiming a piece of home, spiced with smart gains. With ROIs climbing and infrastructure leaping, now’s the moment to act. Grab that chai, crunch those numbers, and let your investments bloom. Here’s to your prosperous portfolio—cheers to roots and riches!

Commission Calculator Your Guide to Smarter Earnings

Do you sometimes find it difficult to figure out the figures regarding your commissions? You must be a realtor, insurance agent, freelancer, or maybe a sales rep to earn commission on your services provided to the clients. The only difficulty comes with determining the exact amount of earnings that you have made through your commissions. That’s when the Commission Calculator India comes into play for you.

This online calculator is more than number crunching; it ensures organization and motivation on your part. Thus, if you are inquisitive about what a Commission Calculator India is, how does it work, and what benefits it offers, you have come to the right place.

This article will provide all the information related to the Commission Calculator India starting from its basics up to the advanced features.

Commission Calculator India

What Is a Commission Calculator India?

A commission calculator, in simpler terms, is basically an online program for calculating the amount of money that one gets as commission. Rather than wasting time making calculations with the use of spreadsheets, you only need to enter a few details and voila! You get your commission calculated right away.

You will be getting the services of a virtual assistant who does not make mistakes in arithmetic.

Why Do You Need a Commission Calculator in India?

Commissions are the lifeblood of the Indian market, whether it comes to real estate, stock, mutual fund, insurance policies, or affiliate marketing; commissions are a major portion of your earnings. With so many different commission systems like fixed fee commissions, percentage commissions, or even tiered commissions, the calculations could get too difficult to manage manually.

Why you need a Commission Calculator India?

  • Accurate – No more expensive mistakes from incorrect math.
  • Time-Saver – No more time wasted on Excel spreadsheets.
  • Clear Vision – You know exactly how much you can earn.
  • Planning – You plan for the future income based on current calculations.
  • Motivation – Knowing the accurate figures motivates you to make more sales.

How Does a Commission Calculator India Work?

You don’t need to be a math wizard to use it. Here’s the usual process:

  1. Input Sale Amount – Enter the total sales figure.
  2. Enter Commission Rate – Usually a percentage set by your company or client.
  3. Add Bonus or Deductions (if any) – Some calculators allow you to adjust extra earnings or deductions.
  4. Click Calculate – Instantly see your commission results.

For example:

  • Sale Amount: ₹10,00,000
  • Commission Rate: 2%
  • Commission Earned = ₹20,000

Easy, right?

Conclusion

In the hectic market of India, every single rupee is valuable. What is the use of wasting valuable time trying to figure out confusing spreadsheets when you can get help from a Commission Calculator India? It saves a lot of time, is precise, and ensures that your attention remains directed towards the more important things like sealing deals and earning money.

No matter whether you are a salesperson, freelance worker, or businessman, this handy calculator can help you in your earnings management process. Next time you secure a deal, rather than opening your calculator app, try the Commission Calculator India.