Blog Page 51

How Pradhan Mantri Kaushal Vikas Yojana (PMKVY) is Shaping India’s Skilled Workforce

0

Hey, have you ever felt stuck in a rut, wondering how to level up your skills and snag that dream job? Well, that’s where Pradhan Mantri Kaushal Vikas Yojana comes into play! Launched by the Indian government, this flagship scheme—often just called PMKVY—aims to turn everyday folks into skilled pros ready to tackle the job market. It’s not just about handing out certificates; it’s a real shot at empowerment, especially for young people who’ve dropped out of school or are hunting for better opportunities.

Picture this: In a country as vast and diverse as India, where millions of youths enter the workforce each year, skill gaps can feel like massive roadblocks. But PMKVY steps in like a trusty sidekick, offering free training that’s tailored to what industries actually need. From tech-savvy roles in AI to hands-on trades like plumbing or hospitality, it’s got something for everyone. And get this—by 2025, with PMKVY 4.0 in full swing, it’s focusing even more on futuristic skills like drones and green energy. Excited yet? This article’s gonna break it all down: the objectives that drive it, the perks that make it worthwhile, and who exactly can hop on board. We’ll chat about real-life impacts, toss in some tips, and wrap up with FAQs to clear up any confusion. Let’s dive in and see why Pradhan Mantri Kaushal Vikas Yojana is such a big deal!
Pradhan Mantri Kaushal Vikas Yojana-PMKVY

What is Pradhan Mantri Kaushal Vikas Yojana?

So, what’s the scoop on Pradhan Mantri Kaushal Vikas Yojana? At its core, it’s the government’s big push to skill up India’s youth, making sure they’re not left behind in a fast-changing world. Think of it as a nationwide training boot camp, but way more flexible and inclusive. Started back in 2015 under the Ministry of Skill Development and Entrepreneurship, PMKVY has evolved over the years, and now in its 4.0 version, it’s sharper than ever.

Back in the day, the first version focused on basic certification for millions. But as time rolled on, folks realized that just training wasn’t enough—people needed skills that matched real jobs. That’s why PMKVY 4.0, running from 2022 to 2026, amps up the ante with demand-driven courses. It’s all about aligning with what employers want, from local factories to global tech giants. And hey, it’s not stuck in the past; it adapts to new trends like Industry 4.0 or sustainable practices. Running through a network of training centers, sector skill councils, and even schools via Skill Hubs, Pradhan Mantri Kaushal Vikas Yojana reaches remote corners—think hilly areas or border regions where opportunities are scarce.

What makes it stand out? It’s free for most participants, with certifications that carry weight because they’re aligned with the National Skills Qualification Framework (NSQF). Plus, there’s this cool emphasis on lifelong learning—upskilling for those already working, or recognizing prior experience through RPL (Recognition of Prior Learning). It’s like the scheme says, “Hey, you’ve got skills? Let’s polish ’em up!” In 2025, with digital tools like the Skill India Digital portal, enrolling and tracking progress is a breeze. No more paperwork headaches; it’s all online, making it accessible even for folks in villages.

The Evolution of PMKVY Over the Years

Tracing back, PMKVY 1.0 was a whirlwind—training over a crore people in just a few years. But lessons learned, right? Version 2.0 brought in more quality checks, like mandatory assessments. Then 3.0 rode the pandemic wave, shifting to online modes and focusing on healthcare skills when the world needed ’em most. Now, Pradhan Mantri Kaushal Vikas Yojana 4.0? It’s the slickest yet, blending physical classes with blended learning, and throwing in extras like foreign language training for overseas jobs. That said, evolving with tech, it’s incorporating AI and VR for immersive training. Wow, imagine learning drone piloting virtually before hitting the field!

It’s not all smooth sailing, though. Early on, there were gripes about low placement rates, but recent tweaks—like tying training to job fairs (Rojgar Melas)—have bumped those numbers up. By prioritizing marginalized groups, like women or tribal communities, PMKVY ensures no one’s left out. In essence, it’s grown from a simple skilling program into a comprehensive ecosystem that’s boosting India’s global competitiveness.

Objectives of Pradhan Mantri Kaushal Vikas Yojana

Alright, let’s get to the heart of it—what’s Pradhan Mantri Kaushal Vikas Yojana really trying to achieve? The objectives aren’t just fancy words on paper; they’re practical goals that hit home for everyday Indians. First off, it’s all about creating a flexible skilling setup that’s quick to respond to market needs. In a world where jobs pop up and vanish overnight, PMKVY wants to equip youths with skills that stick around.

One big aim is boosting employability—making sure trained folks land jobs or start their own gigs. Through demand-driven training, it matches what industries crave, like skills in renewable energy or digital marketing. Another key objective? Inclusivity! PMKVY zeros in on underserved areas—think left-wing extremism zones or aspirational districts—bringing training right to their doorsteps. It’s like saying, “No matter where you are, we’ve got your back.”

Then there’s the push for lifelong learning. Not just for freshers, but for workers needing a refresh—upskilling in AI or reskilling from old trades to new ones. Pradhan Mantri Kaushal Vikas Yojana also eyes global opportunities, with courses in foreign languages or international standards. And don’t forget quality: Standardized curricula, trained trainers, and tech like Aadhaar-based attendance ensure it’s top-notch.

In 2025, objectives have sharpened on future-ready skills—Web 3.0, climate change stuff, you name it. It’s fostering entrepreneurship too, linking trainees to loans and mentorship. Overall, these goals weave together to build a skilled workforce that powers India’s economy. Pretty ambitious, huh?

Key Focus Areas in PMKVY 4.0

Diving deeper, PMKVY 4.0’s objectives spotlight three training pillars: Short-Term Training (STT) for newbies, RPL for experienced hands, and Special Projects for tricky cases. STT, lasting 300-600 hours, includes on-the-job training to make learning real-world ready. RPL? It’s a nod to prior know-how, with quick upskilling sessions. Special Projects tackle unique needs, like skilling jail inmates or rural artisans with modern twists.

Technology’s a biggie here—digitalization simplifies everything from enrollment to certification. Objectives also stress monitoring: CCTV in centers, virtual checks, and post-training tracking for a year. It’s all to ensure outcomes, not just outputs. And with a candidate-centric approach, PMKVY lets folks choose paths aligned with their dreams. That flexibility? A game-changer for dropouts or unemployed youth itching for a fresh start.

Benefits of Pradhan Mantri Kaushal Vikas Yojana

Man, the benefits of jumping into Pradhan Mantri Kaushal Vikas Yojana are endless—it’s like opening a treasure chest for your career! For starters, it’s completely free: Training, assessments, even certification—no hidden costs. You get an NSQF-aligned certificate that’s recognized nationwide, often graded A or B based on your performance. Plus, there’s a one-year accidental insurance policy thrown in, just in case.

But wait, there’s more! Participants snag an induction kit—a T-shirt, bag, handbook—to kick things off right. For women, PwDs, or those in tough spots like border areas, extra perks like boarding, lodging, or transport make it doable. And after? You’re tracked for a year, connected to job placements, apprenticeships, or even entrepreneurship loans. It’s not just training; it’s a launchpad.

On a bigger scale, PMKVY boosts the economy by filling skill gaps, reducing unemployment, and sparking innovation. Industries get ready talent, while society sees more empowered folks, especially from marginalized groups. In 2025, with focus on green jobs, it’s even helping combat climate change. Talk about win-win!

Benefits for Individuals: A Personal Boost

From a personal angle, enrolling in Pradhan Mantri Kaushal Vikas Yojana can flip your life around. Imagine a school dropout turning into a certified electrician—sudden confidence boost! Skills like digital literacy or soft skills make you versatile, opening doors to better-paying gigs. And with OJT, you gain real experience, not just theory.

For those with prior know-how, RPL certifies what you already rock, plus ups your game with short sessions. Women and PwDs get tailored support, like conveyance allowances, making participation easier. Heck, even one free re-assessment if you slip up first time. Graduates often land jobs faster, with many reporting higher wages. It’s empowering, giving you that “I did it!” moment.

Societal and Economic Perks

Zooming out, the benefits ripple through society. By skilling millions, PMKVY cuts down youth unemployment, curbing social issues like frustration or migration woes. It promotes equality—more women in workforce, tribals in modern roles. Economically, a skilled India attracts investments, fuels growth in sectors like manufacturing or IT.

In tough times, like post-pandemic recovery, PMKVY’s adaptability shines. It’s building a resilient economy, ready for disruptions. And with international skilling, remittances could soar. Overall, it’s knitting a stronger social fabric, one skilled person at a time.

Eligibility Criteria for Pradhan Mantri Kaushal Vikas Yojana

Wondering if you’re eligible for Pradhan Mantri Kaushal Vikas Yojana? It’s pretty straightforward, but let’s break it down. First, you gotta be an Indian national with a valid Aadhaar— that’s the baseline. Age-wise, for Short-Term Training and Special Projects, it’s 15-45 years old. For RPL, it’s broader: 18-59, perfect for mid-career folks.

But it’s not one-size-fits-all. Each job role has specifics—like education level or basic skills needed. Unemployed youth, school/college dropouts, or those seeking upskilling get priority. Marginalized groups? Absolutely—SC, ST, women, PwDs, transgenders, even jail inmates via Special Projects.

Can’t reenroll in the same role, but after six months, you can try a different or higher one—up to two total. De-duplication via digital portals ensures fairness. In special areas like LWE districts, flexibilities apply, like alternative IDs. Bottom line: If you’re eager to learn and fit the bill, PMKVY’s doors are open!

Special Considerations for Vulnerable Groups

For vulnerable folks, eligibility bends to include more. Women in non-residential training get conveyance support, encouraging participation. PwDs can access assistive devices worth up to Rs. 5,000. In remote spots, residential options make it feasible. It’s all about removing barriers, ensuring everyone gets a fair shot.

How to Apply for PMKVY

Applying for Pradhan Mantri Kaushal Vikas Yojana? Easy peasy! Head to the Skill India Digital portal (skillindia.gov.in) or app. Register with your Aadhaar, pick a course and center nearby. Centers often hold counseling sessions to guide you.

Documents? Aadhaar, maybe proof of age or prior experience for RPL. Once enrolled, attend classes—70% attendance mandatory via biometric tracking. Finish training, ace the assessment, and boom—certified! In 2025, it’s all digitized, so no long queues.

  • Step 1: Visit the portal and search for courses.
  • Step 2: Fill in details and choose a training provider.
  • Step 3: Attend orientation and start learning.
  • Step 4: Get assessed and certified.

Pro tip: Check for Rojgar Melas post-training for job leads.

Success Stories from PMKVY Participants

Nothing beats real stories to show PMKVY’s magic. Take Raj, a 22-year-old from a Rajasthan village. Dropped out after 10th grade, he joined Pradhan Mantri Kaushal Vikas Yojana for solar technician training. Six months later? He’s installing panels in his district, earning double what he did as a laborer. “It changed my life—now I’m contributing to green energy!” he exclaims.

Or Priya, a single mom from Bihar. Through RPL in tailoring, she upskilled with digital design tools. Now running a small boutique, she’s independent. “PMKVY gave me wings,” she says. Then there’s Arun from a tribal area in Odisha. Special Project in drone tech? Landed him a gig in agriculture surveying. These tales, dotted across India, prove PMKVY’s impact—turning dreams into reality.

Imaginative yet grounded, picture a young artist from Kashmir blending traditional crafts with e-commerce skills via PMKVY. Selling online globally now! Or a PwD mechanic from Tamil Nadu, empowered with adaptive tools. Such stories inspire, showing how the scheme sparks innovation and resilience.

Challenges and Ways Forward

Sure, Pradhan Mantri Kaushal Vikas Yojana isn’t perfect. Challenges like uneven placement rates persist—some grads struggle finding jobs. Infrastructure in remote areas? Still spotty. Awareness is another hurdle; many eligible folks don’t know about it.

That said, improvements are underway. More industry tie-ups for guaranteed placements, stricter monitoring to curb fakes, and tech integrations for better reach. In 2025, with budget boosts, expect smoother sailing. Feedback loops from participants help tweak things, ensuring PMKVY stays relevant.

FAQs

What is the main goal of Pradhan Mantri Kaushal Vikas Yojana? It’s to skill up youths for better jobs, focusing on demand-driven training.

Who can apply for PMKVY? Indian nationals aged 15-45 for most, with Aadhaar; priorities for dropouts and marginalized groups.

Are there any fees? Nope, it’s free—including training and certification!

How long are the courses? STT: 300-600 hours; RPL: 30-132 hours.

What if I fail the assessment? One free re-attempt—give it another shot!

Can I get a job after? Many do, via placements and job fairs linked to the scheme.

Is online training available? Blended modes yes, with approval; physical is main.

How do I check my certificate? Via DigiLocker—it’s digital and QR-coded.

Conclusion

Wrapping it up, Pradhan Mantri Kaushal Vikas Yojana stands tall as a beacon of hope in India’s skilling landscape. From its clear objectives of fostering employability and inclusivity to the tangible benefits like free certs and support, it’s empowering millions. Eligibility’s broad, application simple—why not give it a go? Despite bumps, its evolution shows commitment to a skilled India. As we hit 2025, PMKVY’s not just a scheme; it’s a movement unlocking potentials. So, if you’re dreaming big, dive in—your future self will thank you!
Mutual Fund Fact Sheet Meaning & Importance

Ever wondered what that colorful PDF your mutual fund company emails you every month actually means? That, my friend, is the Mutual Fund Fact Sheet — the financial world’s version of a report card. It’s not just a bunch of numbers and graphs; it’s a treasure map for investors who want to understand how their money is performing.

In India, where mutual funds are gaining massive popularity among both beginners and seasoned investors, knowing how to interpret this document can give you a serious edge. Whether you’re sipping chai on your balcony while checking your SIP returns or analyzing fund performance for the long term, the Mutual Fund Fact Sheet helps you see the bigger picture.

In this detailed guide, we’ll decode everything — from what a fact sheet is, why it matters, and how to read one, to the metrics that can help you decide whether to stay invested or switch to another fund.

So, let’s dive in and unravel the mystery behind the Mutual Fund Fact Sheet in India!

Mutual Fund Fact Sheet

What Is a Mutual Fund Fact Sheet?

A Mutual Fund Fact Sheet is a monthly or quarterly report published by Asset Management Companies (AMCs). It contains vital details about each mutual fund scheme — its performance, portfolio composition, risk level, and fund manager’s commentary.

Think of it as your fund’s progress card. It tells you:

  • How your fund is performing compared to others.
  • What sectors or companies it’s investing in.
  • How risky or stable it is.
  • Who’s managing your money and how they’ve done historically.

In short, it’s transparency served on a silver platter!

Why Is the Mutual Fund Fact Sheet Important?

Here’s why investors can’t ignore it:

  1. Performance Insight: It helps you track your fund’s consistency and growth.
  2. Transparency: You get a clear idea of where your money is going.
  3. Comparison Tool: It allows you to compare similar funds side by side.
  4. Decision-Making Aid: It helps in deciding whether to continue investing or switch.
  5. Risk Awareness: It shows how exposed your fund is to different market sectors.

Without the fact sheet, investing blindly in mutual funds would be like driving with your headlights off!

Structure of a Mutual Fund Fact Sheet

Every AMC in India — from HDFC Mutual Fund to SBI or ICICI Prudential — follows a fairly standardized format. Let’s break it down.

  1. Fund Overview Section

This section covers:

  • Fund Name & Category: Equity, Debt, Hybrid, etc.
  • Launch Date: When the fund started.
  • Fund Manager: Who’s managing it and their experience.
  • Benchmark Index: For example, NIFTY 50 or Sensex — used to measure performance.

You’ll often see something like:

HDFC Equity Fund – Large Cap | Benchmark: NIFTY 100 TRI

This sets the tone for what you’re about to read.

  1. Investment Objective

This part tells you why the fund exists — its primary goal.
For example:

“To generate long-term capital appreciation by investing predominantly in large-cap companies.”

Sounds simple, but it’s essential. It tells you whether the fund’s goals align with your financial objectives.

  1. Performance Summary

This section is the real deal. It showcases how the fund has performed over different time periods — 1 month, 3 months, 1 year, 3 years, 5 years, and since inception.

Typically, it includes:

  • Absolute Returns (%)
  • Annualized Returns (%)
  • Benchmark Comparison
  • Peer Comparison

A quick glance can show whether your fund consistently beats the market — or if it’s lagging behind.

  1. Portfolio Composition

Here’s where things get interesting! This section reveals where your money is actually invested.

  • Top 10 Holdings: Lists the major stocks or bonds the fund holds.
  • Sector Allocation: Shows the percentage invested in different industries like banking, IT, FMCG, etc.
  • Asset Allocation: Displays the fund’s investment mix (equity, debt, cash, etc.).

For instance, a large-cap fund might look like this:

  • HDFC Bank – 9.5%
  • Infosys – 7.8%
  • ICICI Bank – 6.3%
  • Reliance Industries – 6.1%

This section helps you understand if your fund is diversified or overly dependent on a few companies.

  1. Risk Measures and Ratios

These figures can look intimidating at first, but don’t worry — we’ll break them down.

Common metrics include:

  • Standard Deviation: Measures volatility; higher = riskier.
  • Beta: Compares fund movement to the market; if >1, it’s more volatile.
  • Sharpe Ratio: Measures risk-adjusted returns; higher = better.
  • Alpha: Indicates how much extra return the fund manager generates beyond the benchmark.

These numbers help you judge whether your returns justify the risk you’re taking.

  1. Expense Ratio and Exit Load

These two can eat into your returns if you’re not careful!

  • Expense Ratio: The annual fee the fund charges to manage your investment. Lower is generally better.
  • Exit Load: A small penalty for withdrawing your investment before a specific time frame.

Smart investors always check these before investing!

  1. Fund Manager’s Commentary

This is often the most human part of the Mutual Fund Fact Sheet. The fund manager shares insights on:

  • Market conditions.
  • Economic outlook.
  • Reasons for portfolio changes.

It gives investors a peek into the fund’s strategy — whether the manager is being cautious, optimistic, or aggressive.

  1. Other Disclosures

At the end, you’ll find:

  • Riskometer (showing risk level: low to very high).
  • Total AUM (Assets Under Management).
  • Minimum investment details.
  • SIP options.

This section ensures full compliance with SEBI’s disclosure norms.

How to Read a Mutual Fund Fact Sheet in India

Now that you know what’s inside, let’s talk about how to interpret it like a pro.

Step 1: Check the Fund Objective

Ask yourself — does it match your goals? If you’re saving for retirement, a small-cap fund might be too risky.

Step 2: Look at the Returns

Compare the fund’s performance to its benchmark. A good fund consistently beats its benchmark over the long term.

Step 3: Examine Risk Metrics

If the fund’s volatility (standard deviation) is high but returns aren’t compensating, it may not be worth the stress!

Step 4: Analyze Portfolio Holdings

Is your fund diversified across sectors and stocks? Too much exposure to one company or industry can be risky.

Step 5: Study the Expense Ratio

Even a small difference can compound significantly over years.

Step 6: Read the Commentary

Understand the fund manager’s perspective — it often hints at future strategy.

By following these steps, you’ll be reading a Mutual Fund Fact Sheet like a seasoned investor!

Common Jargon You’ll Encounter

To make things easier, here are some common terms and their plain-English meanings:

Term Meaning
NAV Net Asset Value – the per-unit value of your mutual fund
CAGR Compound Annual Growth Rate – shows growth over time
AUM Assets Under Management – total money handled by the fund
Benchmark The index against which performance is measured
Diversification Spreading investments across various assets to reduce risk
Riskometer Indicates how risky the fund is (Low, Moderate, High, etc.)

The Role of SEBI and AMFI in Mutual Fund Fact Sheets

In India, mutual fund transparency is ensured by two key regulators:

  • SEBI (Securities and Exchange Board of India): Sets the rules for disclosure, format, and reporting.
  • AMFI (Association of Mutual Funds in India): Ensures uniformity across all AMCs and publishes consolidated data monthly.

This means whether you invest in Axis, HDFC, or Nippon India Mutual Fund, their fact sheets follow the same broad format — making it easy to compare.

How Often Is a Mutual Fund Fact Sheet Published?

Usually, every month.

AMCs release it around the first week of the month for the previous month’s performance. Some funds also publish quarterly or half-yearly updates for in-depth analysis.

Keeping an eye on these ensures you’re always up to date with your fund’s progress.

Fact Sheets in the Age of Apps

Gone are the days when investors had to download bulky PDFs.

Today, you can:

  • Access interactive dashboards through AMC websites.
  • Use apps like Groww, Kuvera, or ET Money to view fact sheet data.
  • Get AI-powered insights based on fact sheet analysis.

Technology has made tracking mutual funds faster, easier, and far more transparent.

Why You Shouldn’t Ignore the Mutual Fund Fact Sheet

Here’s the thing — even experienced investors sometimes overlook this document. But doing so can cost you!

Ignoring the Mutual Fund Fact Sheet means:

  • You might miss red flags (like increasing volatility).
  • You won’t notice changes in fund strategy or holdings.
  • You could stay invested in underperforming schemes.

Simply put, your fact sheet is your financial health report — ignoring it is like skipping a medical checkup.

Reading a Real Fact Sheet

Let’s take an example (simplified):

Fund: ABC Large Cap Fund
Benchmark: NIFTY 100 TRI
1-Year Return: 14.2%
3-Year Return: 17.5% CAGR
Expense Ratio: 1.2%
Top Holdings: Reliance (7%), HDFC Bank (6.5%), Infosys (6%), ICICI Bank (5.8%)
Sharpe Ratio: 1.3

Interpretation:

  • Performance beats benchmark → ✅ Good.
  • Reasonable diversification → ✅ Safe.
  • Expense ratio slightly high → ⚠️ Watch out.
  • Consistent returns → 👍 Reliable choice.

This is exactly how you can use a Mutual Fund Fact Sheet in India to make smart decisions.

Expert Tips to Make the Most of a Mutual Fund Fact Sheet

  1. Look Beyond Short-Term Returns: Focus on 3- and 5-year performance.
  2. Compare Similar Funds: Use fact sheets to identify outperformers within a category.
  3. Track Fund Manager Changes: A new manager can shift strategy.
  4. Keep an Eye on Portfolio Drift: Watch if a large-cap fund starts investing heavily in mid-caps.
  5. Stay Consistent: Review fact sheets regularly, not just once a year.

Common Mistakes Investors Make

  • Focusing only on past returns — ignoring risk.
  • Not reading the commentary.
  • Ignoring expense ratios.
  • Comparing apples to oranges (like equity vs hybrid funds).
  • Not checking consistency across time periods.

Avoiding these pitfalls can dramatically improve your investment outcomes.

FAQs

  1. What exactly is a Mutual Fund Fact Sheet?

It’s a monthly report from the AMC that gives you complete details about your mutual fund’s performance, holdings, and risk profile.

  1. Where can I find my fund’s fact sheet?

You can download it from your AMC’s website or through financial platforms like AMFI, Moneycontrol, or Groww.

  1. How often is it updated?

Usually, every month — typically released within the first week.

  1. Can I rely solely on a fact sheet before investing?

It’s a great starting point, but combine it with other research like fund house reputation and long-term performance.

  1. Why do some fact sheets look so technical?

Because they’re designed for transparency. However, once you get used to the terms, they’re quite easy to understand!

  1. What should I focus on as a beginner?

Check the fund’s objective, risk level, past performance, and expense ratio — those four will tell you most of what you need.

Conclusion

At the end of the day, investing is all about informed choices. And the Mutual Fund Fact Sheet in India is your best friend on that journey.

It’s not just a dull data sheet — it’s a window into how your money is growing, who’s handling it, and what strategy drives it forward. Reading it regularly empowers you to make smarter, more confident decisions — and stay one step ahead of the market.

So next time that email from your AMC hits your inbox, don’t skip it. Open it, read it, and let the numbers tell their story. Because when it comes to wealth creation, knowledge isn’t just power — it’s profit.

High Frequency Trading: Meaning & Key Features

Ever wondered how some traders make money in milliseconds while others spend hours analyzing charts? Welcome to the lightning-fast world of High Frequency Trading (HFT) — a domain where speed isn’t just an advantage; it’s the whole game!

It’s like the Formula One of the stock market, where everything happens at breakneck speed. In this article, we’re gonna unpack what high frequency trading is all about, digging into its meaning, those quirky features that make it tick, and especially its role right here in India. You know, India’s markets are booming, and high frequency trading is playing a bigger part than ever. Whether you’re a newbie investor or just curious about how Wall Street – or should I say, Dalal Street – works these days, stick around. We’ll keep it simple, throw in some real-world examples, and even tackle those burning questions in an FAQ section. By the end, you’ll feel like you’ve got the inside scoop on this high-stakes game. Let’s dive in!

High Frequency Trading

What Exactly Is High Frequency Trading?

So, first things first: what is high frequency trading, anyway? At its core, high frequency trading – often just called HFT – is a type of algorithmic trading that uses super-fast computers to buy and sell stocks, bonds, or other financial stuff in fractions of a second. We’re talking milliseconds here, folks! Imagine you’re at a bustling market, but instead of haggling over prices, your computer is scanning the scene, spotting tiny price differences, and jumping on them before anyone else can even blink.

High frequency trading isn’t some newfangled idea that popped up overnight. It started gaining traction back in the late ’90s and early 2000s, thanks to advances in technology. Traders realized they could automate the whole process, cutting out the human element that’s prone to errors or, you know, needing coffee breaks. In essence, it’s all about exploiting those fleeting opportunities in the market that regular folks like you and me wouldn’t even notice.

But here’s where it gets interesting: high frequency trading relies on complex algorithms – think of them as secret recipes – that analyze massive amounts of data in real time. These algos can predict price movements based on patterns, news flashes, or even social media buzz. Wow, talk about being ahead of the curve! And while it’s mostly used by big institutions like hedge funds or banks, it’s trickling down to smaller players too, especially in places like India where tech is king.

Dangling in the background, though, is the debate about fairness. Some say high frequency trading levels the playing field by making markets more efficient, while others argue it gives an unfair edge to those with the fanciest tech. Either way, understanding its meaning is key to grasping why it’s such a hot topic today.

The Standout Features of High Frequency Trading

Alright, now that we’ve got the basics down, let’s zoom in on what makes high frequency trading so unique. It’s not just about speed; there are a bunch of features that set it apart from your grandpa’s buy-and-hold strategy. We’ll break ’em down one by one, using some bullet points to keep things snappy.

Speed: The Heartbeat of High Frequency Trading

Speed is the name of the game in high frequency trading – no exaggeration! These systems can execute thousands of trades per second, thanks to colocated servers parked right next to exchange data centers. Why? To shave off those precious microseconds in data travel time. It’s kinda like having a front-row seat at a concert versus watching from the nosebleeds.

  • Ultra-low latency: We’re talking about delays measured in nanoseconds. Any hiccup, and you’re out of the race.
  • High turnover rates: HFT firms might hold positions for mere seconds, flipping assets faster than a pancake on a griddle.
  • Automation overload: Everything’s on autopilot, with algorithms making split-second decisions without human input.

Transitional phrases aside, this speed isn’t just for show; it allows traders to capitalize on arbitrage opportunities, where they buy low in one market and sell high in another almost instantly.

Advanced Algorithms and Data Crunching

Another killer feature? The brains behind the operation: sophisticated algorithms. These aren’t your basic math equations; they’re powered by AI and machine learning, sifting through terabytes of data. High frequency trading thrives on this, predicting trends before they even fully form.

Picture this: an algo spots a stock dipping slightly due to a rumor. Bam! It buys in, then sells when the price rebounds moments later. Features like pattern recognition and sentiment analysis make it possible. And don’t forget big data – from market feeds to satellite imagery tracking crop yields for commodity trades. It’s mind-blowing how interconnected it all is!

Liquidity Provision and Market Making

High frequency trading often acts as a market maker, providing liquidity that keeps the wheels turning smoothly. What does that mean? These traders are always ready to buy or sell, narrowing the bid-ask spread and making it easier for everyone else to trade.

  • Tight spreads: Smaller differences between buy and sell prices mean lower costs for investors.
  • Volume boost: HFT accounts for a huge chunk of daily trading volume – sometimes over 50% in major markets.
  • Risk management: Built-in safeguards like stop-loss mechanisms help mitigate big losses, though flash crashes can still happen, as we’ve seen.

However, critics point out that this liquidity can vanish in turbulent times, leaving markets in a lurch. Still, it’s a double-edged sword worth noting.

Co-location and Technological Edge

Co-location is a fancy term for placing your servers super close to the exchange’s. It’s a feature that’s almost mandatory in high frequency trading circles. Why bother? To reduce latency, of course! Firms pay big bucks for this privilege, giving them a leg up.

Moreover, the hardware involved is top-notch: fiber-optic cables, microwave transmissions – even laser beams for data transfer. Exclamation point: it’s straight out of a sci-fi novel! This tech edge ensures HFT stays ahead, but it also raises questions about accessibility for smaller traders.

How High Frequency Trading Operates 

Curious about the nuts and bolts? High frequency trading doesn’t just happen by magic. It starts with strategy development, where quants – those math whizzes – design algorithms. Then, it’s all about execution: connecting to exchanges via direct market access (DMA), firing off orders at lightning speed.

Take an example: suppose there’s a tiny discrepancy in gold prices between Mumbai and New York. An HFT system detects it, buys in the cheaper market, sells in the pricier one, and pockets the difference. All in under a second! But it’s not without risks – network glitches or regulatory changes can throw a wrench in the works.

Informally speaking, it’s like playing a video game on expert mode: one wrong move, and you’re toast. Yet, the rewards can be massive, with firms raking in billions.

The Evolving Role of High Frequency Trading in India

Now, let’s shift gears to India, where high frequency trading is making waves. India’s stock markets, like the NSE and BSE, have embraced tech big time, and HFT is right in the mix. But what’s its specific role here? Let’s explore.

A Brief History in the Indian Context

High frequency trading hit Indian shores around 2010, when co-location facilities were introduced. Back then, it was mostly foreign institutional investors (FIIs) dipping their toes in. Fast forward to today – October 2025, mind you – and local players are jumping on board too. The NSE alone sees HFT contributing to about 40-50% of trades on busy days.

It’s grown hand-in-hand with India’s digital boom. Think about it: with smartphones everywhere and apps like Zerodha making trading accessible, high frequency trading fits right in, automating what used to be manual drudgery.

Regulatory Landscape and Challenges

Ah, regulations – the necessary evil! In India, SEBI (Securities and Exchange Board of India) keeps a watchful eye on high frequency trading. They’ve got rules on co-location to ensure fairness, like randomizing server allocations to prevent front-running.

But challenges abound. Flash crashes, like the one in 2012 that spooked everyone, led to tighter controls. Plus, there’s the issue of market manipulation – some worry HFT could spoof orders, faking interest to move prices. SEBI’s been cracking down, imposing speed bumps and minimum resting times for orders.

Transitionally, though, these regs are evolving. In 2024, new guidelines boosted transparency, making high frequency trading safer for all.

Benefits for the Indian Economy

On the flip side, high frequency trading brings plenty of perks to India. For starters, it enhances market efficiency. Prices reflect info faster, helping investors make better decisions.

  • Increased liquidity: More trades mean smoother operations, especially in volatile sectors like tech or pharma.
  • Lower transaction costs: Tighter spreads save money for retail traders – that’s you and me!
  • Job creation: The tech behind HFT spurs demand for coders, data scientists, and analysts in cities like Bangalore and Mumbai.

Moreover, it attracts foreign investment, boosting the rupee and overall growth. Imagine India’s markets becoming as liquid as New York’s – we’re getting there!

Drawbacks and Ethical Concerns in India

But let’s not sugarcoat it: high frequency trading isn’t all sunshine. In India, where inequality’s a big issue, HFT can widen the gap between big firms and small investors. Those without fancy tech get left in the dust.

There’s also the risk of systemic failures. A glitch in one HFT system could ripple through the market, causing panic. And ethically? Questions linger about whether it’s truly fair play or just a rich man’s game.

Dangling modifiers aside, addressing these through education and inclusive policies is crucial.

Pros and Cons of High Frequency Trading 

To sum up the features and role, here’s a balanced look with lists.

Pros:

  1. Boosts efficiency and liquidity.
  2. Reduces costs for everyone.
  3. Drives innovation in finance tech.
  4. Helps in price discovery.

Cons:

  1. Potential for market instability.
  2. Unfair advantage for tech-heavy players.
  3. Regulatory headaches.
  4. Ethical dilemmas over manipulation.

It’s a mixed bag, but in India, the pros seem to outweigh the cons as we adapt.

High Frequency Trading vs. Traditional Trading

Aspect High Frequency Trading (HFT) Traditional Trading
Speed Microseconds Minutes to hours
Decision Maker Algorithms Humans
Holding Period Seconds or less Days to years
Capital Requirement Very high Moderate to low
Objective Exploit short-term inefficiencies Long-term investment growth
Technology Advanced computing, AI Basic trading platforms
Risk Level High operational risk Market-driven risk

FAQs 

Got questions? We’ve got answers! Here are some common ones.

What is the main goal of high frequency trading?

The goal? To profit from tiny, short-lived market inefficiencies using speed and smarts.

Is high frequency trading legal in India?

Absolutely! But it’s heavily regulated by SEBI to keep things fair.

Can individual investors do high frequency trading?

Sure, but you’ll need serious tech and know-how. It’s not for the faint-hearted!

How has high frequency trading changed Indian markets?

It’s made them faster, more liquid, and globally competitive – a real game-changer.

What risks come with high frequency trading?

Flash crashes, manipulation, and tech failures top the list. Stay vigilant!

Conclusion

Wrapping it up, high frequency trading is more than just a buzzword – it’s reshaping finance worldwide, and India’s no exception. From its meaning as ultra-fast algo trading to features like blazing speed and smart algorithms, and its role in boosting liquidity while posing challenges, we’ve covered the gamut. Sure, there are hurdles, but with smart regs and innovation, it’s poised to thrive. If you’re dipping into investing, keep an eye on this space – it might just be the future. Thanks for reading; now go out there and trade wisely!

Understanding the Settlement Cycle in Stock Markets

Have you ever placed an order to buy some shares online, only to check your account right away and see nothing there? It’s frustrating, right? You might think the deal happened instantly, but that’s not how it works. There’s a behind-the-scenes process called the settlement cycle that makes sure everything transfers smoothly between the buyer and the seller. In India, we’ve moved to a super-fast system called T+1, where things wrap up in just one day. This keeps trades secure and quick. But why does this matter to everyday investors like you or me? Let’s dive in and break it down step by step. We’ll look at what settlement really means, how it happens, the different timelines like T+1 or T+2, who’s involved, how it’s changed over time in India, the upsides, the potential downsides, and more. By the end, you’ll have a clear picture of this key part of stock trading.

Imagine you’re at a local market buying fruits from a vendor. You pick the apples, agree on the price, and hand over the cash. The vendor gives you the bag right then. That’s instant settlement. But in the stock market, it’s more like ordering online – you pay, but the delivery takes a bit because the system checks everything to avoid mix-ups. That’s the settlement cycle in a nutshell. It ensures no one gets cheated and that the market runs fairly for everyone.

Settlement Cycle

Understanding Settlement Cycle in Simple Terms

Settlement is basically the final handover after a stock trade. When you buy shares, you’re not just clicking a button; you’re entering a deal where you get ownership of part of a company, and the seller gets your money. But it doesn’t happen on the spot because there are checks to make sure both sides can deliver what they promised.

Think of it like this: You agree to buy a used bike from a friend. You shake hands on the price (that’s the trade), but then you need to transfer the money, get the papers signed, and take the bike home (that’s settlement). In stocks, this handover involves electronic shares moving to your digital account, called a Demat account, and money going to the seller’s bank.

Why the delay? It’s to protect everyone. If the seller doesn’t have the shares or the buyer doesn’t have the funds, the system catches it early. Without settlement, trades could fall apart, leading to chaos. For instance, during busy market days, thousands of trades happen every minute. Settlement organizes all that mess into a clean transfer.

In real life, settlement affects how you plan your investments. If you’re a short-term trader, knowing when your money or shares arrive helps you decide your next move. Say you sell shares to buy something else – if settlement is slow, your cash is tied up, and you might miss a good opportunity.

Step-by-Step: How the Process Works from Trade to Settlement

The journey from placing an order to seeing shares in your account has a few clear steps. Let’s walk through them one by one, with examples to make it real.

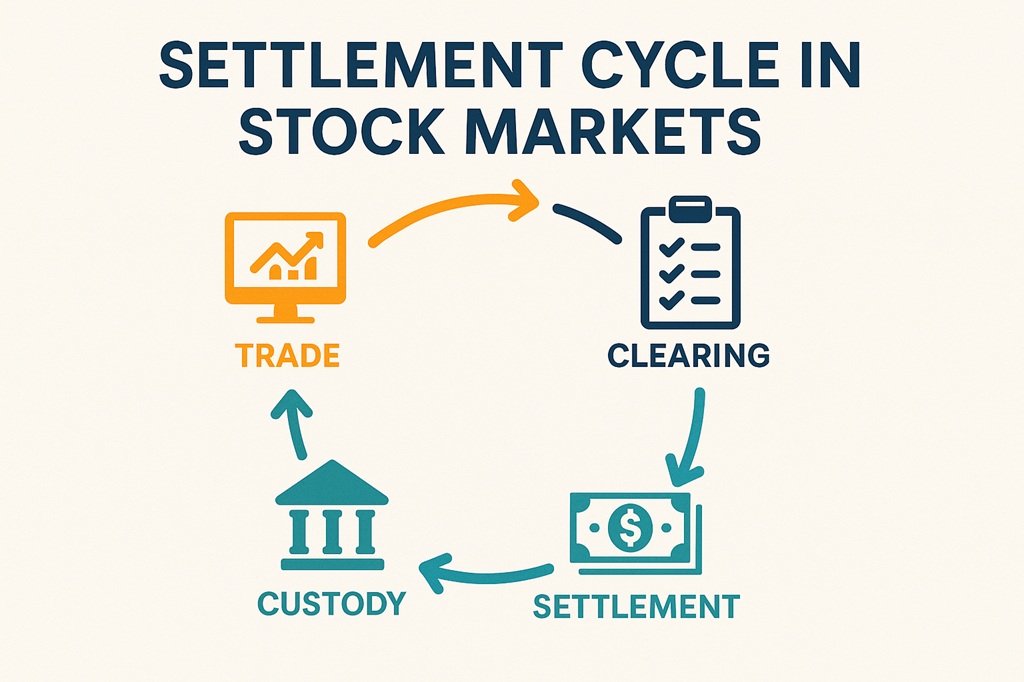
First comes Trade Execution. This is when your buy or sell order hits the stock exchange, like the National Stock Exchange (NSE) or Bombay Stock Exchange (BSE). The system matches your order with someone on the other side. For example, if you’re buying 100 shares of Reliance Industries at Rs 2,500 each, the exchange finds a seller offering at that price or better. It’s like an auction where buyers and sellers meet digitally. This happens in seconds during trading hours, usually 9:15 AM to 3:30 PM in India.

Next is Clearing. Here, a middleman called the clearing corporation steps in. Think of them as the referee. In India, it’s usually the National Securities Clearing Corporation Limited (NSCCL) for NSE or Indian Clearing Corporation Limited (ICCL) for BSE. They calculate what everyone owes. If you bought those Reliance shares, they check if you have enough money in your trading account. For the seller, they verify the shares are in their Demat. This step prevents defaults. An example: During the 2008 financial crisis, clearing helped spot risky trades early, saving markets from bigger crashes.

Then there’s Settlement. This is the actual transfer. Shares move from the seller’s Demat to yours via depositories like NSDL or CDSL, and money flows through banks. Under T+1, if you trade on Monday, everything settles by Tuesday end. Picture this: You buy shares on a Friday. Monday is a holiday? Settlement shifts to Tuesday. It’s all about business days, not weekends or holidays.

Finally, Custodial Confirmation. This is the wrap-up where your broker and depository confirm everything’s in place. Your app or statement shows the update. It’s like getting a receipt after delivery. In practice, if there’s a glitch, like insufficient funds, the exchange might penalize you or auction shares to cover it.

A real-world example: Suppose Raj, a Mumbai trader, buys 50 shares of HDFC Bank on Wednesday (T day). Under T+1, by Thursday evening, the shares are in his Demat, and the seller gets paid. If Raj sells them immediately on Thursday, he can use the cash for something else on Friday. This speed helps active traders flip investments quickly.

Key Components of the Settlement Cycle

Breaking it down further, the settlement cycle involves a few key players and steps. You’ve got the buyer, seller, brokers, clearing corporations (like NSE Clearing Ltd.), and depositories (NSDL or CDSL). They all work in sync, kinda like a well-oiled machine.

  • Trade Execution (T Day): This is when the magic starts – you place your order, it matches with a seller, and boom, trade done.
  • Clearing: Here, obligations are figured out. Who owes what to whom? Netting happens to simplify things.
  • Settlement: The big finale – funds and securities move.

Breaking Down T, T+1, T+2, and Beyond

These “T” terms might sound technical, but they’re just timelines. “T” stands for Trade Day – the day the deal is struck.

T (Trade Date): This is ground zero. Your order executes, but nothing moves yet. All details go to the clearing house for processing. For instance, if you trade on October 9, 2025, that’s T. No shares or money change hands; it’s just recorded.

T+1 Settlement Cycle: India’s current standard, fully rolled out in January 2023. Settlement happens one business day later. Buy on Monday? Get shares Tuesday. This cut down wait times from older systems. Why the change? Faster cycles mean less risk if markets drop suddenly. Example: During COVID market swings in 2020, T+1 would have let investors access cash quicker to buy dips.

T+2 Settlement Cycle: The old way, used until 2023. Two days after trade. Trade Monday, settle Wednesday. It worked, but had issues like higher default risks. If a broker went bust in those two days, trades could fail. Many countries like the US still use T+1 or T+2, but India led by switching early. Drawback: Slower liquidity. Say you sell shares for an emergency – waiting two days hurts.

T+0 (Same-Day Settlement): The future is here, sort of. SEBI started a pilot in March 2024 with 25 stocks. By April 2025, it expanded to 500 more securities, and it’s optional alongside T+1. As of October 2025, it’s voluntary for select stocks, with plans to include top 500 gradually. Trades in the morning settle by evening. Imagine buying at 10 AM and having shares ready by 4 PM to sell if needed. It’s great for high-frequency traders but requires top-notch tech. Recent SEBI updates in October 2025 tightened rules for block deals in T+0, like minimum Rs 25 crore trades and specific windows (8:45-9:00 AM and 2:05-2:20 PM), to boost transparency.

Why these shifts? Shorter cycles reduce “settlement risk” – the chance something goes wrong between trade and handover. In volatile markets, like during the 2022 Ukraine crisis, quick settlements protected investors from big losses.

Key Players in the Settlement Game

Settlement isn’t a solo act; it’s a team effort. Here’s a closer look at each player, with examples of their roles.

  • Investor: That’s you! You start it by placing orders via an app or broker. You need funds ready for buys or shares for sells. Example: If you’re short on cash, your trade might get rejected, like trying to buy a phone without money in your wallet.
  • Broker: Your go-between, like Zerodha or Groww. They execute orders and handle paperwork. They ensure you comply with rules. For instance, if you forget to link your bank, the broker flags it.
  • Stock Exchange (NSE/BSE): The marketplace. They match orders in real-time. During IPO rushes, like the LIC listing in 2022, exchanges handle millions of trades without hiccups.
  • Clearing Corporation: The risk managers. They guarantee trades even if one side fails. NSCCL, for example, uses margins (like deposits) to cover defaults. In 2019, a broker default was handled smoothly thanks to them.
  • Depository (NSDL/CDSL): Digital vaults for shares. They transfer electronically, no paper. When you convert physical shares to Demat, they store them safely. Example: During Demat booms post-2020, CDSL added millions of accounts.
  • Banks/Payment Gateways: Handle money moves. UPI or NEFT ensures quick transfers. If a bank delays, settlement could slip, but rules penalize that.

All these work like a relay race, passing the baton smoothly.

How India’s Settlement Cycle Evolved Over Time

India’s stock market wasn’t always this slick. It’s come a long way from paper chaos to digital speed.

Back in the 1980s and early 1990s, everything was physical. Shares were paper certificates, mailed around. Settlements took weeks – T+14 was normal! Payments by cheque added delays. The 1992 Harshad Mehta scam exposed flaws: Fake bank receipts led to a crash. This pushed reforms.

By 2001, SEBI introduced T+5: Settle in five days. It cut risks but was still slow. Then T+3 in 2002 sped things up, building trust after the dot-com bust.

In 2003, T+2 arrived, aligning with global norms. Brokers got cash faster, boosting trading volumes. But the real game-changer was Demat in the late 1990s. NSDL launched in 1996, CDSL in 1999. No more lost certificates – everything electronic. This slashed fraud and sped settlements.

Post-2008 crisis, tech upgrades like online platforms made things seamless. By 2021, SEBI eyed T+1 to lead globally. Phased in from 2022: Small stocks first, all by 2023. It reduced locked funds by 50%, per SEBI data. Example: In 2023 bull run, T+1 let investors rotate money quickly into rising stocks like Adani.

Now, T+0 is rolling out. Pilot in 2024, expanded in 2025 to over 500 stocks. It’s optional, but SEBI’s October 2025 block deal tweaks show commitment to efficiency. Compared to the US (T+1 since 2024) or Europe (T+2), India’s ahead. This evolution turned a clunky system into a world-class one, attracting foreign money – FDI in stocks hit records in 2024.

Why Shorter Cycles Are a Big Win: Benefits Explained

Shifting to shorter settlements like T+1 and T+0 brings tons of perks. Let’s unpack them with everyday examples.

Quicker Cash Flow: Money or shares arrive faster. Sell today, reinvest tomorrow. For retirees relying on dividends, this means less waiting. In T+2 days, funds were stuck; now, they’re free sooner, boosting market activity by 20-30%, as per exchange reports.

Lower Risks: Less time for things to go wrong. If markets crash overnight, you’re not exposed as long. During 2020’s COVID dip, quicker settlements could have saved billions in losses. Counterparty risk drops – if a broker defaults, impact is minimal.

Better Liquidity: More trades happen as capital circulates fast. Small investors benefit: Sell shares for a home downpayment without delays. Market volumes rose post-T+1, making prices fairer.

Efficiency Boost: Automation cuts costs. Brokers save on holding margins. For the system, fewer errors mean smoother ops. Example: Clearing houses process trades 50% faster now.

Global Edge and Trust: India’s speed draws investors. Foreign funds poured in after T+1, per RBI data. It builds confidence – no more worries about delays in a fast world.

Overall, it’s like upgrading from a bicycle to a car: Faster, safer, more fun.

Risks and Challenges in Settlement

Nothing’s perfect. Shorter cycles have hurdles too. Here’s what to know, with tips to handle them.

Tight Timelines: T+1 gives little wiggle room. Miss funding? Trade fails. For newbies, this means planning ahead. Example: During festivals, bank holidays can mess up schedules – always check calendars.

Failure Risks: Short on funds or shares? Auction time. Sellers might lose if prices drop. In 2023, some retail traders faced penalties for overselling without holdings. Tip: Use broker alerts for balances.

Global Hitches: Foreign investors deal with time zones. A US trader buying Indian stocks might struggle with same-day wires. Currency conversions add complexity. SEBI’s easing rules, but it’s still a pain.

Tech Glitches: Everything’s digital, so hacks or outages hurt. The 2021 NSE glitch delayed trades. Cyber risks rise with speed. Solution: Exchanges invest in backups, but investors should diversify brokers.

Liquidity Squeeze: Big players need cash ready fast. Small brokers might struggle. During 2022 inflation, some faced crunches.

To mitigate: Educate yourself, use reliable brokers, and keep buffers. Regulators like SEBI monitor to keep things stable.

Why Settlement Matters to You

The settlement cycle is the quiet hero of the stock market, turning promises into reality. From slow paper days to T+1 and emerging T+0, India’s journey shows smart reforms at work. It makes trading safer, faster, and more inclusive. Whether you’re a day trader flipping stocks or a long-term holder building wealth, understanding this helps you navigate better. As India pushes boundaries – with T+0 expanding in 2025 – we’re set for even smoother sails. Remember, knowledge is power; stay informed, trade smart, and watch your portfolio grow.

Frequently Asked Questions

Q1. What exactly is a settlement cycle in stocks?

It’s the timeline for transferring shares to buyers and money to sellers after a trade.

Q2. What does T+1 really stand for?

Trade plus one day – settlement on the next business day.

Q3. Is T+1 active everywhere in India now?

Yes, since January 2023 for all equity trades.

Q4. How’s T+1 different from T+2?

T+1 is one day faster, cutting risks and speeding cash flow.

Q5. What’s the deal with T+0?

Same-day settlement, optional for select stocks as of 2025, expanding gradually.

Q6. Can settlement fail, and what happens then?

Yes, if funds/shares are missing. Exchanges auction to cover, with penalties.

Q7. How does this affect foreign investors?

Time zones and forex can complicate, but SEBI’s making it easier.

Q8. Why did India switch to shorter cycles?

To reduce risks, boost efficiency, and attract global money.

Q9. What’s a Demat account’s role here?

It holds electronic shares, making transfers quick and safe.

Q10. Any tips for new traders on settlement?

Keep funds ready, check holidays, and use apps for real-time updates.

Conclusion

Wrapping up, the settlement cycle in India’s stock markets is that crucial workflow keeping everything ticking smoothly. From the standard T+1 to the zippy optional T+0, it’s all about speed and safety. We’ve covered the basics, history, steps, impacts – hopefully, it’s clearer now. Whether you’re a newbie dipping toes or a seasoned player, grasping this cycle empowers better decisions. After all, in investing, timing’s everything! Keep an eye on SEBI updates; who knows, instant settlements might be next. Happy trading, folks – may your portfolios soar.