Blog Page 284

Top LIC Pension Plans for Retirement Planning

lic pension plans

A pension plan is one of the most popular ways to save money for retirement. Pension plans offer dual benefit of pension and insurance cover. Pension plans are also known as retirement cum investment plans. In this plan you need to contribute via monthly, yearly or onetime payments and you can get steady monthly income or lump sum money post your retirement.

Pension plans help you to secure your financial future post-retirement.  There are multiple pension plans available in the market with different annuity options. It is advisable to select a retirement plan based on your retirement goals. E.g. if you want to retire early, your corpus upon maturity should be enough to support additional years. In addition to your retirement goals, you should also evaluate a plan based on annuity, return, premium payment flexibility, pension guarantee, risk coverage, and additional benefits.

LIC offers a number of pension plans. In this post, we will discuss Top LIC Pension Plans for retirement planning. In addition to that, we will also look at tips to choose the right pension plan.

What is Pension Plan?

A pension plan is a retirement insurance policy/scheme that offers regular income and bonus, post-retirement at a low premium. It is investment cum insurance plan.

Types of Pension Plan in India

Types of Pension Plans available in India are given below.

Deferred Annuity – A deferred annuity plan allows you to accumulate corpus via regular or single premium over a policy term. Pension begins at the end of term.

Immediate Annuity – Immediate annuity scheme allows only lump sum one time investment. Pension begins immediately at the end of policy term. You can get benefit of tax exemption on the premium paid.

Annuity Certain – Under annuity certain scheme pension is disbursed for a specific period. The policyholder is allowed to select the period. The nominee can claim the pension after the death of the policyholder.

With Cover Pension Plan – With cover pension plan comes with life cover component. This means that on the death of the policyholder, a lump sum amount is paid to the family members. The coverage amount in this case is not very large.

Life Annuity – Life Annuity plan is plan where pension is paid till death. If option of with spouse is selected spouse will continue to receive pension on the death of policyholder.

National Pension Scheme – NPS scheme is backed by the government of India. National pension scheme allows you to invest your money in equity and debt market based on your preference. You can withdraw 60% of money at the time of retirement and remaining money you need to use for buying annuity.

Guaranteed Period Annity Plan – Under this scheme, annuity is given to the life assured for certain period like 5,10,15 or 20 years irrespective of survival of policy holder.

Top LIC Pension Plans for Retirement Planning

LIC offers multiple pension plans such as LIC Jeevan Nidhi, LIC Jeevan Shanti, Jeevan Akshay etc. Details of LIC pension plans are given below.

LIC Jeevan Nidhi

LIC Jeevan Nidhi is launched by LIC in the year 2013. LIC’s New Jeevan Nidhi Plan is a conventional with profits pension plan which provides death cover during the deferment period and offers annuity on survival to the date of vesting.

Eligibility Conditions –

  • Minimum Basic Sum Assured :  Rs.1,00,000
  • Maximum Basic Sum Assured :  No Limit
  • Minimum Entry Age  :  20 years (nearest Birthday)
  • Maximum Entry Age :  60 years (nearest birthday)
  • Policy Term :  5 to 35 years
  • Minimum Vesting Age :  55 years (nearest birthday)
  • Maximum Vesting Age :  65 years (nearest Birthday)

Benefit on Vesting – On vesting an amount equal to the Basic Sum Assured along with accrued Guaranteed Additions, vested Simple Reversionary bonuses and Final Additional bonus, if any, shall be made available to the Life Assured. It gives two different options one is to purchase immediate annuity plan or to purchase new single Premium deferred pension product from LIC.

Benefit on Death – If policyholder expires during the first five policy years, basic sum assured along with accrued Guaranteed Addition shall be paid as lump sum or in the form of an annuity or partly in lump sum and balance in the form of an annuity to the nominee.

In case if policy holder expires after first five policy years, basic sum assured along with accrued Guaranteed Addition, Simple Reversionary and Final Additional Bonus, if any, shall be paid as lump sum or in the form of an annuity or partly in lump sum and balance in the form of an annuity to the nominee.

LIC Jeevan Shanti

LIC Jeevan Shanti is pension plan launched by LIC in the year 2018. LIC Jeevan Shanti is a Single Premium Guaranteed Pension Plan (Plan 850). It is a non-linked, non-participating, one-time investment annuity plan wherein policyholder can select from the immediate pension or deferred pension options. This means you can start receiving pension either immediately on the maturity of this policy or at deferred annuity option.

Eligibility Conditions –

Immediate Annuity

  • Minimum Age – 30 years
  • Maximum Age – 85 years
  • Min Annuity – Rs.1000 monthly, Rs.3000 Qly, Rs.6000 Half yearly and Rs.12000 yearly
  • Minimum Purchase Price – 1.5 Lakh

Deferred Annuity

  • Minimum Age – 30 years
  • Maximum Age – 79 years
  • Maximum Vesting Age – 80 years
  • Min Annuity – Rs.1000 monthly, Rs.3000 Qly, Rs.6000 Half yearly and Rs.12000 yearly
  • Minimum Purchase Price – 1.5 Lakh

There are multiple annuity options under this plan.

The annuity options under immediate annuity are given below.

  • Option A Immediate Annuity for life
  • Option B Immediate Annuity with a guaranteed period of 5 years and life thereafter
  • Option C Immediate Annuity with a guaranteed period of 10 years and life thereafter
  • Option D Immediate Annuity with a guaranteed period of 15 years and life thereafter
  • Option E Immediate Annuity with a guaranteed period of 20 years and life thereafter
  • Option F Immediate Annuity for life with return of Purchase Price
  • Option G Immediate Annuity for life increasing at a simple rate of 3% p.a.
  • Option H Joint Life Immediate Annuity for life with a provision for 50% of the annuity to the Secondary Annuitant on the death of the Primary Annuitant.
  • Option I Joint Life Immediate Annuity for life with a provision for 100% of the annuity payable as long as one of the Annuitant survives.
  • Option J Joint Life Immediate Annuity for life with a provision for 100% of the annuity payable as long as one of the Annuitant survives and return of Purchase Price on the death of the last survivor

The annuity options under deferred annuity are given below.

  • Option 1 Deferred annuity for Single Life at vesting age
  • Option 2 Deferred annuity for Joint Life at vesting age

Pradhan Mantri Vaya Vandana Yojana

LIC Pradhan Mantri Vaya Vandana Yojana is pension scheme notified by the government for the senior citizen above 60 years. It is government subsidized pension scheme which shall provide an assured return of 8% per annum payable monthly (i.e equivalent to 8.30% per annum) to the pensioner surviving during the policy term of 10 years. Pradhan Mantri Vaya Vandana Yojana is a single premium payment pension plan. This pension plan offers an option to choose either the amount of pension or the Purchase Price. The last date of applying for this policy is up to 31st March, 2020.

Eligibility Conditions –

  • Minimum Entry Age – 60 Years Completed
  • Maximum Entry Age – No Limit
  • Policy Term – 10 Years
  • Maximum Purchase Price – 15 Lakh

Benefits –

Pension payment – On survival of the pensioner during the policy term, Pension shall be payable as per selection of mode.

Death benefit – On the death of the policy holder during the policy term, the purchase price shall be returned back to the nominee.

Maturity benefit – On survival of the pensioner to the end of the policy term, Purchase price and final pension instalment shall be payable.

Tips for the selection of Right Pension Plan

Few important tips while shortlisting pension plan are given below.

  • Make estimate of future financial goals. Consider your current expenses and expected future expenses while evaluating pension scheme.
  • Evaluate all available plans, read the benefit offered by the plan post retirement and select plan accordingly.
  • Don’t invest in the pension plan for the sole purpose of saving tax.
  • Know other Investment options and select the best investment option based on safety of capital and returns.

If you think any of above LIC pension plans are suitable for requirement start investing.

Best Mutual Funds for Child Education in 2021

0

Best Mutual Funds Child Education – We always dream to give the best education to our child but do we really think about the growing cost of child education? We want a child to become doctor, engineer or businessmen but do we really plan for it? As per me saving for child education is the most important goal for parents. Other goals like buying a car or buying a home can be compromised, but we should not compromise our child education.

As you know that the cost of Education in India is growing like anything. To meet expenses of higher education, you need to arrange more funds either from your own pocket or you need to borrow the money. The only way to finance your child education in the future is sound financial planning and investment strategy.

Mutual Fund is one of the best and preferred investment option for child education. By investing in mutual funds, you can help your child to achieve his or her future dreams. In this post, I will share Best Mutual Funds for Child Education in 2021. Before disclosing best mutual funds for child education let’s try to estimate – How much money will be required for Child Education in Future?

Also Read – How to Find Best Child Education Investment Plan

Estimating Cost of Child Education in the Future

The cost of education in India is rising at an unprecedented rate. The reason for this is very simple.

A lack of policy by the government to regulate private school and colleges. Moreover, the shortage of physical infrastructure and a highly qualified teacher is another problem. A teacher to student ratio is very high and teachers are not well trained. In most of the school and colleges, teachers do not teach in their regular classes and create a situation where students are required to opt for tuition. All these things ultimately cause an increase in education cost in India.

As per rough estimates, the cost of education is increasing by 10% on annual basis. On conservative estimate engineering course that costs 6 Lakh at present will likely to cost 15 Lakh after 10 years. Similarly, an MBA course costing 10 Lakh will cost 25 Lakh after 10 years.

Data shows that fees of premier institute IIT for engineering have increased by five times in the last 10 years. IIT (B.Tech) fee was 2.28 Lakh in 2008 and now it is 10 Lakh. Similarly, fees of IIM for PGP course has nearly doubled. A fee of PGP course in IIM Ahmedabad was 11.5 Lakh in 2008 and today it is costing 19.5 Lakh.

cost education india

Forget premium institute like IIM and IIT, an average fee of Engineering course is roughly Rs 6 Lakh today, five years down the line it would be close to double meaning Rs 12 Lakh. In 10 years’ time, it’s likely to cost around Rs 20 Lakh.

The growing cost of education has no dead end. The options left with you succumb to the situation by taking education loan or plan for child education.

A mutual fund is one of the best investment options in India for child education planning. Here is a list of Best Mutual Funds for Child Education in India.

Also Read – Cost of Child Education – Planning & Calculator

Best Mutual Funds for Child Education in 2021

Shortlisting method for Mutual Funds –

  • Type of Funds -The first factor for the shortlisting is a type of fund like large cap, small cap, mid cap, and balance etc. I have tried to shortlist fund in all categories.
  • Fund performance – The second factor used for shortlisting of a fund is the fund performance. I have selected the best performing fund 5-10 years’ time frame.
  • Benchmark – I have taken into consideration the performance of the fund against a benchmark index.
  • Fund Rating – Another factor of shortlisting is fund rating. Higher the fund rating better is fund. I have considered a rating given by Value Research. The fund rating above 3 stars is considered.

Some of the funds might be a repetition of earlier recommendations. My recommendations are divided into three parts long term, medium term, and short term.

Long Term – Child Age 0-5 Years

Suppose you are planning for child education for the newborn baby or for child up to age 5 years. Your child will enter the graduation phase at the age of 18 years. This means you have a couple of years in hand. To be precise you have 13-18 years’ time frame. You should plan to invest in large cap, mid cap and small cap funds that offer the highest growth potential.

First step is to estimate child education cost in the future. You can take reference from the above section. Once you arrived at the required corpus second step is to calculate monthly investment amount required.

Case – 1

  • Age of Child – 0 Year
  • Corpus Required – 20 Lakh after 18 Years
  • Expected rate of return by Mutual Funds – 15%

SIP Amount required in the above case would be Rs.2100.

Case – 2

  • Age of Child – 5 Year
  • Corpus Required – 20 Lakh after 13 Years
  • Expected rate of return by Mutual Funds – 15%

SIP Amount required in the above case would be Rs.4600.

Here are few recommended Mutual Funds for long term investment. These mutual funds are mix of large cap, mid cap and hybrid.

best mutual funds long term

Note – Above mutual funds returns detail is as on Feb,2019.

Medium Term – Child Age 6 -10 Years

Suppose you are planning for child education for the child in the age group of 6-10 Years. This means you have 8-12 years’ time frame. You should plan to invest in large cap, multi cap and Hybrid funds.

You need to follow a similar method given in the section above to arrive at corpus figure. The only change here would be age of the child and required time frame for investment.

Case – 1

  • Age of Child – 6 Year
  • Corpus Required – 20 Lakh after 12 Years
  • Expected rate of return by Mutual Funds – 15%

SIP Amount required in the above case would be Rs.5500.

Case – 2

  • Age of Child – 10 Year
  • Corpus Required – 20 Lakh after 8 Years
  • Expected rate of return by Mutual Funds – 15%

SIP Amount required in the above case would be Rs 11500.

Here are few recommended Mutual Funds for medium term investment. These mutual funds are mix of large cap, multi cap and hybrid.

 best mutual funds medium term

Note – Above mutual funds returns detail is as on Feb,2019.

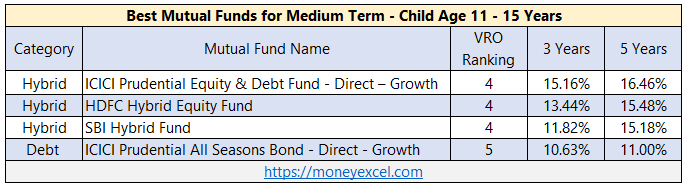
Short Term – Child Age 11-15 Years

Suppose you are planning for child education for the child in the age group of 11-15 Years. This means you have 3-7 years’ time frame. As this time frame is very low it is advisable to invest in mix of debt fund and hybrid funds.

Here are few Best Mutual Funds for short term investment. These mutual funds are mix of debt fund and hybrid funds.

best mutual funds short term

Note – Above mutual funds returns detail is as on Feb,2019.

Food for Thought 

A purpose of this article is not to increase your worry about the cost of child education but make yourself aware of the situation so that appropriate step can be taken.

Do share your experience and views about the cost of education by adding comments.

How to Make Money via YouTube? – Complete Guide

Do you want to make a lot of money using YouTube? If Yes! You are at the right place. In this post, I will share complete information about making money using YouTube. YouTube is the 2nd biggest search engine after Google. YouTube is generating billions of views every single day. Every minute, more than 300 Hours of videos are uploaded on YouTube. All these make YouTube the most powerful platform for making money. There are a lot of YouTubers making thousands of dollars every month using YouTube. You can also make a lot of money via YouTube, provided you select the right category and upload unique videos consistently. Here are steps that can help you in earning money via YouTube.

Also Read – 7 Ideas to Make Money Online in India for beginner

5 Steps to make money from YouTube

Step 1 – Create Your YouTube Channel

The first step is creating your own YouTube Channel. It is very easy to create a channel, you just need to follow the steps given below to set up your own YouTube Channel.

  • Log in to your Gmail account, if you don’t have one create it. After login visit youtube.com
  • Click on the drop-down menu present just on the left side of the YouTube logo
  • Go to the My Channels option from that menu
  • Once you click on My Channel you can see an option to ‘Set up your channel on YouTube’
  • Now, you need to provide your personal information for the creation of a channel

make money youtube

Step 2 – Selecting a Niche

The next step is selecting a niche or category. You should select a Niche based on your area of interest. Here are a few recommended category options that can help you to go Viral on YouTube.

  • Gaming
  • Personal Finance
  • Food & Cooking
  • Yoga, Exercise or Training
  • Technical Reviews
  • Travel & Fashion
  • Comedy

The above categories are popular and have a lot of audiences all over the world. You can easily gain a lot of popularity and subscribers in the mentioned category. You have to consistently post unique and informative videos on the channel.

Step 3 – Create Unique Informative and Viral Videos

In this step, you need to create unique and informative videos. You can use either handy cam, HD camcorder, or mobile for creating videos. If you are not good at acting or shooting videos, you can use software such as VideoScribe, or Camtasia for creating whiteboard animation or screen capture videos.

Make sure to keep an eye on your competitor to know what type of videos they are creating and which videos are going viral. You can use a similar type of video on your channel.

You need to be consistent. Make sure to create high-quality videos with unique content. It is recommended to follow a schedule for posting videos. You can also declare that schedule to your audience. Post at least two to three videos per week.

Step 4 – Increase your Subscribers

The next step is to grow your subscriber count. You can increase your subscriber count easily. Here are a few tips for increasing your YouTube Channel Subscriber count.

  • Create customized and appealing thumbnails for every video. You can embed video views or unique photographs on thumbnails.
  • You should create a compelling title for your videos. Most of people see thumbnails and titles for viewing videos.
  • You should describe the content of your video in the meta description. Use keywords for tagging. It will help in ranking your videos in search.

Step 5 – Apply for AdSense

The final step for making money via YouTube is applying for AdSense which is also known as a YouTube Channel Partner Program. Your channel must meet the monetization criteria set by YouTube. Your channel needs at least 4000 watch hours in the past 12 months and 1000 subscribers.

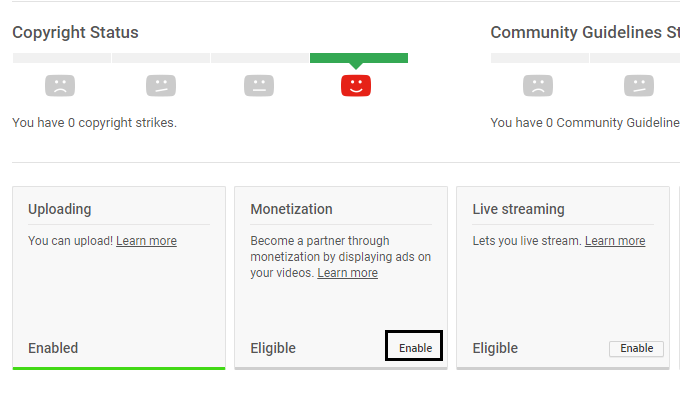
In order to apply for AdSense, you need to visit YouTube Dashboard. In the dashboard click on ‘Status and Features’, and you will see various tabs. Click on the Enable button under Monetization. Click on the Start button and follow the on-screen instructions. Once your account is approved you will get an email from Google about approval.

YouTube Monetization

Now you can monetize your videos by opening your Video Manager and clicking on the “$” sign next to the video that you want to monetize. Check the “Monetize with Ads” box. You should have a bank account and you must be 18 years of age to apply for the above program.

How do people make money via YouTube?

YouTubers use multiple methods to make money via YouTube. The few most popular methods are given below.

YouTube Advertising

The first method of monetization is using the AdSense advertisement program. You can use multiple ad formats on YouTube videos to earn money. These formats are display ads, overlay ads, skippable video ads, bumper ads, sponsored cards, etc. You can select ad formats for your videos.

YouTube Red

YouTube Red is a paid subscription program. In YouTube Red members pay a recurring fee for watching videos without Ads. The amount paid by YouTube Red is calculated based on the time members spend watching videos.

YouTube Merchandising

You can also use YouTube Merchandising to make money. You can endorse a specific product or brand and make videos. You can earn a lot of money.

Affiliate Marketing

Another idea of making money via YouTube is Affiliate Marketing. In this method, you need to add an affiliate link to the video description. You can earn commission income using affiliate marketing.

Paid Videos

Once your channel gets popular you can get an offer for the paid video. In this method, you need to make a video for a product or brand and post it on your channel. You will get paid on a per video basis.

Summing Up 

There are multiple YouTubers in India that makes thousands of dollars every month. A few examples are Geeky Ranjit, Technical Guruji, BB Ki Vines, etc.

In short, YouTube is an evergreen platform that helps people to make a lot of money. Apart from making money it also helps in branding and gaining popularity as a YouTuber. If you are serious about making online money you can consider YouTube Monetization.

Connect with us by sharing your thoughts and experiences in the comment section.

Do share this post with others.