Blog Page 268

ULIP – Unit Linked Insurance Plan – Should You Invest?

ULIP – Unit Linked Insurance Plan is a combination of investment cum insurance. Recently I got a marketing call for selling a unique product that provides life cover, investment, and tax benefit. The guy started with a sales pitch that product is like a fixed deposit and it comes with additional insurance benefit. It even gives you tax saving and you need to invest with a lock-in period of 5 years. It was a clear case of mis-selling ULIP. This incident inspired me to write about ULIP as a product.

How ULIP works? 

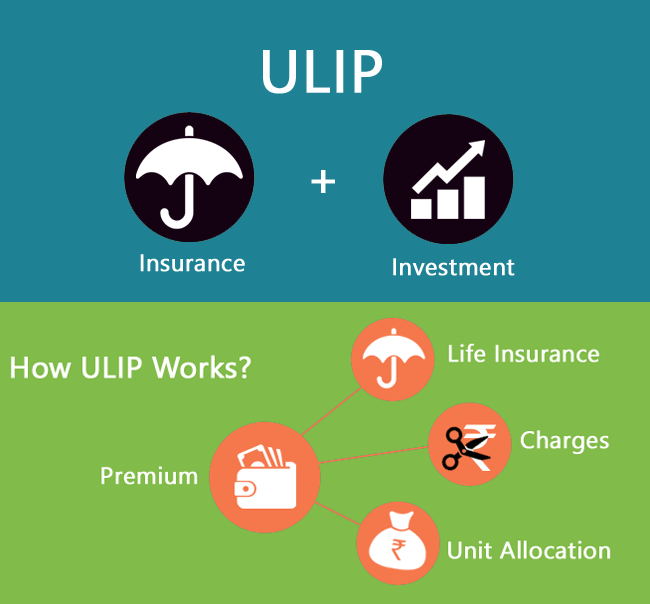
ULIP is an insurance cum investment product. You need to pay a premium to purchase unit linked insurance plan. The premium amount of ULIP is divided into two parts. Part of the premium is kept exclusively for buying life or health insurance while the remaining amount is used for making investments. The investment is made in equity or debt or both. The total invested corpus is divided into units and allocated to you as per the invested amount. The net asset value (NAV) of the allocated unit is decided and declared from time to time.

ULIP is managed by a fund manager. Fund managers invest the fund and responsible for tracking and making changes. (If required). You can switch your ULIP portfolio based on risk appetite.
ULIP Unit Linked Insurance Plan

Types of ULIPs 

The Unit Linked Insurance Plans are classified based on three broad parameters.

  • Investment Portfolio
  • Financial Goal
  • Death Benefits 

(1) Investment Portfolio 

Equity Funds – In equity funds, the premium amount is invested in equity funds. This type of fund is risky in nature.

Balance Funds – The fund that invests a premium amount in equity as well as debt to minimize risk is known as balance or hybrid funds.

Debt Funds – In debt funds, the premium amount is invested in debt instruments to reduce the risk. The return offered by this fund is less. 

(2) Financial Goal 

Retirement planning – The primary aim of this fund is to generate a corpus for retirement. This type of unit linked insurance plan is generally identified with suffix retirement. 

Child Education – This type of unit linked insurance plan fund is made for child education. The product here is identified with the suffix of child education.                                                                                    

Wealth Generation – If your financial goal is to generate wealth you can use wealth generation type funds for investment.

(3) Death Benefits 

Type I ULIP – This type of unit linked insurance plan pays higher of the assured sum value or fund value to the nominee in case of death of the policyholder.

Type II ULIP – This type of unit linked insurance plan pays the assured sum value plus the fund value to the nominee in case of the death of the policyholder.

Type of Fees and Charges

When you invest in ULIP you need to pay multiple fees and charges. This makes this product costly. The charges associated with this product are given below.

1 Premium Allocation Charges

The allocation charges deducted from premium in the initial years of the policy. It is charged at a higher rate. It includes initial and renewal expenses. It is kind of loading on the premium paid.

2 Mortality Charges

Mortality charges is charges to provide insurance coverage. This charge depends upon multiple factors such as age, sum assured etc. This charges are deducted on a monthly basis.

3 Fund Management Charges

The fee imposed by the insurance company for the management of various fund in the ULIP is known as fund management charges. It is like expense ratio charges of the mutual funds.

4 Partial Withdrawal Charges

ULIP comes with a lock-in period of 5 years. However, few ULIP offers the option of the partial withdrawal. You need to pay extra money for the partial withdrawal of money from ULIP.

5 Policy Administration Charges

The policy administration is also charged separately in the ULIP. It is levied at a fixed rate or as a percentage of your premium. 

ULIP vs Mutual Funds 

The primary difference between Mutual Fund and ULIP is of return. Mutual Funds generally provide higher returns. Apart from returns, mutual funds can be withdrawn at any time. However, ULIP comes with lock-in period of 5 years. The comparison table of ULIP vs Mutual Funds are given below.

ULIP Mutual Funds
Type Investment cum Insurance option Pure Investment option
Withdrawal Lock-in period of 5 years Can be withdrawn anytime
Return At long run returns are low Returns are higher at long run
Switching Switching between ULIP is permitted without any taxation. Switching is permitted. However, it is considered as capital gain and tax is applicable.
Charges Morality Charges, Premium Allocation charges, fund management and administrative charges Exit load as applicable

Things to consider before investing money in Unit Linked Insurance Plan

Looking at the product investors get excited as they see life insurance coverage and investment in a single product. However, you should note the following points before investing money in the ULIP.

  • The fee structure of Unit Linked Insurance Plan is complicated. You need to pay multiple charges in order to purchase this product. The fee charges impacts returns of the unit linked insurance plan.
  • Unit Linked Insurance Plan has lock-in period of 5 years. This means your money will be locked for 5 years after investment. If you are looking for liquidity you need to think twice.
  • The ULIP investment funds are generally not diversified this means risk associated with this unit linked insurance plan is high.
  • Compare all features and fees associated with unit linked insurance plan before investing your money.
  • As you can’t exit from underperforming ULIP, the performance becomes important factor when you are investing in the ULIP product. You should compare past performance before making investment decision.

Over to you –

I hope now you have got a complete understanding of ULIP as a product. If you ask my views, I would recommend keeping investment and insurance separately. You should purchase good mutual funds and term plans instead of investing in Unit linked investment plan. The combination of mutual funds and term plan will give higher returns compared to a unit linked insurance plan.

Another reason of not recommending ULIP is higher fees and charges which will reduce the performance of the product. If you still decide to invest in unit linked insurance plan you should go for low-cost ULIP.

10 Best Credit Cards 2025-26 – Top Credit Card Picks

0

Best Credit Cards 2025-26 – Which is the best credit card for 2025? Well, it is a known fact that the choice of best credit card is different for every individual. The reason is credit card choice depends on the purpose, goal, and lifestyle of the individual. That’s why I have compiled a list of the best credit card 2021 in all major categories like cash back, travel, premium and lot more. Explore Top Credit Card Picks from the list given below and select the best credit card for you.

#1 Best Credit Cards for Cashback and Rewards

#2 Best Credit Cards for Online Shopping

#3 Best Credit Cards for Business

#4 Best Credit Cards Travel Category

#5 Best Credit Cards Premium Users

Before sharing a list of best credit cards let’s take a look at steps that you should follow to find out the right credit card for you.

Also Read – 15 Types of Credit Cards in India and Usage

How to choose a credit card?

Usage of the Card

Firstly, decide what is the purpose of availing a credit card? This means to decide what you will use the card for. E.g if you are looking for a credit card for general spending you should go for low-interest credit card. If you are looking for a card for travel cashback you should go for a card providing travel benefits.

Look at your Spending Habits

To find out your usage or to decide the purpose of the card, look at your spending habits. You can divide your expense into major categories such as groceries, fuel, business spending, restaurant, etc. it is advisable to look at the past few month expense sheet to see what type of expenses are made by you frequently. Choose a card that provides maximum rewards in the category where you are making frequent expenses.

Compare Key Features

You should look at the key features offered by the card. The key features of the card include cashback, rewards, cash withdrawal fees, security features, minimum payment, sign up bonus, other perks, add on card, Flexi pay option, etc. Choose the card that offers maximum features.

Look at Annual Fees and Interest rates

The next point to consider while selecting a credit card is annual fees and interest rate applicable on the card. Select the card that offers lowest interest rate on the default. It is advisable to go for life time free credit card without any annual fees.

Credit limit and Penalties

You should check applicable credit limit and penalties applicable in case of default or delay in the payment. Credit limit means amount that is allowed per month by credit card issuer. If your usage is high it is recommend to go for card with higher credit limit.

Best Credit Card 2020

Best Credit Card 2025 – Top Credit Card Picks

#1 Credit Card for Cashback and Rewards

Citi Cash Back Credit Card

Citi Cash Back Credit Card is one of the best credit card that provides cashback and rewards. You can enjoy saving, cashback and multiple other benefits using this card. The key features of Citi Cash Back Credit Card are given below.

  • 5% cashback on movie ticket, telephone and utility bill payments. The maximum cashback is Rs.100 for each category per month.
  • 0.5% cashback on any other spend.
  • Up to 15% saving across participating restaurants.
  • Cashback redemption in multiple of Rs.500 credited automatically.
  • Facility to convert bill in to EMI.

Joining Fee – NIL

Annual Fee – Rs.500

Interest rate – 3.5% per month

HDFC MoneyBack Credit Card

HDFC MoneyBack Credit card is one of my favorite credit card. Accelerated rewards and saving of fuel expense are plus points of this card. Key Features of HDFC MoneyBack Credit Card are given below.

  • 2 Reward points on every Rs.150 spent using card.
  • 2X more reward points on online purchase.
  • Enjoy saving up to Rs.250 with 100% fuel surcharge waiver.
  • Redeem point for gifts and air miles.
  • Zero liability lost card benefits.

Joining Fee – Rs.500

Annual Fee – Rs.500

Interest rate – 3.49% per month

#2 Credit Card for Online Shopping

SBI Simply Click

SBI Simply Click as name indicates it is credit card for online users. This card provides exclusive benefits for online shopping on Amazon, BookMyShow, Cleartrip etc.

  • Amazon Gift Card of Rs.500 on joining.
  • 10X rewards on online shopping with exclusive partners.
  • 5X rewards on any other online spending.
  • Milestone base spend reward of Rs.2000.
  • 1% fuel surcharge waiver on fuel spend.
  • Annual fee reversal facility.
  • Contactless Technology.

Joining Fee – Rs.499

Annual Fee – Rs.499

Interest rate – 3.35% per month

ICICI Bank Coral American Express Credit Card

ICICI Bank Coral American Express Credit card is next in the list of best credit card for online shopping. This card is projected as extra reward card that provides multiple benefits on shopping, travel and entertainment.

  • 2x reward points on online spends.
  • 2 Payback reward on every Rs.100 spend.
  • Get complimentary movie ticket per month.
  • Save 15% money on dining bills at participating restaurant.
  • Fuel surcharge waiver.
  • Easy redemption of payback points.

Joining Fee – Rs.500

Annual Fee – Rs.500

Interest rate – 3.40% per month

#3 Credit Card for Business  

SBI Corporate Platinum Card

SBI Corporate Platinum Card is privilege credit card for the business owners. From travel to spend management this card provides multiple benefits. Key features of SBI Corporate Platinum Card are given below.

  • Globally accepted credit card.
  • Analyze entire organization spending pattern using spend management tool.
  • Real time dashboard for expense management.
  • Multilayer spend control facility.
  • Fraud related insurance coverage of 2 Lakh.
  • Discount offer on the travel tickets.

Joining Fee – NIL

Annual Fee – NIL

Interest rate – 3.35% per month

MY Business Credit Card

MY Business Credit card from axis bank is one of the best credit card for managing your business expense. This card comes with exclusive business saving plan and multiple other benefits.

  • Business saving plan that provides discount and cashback on flight, ticket and holiday offers.
  • Complimentary access to airport lounges.
  • Cash withdrawal up to 30% of your credit limit.
  • 1% fuel surcharge waiver.
  • Convert major purchase to EMI.
  • Auto bill payment facility.

Joining Fee – Rs.999

Annual Fee – Rs.499

Interest rate – 3.25% per month

#4 Credit Card Travel Category 

Citibank PremierMiles Credit Card

Citibank PremierMiles Credit card is best air mile credit card for travel. It is a best card for travel user. You need to pay higher annual fees for using this card. Key features of Citibank PremierMiles Credit Card.

  • 10 Miles on every Rs.100 Spent on flight tickets.
  • Complimentary airport lounge access.
  • Air accident insurance coverage up to 1 Cr.
  • Up to 20% saving on various restaurants across India.
  • Redeem miles for any flight ticket.

Joining Fee – NIL

Annual Fee – Rs.3000

Interest rate – 3.5% per month

JetrPrivilege HDFC Bank World Credit Card

JetPrivilage HDFC Bank Signature Debit card is specially designed for frequent travelers. This card provide facility to accumulate JP Miles to redeem for free flights.

  • 5% discount on base fare for tickets booked on Jet Airways.
  • 6 JPMiles per Rs.150 on retail spend, 12 JPMiles per Rs.150 on flight booking with jetairways.
  • Complementary airport lounge access.
  • Additional baggage allowance.
  • Cash Advance and Easy EMI Facility.

Joining Fee – Rs.2500

Annual Fee – Rs.2500

Interest rate – 3.5% per month

#5 Credit Card Premium Users

SBI Elite Card

SBI Elite Card is best credit card for the premium segment users. SBI Elite Credit Card comes with multiple rewards and privileges. If you want high credit limit and premium benefits on products and services you should use this card.

  • You will get e-gift voucher worth Rs.5000.
  • Complementary movie ticket of Rs.6000 every year.
  • 5x rewards on dining, grocery & departmental store purchases.
  • Club Vistara Membership.
  • Lowest foreign currency markup charges.
  • Exclusive concierge service.
  • Fraud liability coverage.

Joining Fee – Rs.4999

Annual Fee – Rs.4999

Interest rate – 3.35% per month

HDFC Regalia Credit Card

HDFC Regalia Credit Card is luxury credit card for rich and premium customers. Priority customer services, rewards and travel benefits are major facilities that you can avail from this card.

  • 4 Reward points on every Rs.150 spend.
  • Lowest Foreign currency markup fee of 2% on international transactions.
  • Travel Concierge Services.
  • Free accidental death insurance & credit liability coverage.
  • Earn extra reward spend on crossing annual spend limit.
  • Airport Lounge access.
  • Fuel surcharge waiver

Joining Fee – Rs.2500

Annual Fee – Rs.2500

Interest rate – 3.49% per month.

How to Get a Personal Loan with a Low Interest Rate?

A personal loan is any purpose loan. You can use this loan for any purpose like medical emergency, marriage expenses, renovation of a home, paying for a dream holiday, etc. It is one of the easiest ways to get money from the market. The interest rate offered on a personal loan is generally higher compared to any other loan. However, if you have an urgent requirement for money, a personal loan is a very good option. Services like UK Quick loans also offer fast approvals, making funds accessible when time is critical. You must be aware that many banks sanction and disburse the loan within 24 hours of your application. Even a few banks and lending organizations give pre-approved loan offers.

So, if you are planning to avail of a personal loan and want to reduce a cost by getting a low interest rate here are proven ways.

personal loan low interest rate

Also Read – 10 Best Instant Personal Loan Apps for Quick Cash Requirement

How to Get a Personal Loan with a Low-Interest Rate?

Maintain a Good Credit Score

A credit score plays a crucial role in deciding your loan amount, interest rate, and processing charges. You need to maintain or improve your credit score by repaying your debt over a period of time. Your credit score should be above 750. A credit score above 750 means a very good chance of getting one of the best loans for low-interest rates. There are multiple ways to maintain and improve your credit score. A few of them are listed below.

  • Pay bills on time
  • Keep your credit card balance low
  • Limit your application of new credit card and loans
  • Maintain a credit utilization ratio
  • Check your credit report at regular intervals

Employment History

Your employment history also plays a vital role in reducing the personal loan interest rate. If you are maintaining good job stability it affects your credit score positively. In addition to your employment history, a few lending companies also look at factors such as repayment capacity, income, and profile to decide on a personal loan interest rate.

Credibility of Employer

The credibility of an employer is one of the important factors in reducing personal loan interest rates. If you are working with blue-chip companies or multinational companies your chance of getting a personal loan with a low interest rate is high. The reason is the employer is able to provide steady and higher job security with a stable income.

Repayment History

Repayment history is crucial for getting a personal loan at a lower rate. Pay your credit card bill on time. Pay the EMI of your loan on time. If your repayment history is good you get a better chance to negotiate interest rates with lenders.

Monthly Income

It may sound unfair but your monthly income also matters a lot when deciding personal loan interest rates. Your monthly income should be high to get a good deal on a personal loan.

Relationship with Bank

Your relationship with the bank also matters a lot while applying for a personal loan. If you are a loyal customer of a bank and maintain all your transactions with the same lender or bank, your bank/lender is likely to offer a personal loan with low interest rate.

Check Alternatives

You should check for other alternatives when seeking a personal loan with a low-interest rate, exploring alternatives like commercial hard money loans can offer distinct advantages. While traditional personal loans often come with stringent eligibility criteria and lengthy approval processes, commercial hard money loans provide a viable option for individuals seeking quicker access to funds. These loans, secured by commercial real estate, offer competitive interest rates and flexible terms, making them an attractive option for borrowers with substantial assets or businesses in need of capital. By leveraging the value of commercial properties, borrowers can secure financing with favorable terms, enabling them to meet their financial needs while minimizing interest expenses.

Smart Strategies to Get the Lowest Possible Rate

Now let’s dive into the good stuff—how to actually score that low-interest personal loan.

Keep That Credit Score High

It’s your golden ticket. Aim for 750 or above. Here’s how:

  • Pay EMIs and credit card bills on time

  • Keep credit utilization under 30%

  • Avoid too many loan applications at once

Compare, Don’t Settle

Never go with the first offer you get. Use online platforms like BankBazaar, PaisaBazaar, or your bank’s loan calculator to compare rates from multiple lenders.

Negotiate Like a Pro

Yes, you can negotiate your interest rate! Especially if:

  • You’re a long-term customer

  • Your credit score is excellent

  • You have pre-approved offers

Credit Cards vs. Personal Loans—Which Is Cheaper?

Factor Credit Card Loan Personal Loan
Interest Rate 24–36% p.a. 9–18% p.a.
Repayment Flexibility Low High
Loan Tenure Short Long

Best Banks for Low-Interest Personal Loans in 2025 (So Far)

Bank Starting Interest Rate (p.a.)
HDFC Bank 10.50%
ICICI Bank 10.75%
SBI 9.60%
Axis Bank 10.49%
Kotak Mahindra Bank 10.25%

FAQs

1. How can I improve my credit score quickly to get a lower interest loan?

Start by paying off your credit card dues in full, avoid new loan inquiries for a while, and don’t miss any EMI payments. Consistency is the key.

2. Can I switch lenders if I find a better rate after taking the loan?

Yes! You can opt for a personal loan balance transfer, which lets you move your loan to another bank with a lower rate.

3. Is it safe to take personal loans from online apps?

Stick to RBI-registered lenders only. Some shady apps may charge crazy interest rates and harass borrowers.

4. Do women really get lower interest rates?

Yep! Many banks offer 0.25% to 0.5% lower rates as a perk for women borrowers. It’s part of financial inclusion initiatives.

5. What’s better—short tenure with high EMI or long tenure with low EMI?

Short tenure means less total interest paid. But if budgeting is tight, a longer tenure with smaller EMIs might work better.

6. Can self-employed people get low-interest personal loans?

Definitely—but you’ll need strong ITRs, audited financials, and a good credit history. Some lenders even specialize in these profiles.

7. Is it cheaper to take a loan from my salary account bank?

Usually, yes. Banks love existing customers and often offer preferential rates, especially if your salary hits their account every month.

8. Can I take a personal loan to pay off a credit card?

Absolutely. In fact, it’s one of the smartest ways to escape high credit card interest. Just ensure the loan rate is lower than your card APR.

9. What’s a good interest rate for a personal loan in 2025?

Anything below 11% p.a. is solid for unsecured loans this year. Of course, your credit score, income, and loan amount play a role.

10. Does applying for too many loans hurt my chances?

Yes, it does! Each application triggers a hard inquiry, which can lower your credit score and make you look credit-hungry.

Over to You –

Before taking a personal loan make sure that your need is unavoidable and can be fulfilled by only a personal loan. Because the higher interest rates of personal loans singapore will put you under great financial pressure. Ask the following questions yourself before taking a personal loan.

  • Do I really need a loan?
  • Can I postpone my expenses?
  • Can I manage without a personal loan?
  • Is it possible to get the money from somewhere else, like friends, relatives, or a part-time job?

How to find Multibagger Stocks?

0

How to Find Multibagger Stocks? Where to invest money for getting multibagger returns? These are the most frequently asked questions by stock market investors. I have received many e-mails asking for recommendations and suggestions about multi-bagger stocks. The common questions asked by the investors are –

  • Tell me the name of stock which can double my money.
  • Which stock will be next multibagger like Eicher Motors?
  • Can you recommend good stock for investing which can make me millionaire?

Well, instead of recommending a specific stock, I decided to write the post about – How to identify multi-bagger stocks?

Multibagger Stocks

Multibagger stocks are stocks that provide extraordinary returns to investors. Suppose you have purchased stock with Rs.100 and after few years you sold it for Rs.500, then it is 5-bagger stock for you.

Similarly, if you got 10 times returns on your original investment it is 10-bagger stock.

Remember, you will not get an overnight return in these types of stock. You need to wait for a few months or years to get returns.

A true multibagger stock can multiply your wealth and you can become a millionaire by investing in these types of stocks. However, it is difficult to identify such stocks. You need to do a lot of research to find such stocks. In order to help you, here is complete information about finding multi-bagger stocks.

Also Read – How to find Multibagger Stocks? – Secrets of finding Multibagger

How to Find Multibagger Stocks?

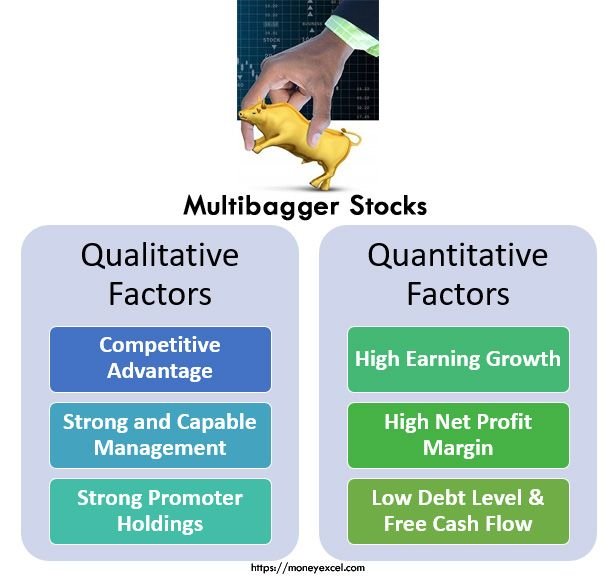
In order to find multibagger stocks logically, you need to two types of research/analysis about stock.

  1. Qualitative Analysis

Qualitative analysis is a scientific method of observation to gather non-numerical data about the stock. This includes brands, product range, management, promoter holding etc.

  1. Quantitative Analysis

Quantitative analysis is a method of getting numerical (quantity) data about the stock and doing analysis. This includes financials, cash flow, debt level etc.

multibagger stocks

Qualitative Characteristics  

First let’s try to focus on qualitative factors of the stocks.

Competitive Advantage

Competitive advantage means favorable circumstances that put business ahead of the competition. It includes products & services.  You also need to consider branding as well as a monopoly in business. This factor allows a business to perform better and get price advantage and market share over peers.

In order to find this quality, you need to ask the following questions while analyzing a stock.

Do the company offer unique products? – A company can achieve a competitive edge via unique products. You need to check if the company is offering unique products or not. A company like Reliance Jio is offering Jio Fiber at a competitive rate. This gives a durable competitive advantage of Reliance Jio.

Do the company has established a big brand or in a monopoly business?  – Another thing to check is a monopoly in business by the company. A monopoly business means higher profit margin and more returns. A company should have a preferably big brand name and high entry barrier.

Strong and Capable Management

A company should be in a safe hand. You should check for the honesty and capability of the management. Only strong management is not enough. Management should have a future goal and plan to achieve it. To find out this quality you need to ask the following question while analyzing a stock.

Do the company have a clear goal for the business in the future? – A company should be clear about goals and future business prospects. Honest management plays a crucial role here. You can get information about this by reading an annual report or going through management interviews.

In addition to the goal set by the management, you should also look that goals are realistic or not. A company should be able to demonstrate how they are going to achieve that.

You should also check if management has a proven track record and history of achieving past goals or not.

Strong Promoter Holdings

Strong promoter holding is the next important factor to check. Promoter means people that start, fund and operate a business.

A company with strong promoter holding indicates the trust of the founders in the business. A low promoter holding indicates promoter has less faith in the business and they have pulled out money from the business.

A promoter holding should be at least 50% or above. In a few cases, you may not find strong promoter holdings as holding is distributed to multiple holders including institution and public.

Quantitative Characteristics

Now let’s try to look at quantitative factors of the stocks.

The stock should be sound fundamentally. To evaluate the fundamental of stocks you need to check the quantitative characteristics of the stock. You can do that by evaluating the financial statement and quarterly results of the business.

High Earning Growth

Earning growth is the first quantitative factor to consider. A company should have high earning growth. Earning growth is the annual growth rate of earning from investment. This factor provide valuable information such as how fast a company is growing.

One of the best way to know earning growth is via EPS (Earning per Share). EPS is calculated by dividing net profit by total number of shares. This shows how much company is earning against each share. EPS of stock should be higher.

One year EPS is not enough while evaluating. You should consider past three years EPS while evaluating stock.

High Net Profit Margin

High net profit margin is another quantitative factor for consideration. A company should be performing well and should have a high net profit margin. You can calculate Net Profit Margin by dividing net profit by total sales of the company. A multibagger stock should have a higher profit margin.

You should consider the past three years’ net profit margin while evaluating a stock.

Low Debt Level

Debt is bad for any company. It can destroy a business at any time. When you are evaluating stock you should look at the stock with low or nil debt level. A debt-free company is a very good candidate for multibagger.

You can get information about the debt level from the balance sheet of the company.

Free Cash Flow

Free cash flow is the next quantitative factor to consider. Free Cash Flow is total cash left with the company after making capital expenditures such as the purchase of plant, machinery, technology, etc.

Free cash flow can be used for business expansion, new product development, debt payment or dividend distribution. You can get information about free cash flow from the financial statement of the company. You need to subtract capital expenditures from operating cash flow to get this information.

A company should be generating free cash flow year on year. This is one of the factors that helps the stock to become a multibagger.

Note – I have tried to list down characteristics that are useful for identifying multi-bagger stocks. If you find the above information useful, do share it with your friends and collogues via Facebook, Twitter or WhatsApp.