Blog Page 262

Stock Market Crash – Should you exit Stock Market now?

Stock Market Crash

The stock market is falling. I am losing money in Stocks & Mutual Funds, I am worried a lot- What to do? Should I exit the stock market now? I recently received this question via e-mail. This is a common question, which is bugging many investors nowadays.

A Carona Virus has created a massive impact on the stock market. Retail investors are in a panic situation. Many investors are thinking that they should stop their SIP. Some of them are of opinion that they should sell all their equity investment and put leftover money in the bank. Few of them want to hold their investments.

So which approach is correct? What investor should do? Well, I don’t guarantee that you will get answers to your all questions here. But, I assure that you will be in a better position to decide what to do in current stock market conditions.

Also Read – 20 Best Mutual Funds for Investment in 2020-21

Stock Market Crash – Should you exit Stock Market now?

Under the current market scenario where the stock market is falling, here are five things that stock market or mutual funds investor can do.

#1 Stay Relax and Cool

Firstly, Don’t get panic. Stay Relax, cool and do nothing. This advice is for the long term investors.

The stock market goes up and down but in the long run it is likely to perform better and provide good returns to the investors. In the short term due to volatility and various other factors, the price of a stock is likely to go down. Your portfolio may lose shine as you lose money in equity and mutual funds. But, if you hold stocks for the longer duration you are likely to recover and get better returns.

So, if you have longer time horizon say 5-10 years, don’t get disturbed with any bad news. Stay cool.

#2 Don’t Stop your SIP

Secondly, don’t stop your SIP. Stopping SIP at this moment is foolishness.

As you know that you can earn in the market if you follow – Buy low & sell high principal. It indirectly means when the market is down, you have to buy more and when market is up, you should buy less.

SIP works on the same principal. The above principal automatically gets applied on the SIP.

Let me explain – Suppose you do SIP of Rs.1000 in the mutual funds every month. When stock market was up the particular mutual funds where you invested your money its NAV was Rs.100. This means you every month you were buying 10 units. Now when market falls, the NAV of mutual fund will reduce automatically. Suppose NAV is reduced to Rs.50.  If you continue your SIP of Rs.1000, you will get 20 units instead of 10 units. This means you have got more unit in the same price when market is low and you got less unit in same price when market is up.

So, you should not STOP your SIP when stock market is down.

#3 Avoid Redeeming your Mutual Funds

The third important thing you need to understand when stock market is falling is avoid redeeming your mutual funds. Many investors make this mistake.

Investors think that it is easy to get out of market at this stage and re-enter back before recovery. But it is almost impossible because no one can time the market.

Additionally, when you exit from mutual funds or stocks when market is low you will end up making losses. You may need to pay exit load if it is mutual fund investment. If profit from your equity investment is above 1 lakh, you need to pay long term capital gain tax.

So decision of redeeming mutual funds or selling all your stocks under Stock Market crash condition & reentering again when market is up is totally wrong.

#4 Invest only if you have surplus money

When stock market is falling many people think about making investment. Investing money when market is down is very good option. However, make sure that you select fundamentally strong stock for the investment. The company where you are investing money should be cash rich with lot of working capital.

As it is very risky to make investment during stock market crash. It would suggest that invest only if you have surplus money in hand and you are ready for losing money.

#5 Don’t Invest money in the Market at Single GO

If by chance you want to invest money in the stock market when market is falling, avoid investing lump sum money at single go. We cannot predict the stock market it may further go down. So, always prefer SIP option and never invest your money in the market at single GO.

Over to you –

What you are planning to do in current stock market crash?

Do you want to exit from stock market or you prefer to stay invested?

 Please share your opinion in the comment section given below.

10 Best Business Courses in 2020 for Highest Paying Business Careers

0

Best Business Courses

Doing a business course is becoming essential if you are planning to start your own business or want to enter in highest paying business careers.

There is a cut-throat competition in the business world, hence it is but natural that you should select a course that pushes you ahead from other people. The course that helps you to learn all business skills for managing and growing business. The first course that comes in our mind when we talk about business is MBA (Master of Business Administration). But, apart from MBA, there are wide range of other business courses, degrees, and universities at your disposal.

Selecting the best option among them is slightly challenging. Here is readymade help. I have prepared a list of 10 Best Business Courses in 2020. These business courses help you in enhancing your professional skills problem-solving skills, leadership, communication, business administration, and finance skills.

Also Read – 10 Best Digital Marketing Course in India

Why Business Course? 

There are multiple benefits associated with business courses. A few of them are given below.

(1) Management Skills

The business requires managerial skills. Businesses can not operate properly without managerial skills. Managerial skills are of three types conceptual skills, human skills, and technical skills. The business course provides education to students for all types of management skills.

(2) Leadership Skills

The business course helps to develop leadership skills. Leadership skill is mandatory to run a business. You will get a good insight on leadership skills in the business course. You will also able to improve your leadership skills while doing these courses.

(3) People Management Skills

People Management and handling are mandatory for running a business. You need to learn to delegate work and supervision of the same. When you learn business management you will be able to effectively manage people and work.

(4) Career Improvement

You can get a competitive edge over others and withstand in the market. The course will give a boost to your career and you will be ready to face new challenges with respect to running a business.

(5) Get Acquainted with the reality of business

You can get acquainted with the reality of the business. Especially, when you are new to business without prior experience.

Success in business is built upon a strong foundation of education and understanding of how successful businesses are run. 

Many students have opted done business courses and got good exposure to the business.

10 Best Business Courses in 2020 for Highest Paying Business Careers

For better understanding, I have classified business courses in the following categories.

  • Diploma level Business Courses
  • Degree level Business Courses
  • Post Graduate or Master Degree in Business
  • PhD Business Courses

Diploma level Business Courses 

#1 Diploma in Business Management

Diploma in Business Management is a certificate program for management education. You will get basic management skills under this course. The course duration is one year. The course is available at a few institutes all over. You will need a bachelor degree to get admission in this course.

Degree level Business Courses

#2 Bachelor of Business Administration or Business Management

Bachelor of business administration is popular as a BBA course. This course content includes all aspects of overseeing and supervising business. You will learn leadership, finance, accounting, project management and marketing under this course. It is 3-years course that can be taken up after class XII.

Post Graduate or Master Degree Courses 

#3 Master of Business Administration

Master of Business Administration is popular as an MBA Course. You will get a master’s degree after doing this course. You require a bachelor’s degree to start this course. This course can be done by an experienced professional also. It is a two years course. The course content includes all topics related to business administration including project work, case study, and internship. The course is available full time, part-time as well as distance. It is recommended to go for a full-time course.

#4 MBA in Business Information Systems

MBA in the Business Information system is a newly introduced course with good career prospects. The course content includes a combination of business and information technology. You can get a very good job at a senior position in IT or business by doing this course. It is a two-year full-time course offered after a bachelor degree.

#5 MBA in Banking & Investment

MBA in banking and investment is a specialized course for people interested in the banking and investment sector. It is two-year full-time course available to the bachelor degree holders.

#6 Post Graduate Program in Management for Executives

Post Graduate Program in Management for Executive is also known as ePGPx program. The main objective of this program is to develop leadership and management skills for challenging managerial situations. It is one year course offered to experienced professionals.

#7 Master of Management Studies

Master of Management Studies is popular as MMS program. This program is offered by many premier institutes. The course duration of this program is two years. You need to be a bachelor degree holder for getting admission to this program.

#8 ePost Graduate Diploma in Advanced Business Analytics

There are many B School’s that offers ePost Graduate Diploma program for business analytics. The course content of this program includes problem-solving and analytics techniques. The course duration is 16 months. 

PhD Business Courses 

#9 PhD in Management Studies

PhD in management studies is a doctorate program that helps you to develop planning, leading and management capabilities. You will need a master’s degree to enroll for PhD program. The course duration is 3 years.

#10 PhD in Business Administration or Management

PhD in Business Administration or Management is one of the top and highest paying career options. You need to have M Phill or Master degree to register for this program. The course duration is 2 to 5 years. You will get a lot of business insights by doing this course.

Conclusion –

In the end, I would like to say that doing a business course will surely help you in enhancing your business knowledge and kick-starting the highest paying business careers.

The business course will not only helps students but also to experienced professionals. Even if you are looking for a career change or job change doing MBA course will make you more competitive in the job market.

Make sure to select the good institutions for doing a business course. You need to pass common entrance tests such as GMAT, CAT, XAT, MAT or SNAP to get admission in these business courses.

How to do Home Loan Balance Transfer & Top Up?

Home Loan Balance Transfer

Home Loan Balance Transfer – Buying a home is difficult without a home loan. Once you take a home loan from a bank or financial institute you need to pay principal and interest component. Both these components are part of your EMI.

Suppose you have taken a floating rate home loan for the longer duration say 15 years or 20 years, your bank is increasing interest rate frequently. In this case, you will end up paying more interest to your bank. There are multiple ways to reduce your Home loan interest component which I have already discussed in my earlier post. One such way is the Home Loan Balance Transfer.

A home loan balance transfer is offered by most of the banks and financial institutions. Home loan balance transfer makes sense if the offer by other bank is lucrative in terms of interest rate and transfer fees. Additionally, a home loan balance transfer is beneficial for the first 4 to 5 years of home loan as an interest rate component will be higher in the initial years. If you are planning to do a home loan balance transfer or top up this post is for you. In this post, I will share information about How to do Home Loan Balance Transfer and Top Up? 

What is Home Loan Balance Transfer?

Home Loan Balance Transfer means transferring a balanced loan to other banks or financial institutions. The primary reason for doing a home loan balance transfer is to save higher interest outgo. The process of doing a home loan balance transfer is very easy, but before you opt for balance transfer do a proper analysis of saving and cost associated with a transfer of the loan.

What are benefits of Home Loan Balance Transfer?

There are multiple benefits of home loan balance transfer a few of them are given below.

  • Reduction in interest rate resulting in lot of saving with respect to interest payment.
  • Reduction in monthly EMI based on rate difference, balance tenure and EMI.
  • NIL processing fee and other benefits provided by other bank.
  • You can Top-up loan and avail additional loan at same home loan rate.
  • Satisfactory customer support services, if you are not satisfied with current bank.

How to do Home Loan Balance Transfer?

The steps to do home loan balance transfer are given below.

Step 1 –  The first step is evaluating the need for a balance transfer program. To do that check your current rate and calculate your interest outgo.

Step 2 – In addition to interest, outgo you need to calculate various other costs, fees associated with your current home loan.

Step 3 – Shortlist a new bank that you wish to transfer your loan. In addition to the shortlisting bank for loan transfer also decide that you want top-up loan or not. Once you decide which bank you want to go for find out the documentation requirement of the bank and documents deposited with your existing bank.

Step 4 – Apply for a loan with a new bank with a photocopy of property documents and other documents such as income proof, ID proof etc. You also required to submit the document on the letterhead of existing bank stating the list of property documents held by them. The bank also requires latest outstanding balance letter from your existing bank on their letterhead. The bank may require your own contribution proof in the property. You also need to pay loan processing fee.

Step 5 – The next step is to obtain a sanction letter from a new bank and execute a new loan agreement. Once your loan agreement is executed, you need to take disbursement in favor of old bank by cheque or demand draft. Alternatively, you can also ask bank to do online transfer and internally get home documents transferred.

Note – Some bank requires prior notice before you initiate home loan transfer. Check your current loan agreement and ask your bank about any terms and conditions like this. If notice is applicable you need to give notice to the bank.

How to find out best deal for Home Loan Balance Transfer?

The first thing to do to find out the best deal for a home loan balance transfer is checking interest rate and track record of the new lender. Also check the benchmark rate track record of the new lender.

Check the service level and customer support offered by a new bank. You can take feedback from existing customers or check online references. It should not happen that a lower interest rate means inferior services.

The home loans are offered with a benchmark rate MCLR rate and prime lending rate (PLR). MCLR rate are more transparent compared to PCR hence it is advised to go for MCLR home loan.

Check for the estimated cost of a transaction. This includes processing fee and other applicable fees for transferring loan.

You can take help from online portals to find out the best deal for home loan balance transfer.

You can also prepare a comparison table for taking up fast decision. Here is a sample table.

Best Home Loan Transfer Offers in India – Comparison Table

Bank Home Loan Transfer Rates Processing Fess EMI per Lakh
SBI Home Loan Transfer 7.90% 0.20% – Min Rs.4000 Rs.727
HDFC Home Loan Transfer 8.00% Min Rs.10000 Rs.734
Bank of Baroda 8.00% Min Rs.10030 Rs.734
ICICI Bank 8.45% 0.25% Rs.765
Axis Bank 8.25% 0.50% Rs.751

What is Top-up Home Loan?

Top-up Home loan is a facility provided by the bank and other financial institutions that allow you to borrow an additional amount over and above your home loan. It is like top-up of your mobile SIM. In mobile SIM when the balance is low, you opt for top-up. Similarly, in a Home loan if you have an additional requirement you can opt for additional money by Top UP Home Loan.

You can utilize Top-up money for property modification or construction of your house or meeting your personal expense also. The Interest rate applicable on top-up home loans is higher compared to a regular home loan.

To get Top-Up Home Loan, you need to contact your bank. You can get this loan in a regular course or even when you apply for a balance transfer.  

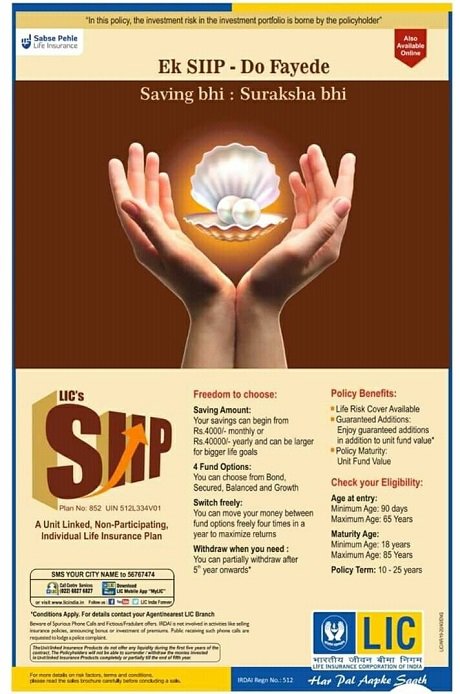
LIC SIIP Plan No 852- Systematic Investment Insurance Plan

LIC SIIP Plan No 852 is a new ULIP plan launched by LIC on 2nd March 2020. This plan is unique in terms of many aspects. SIIP is unit linked, non-participating, individual life insurance plan. SIIP is the second ULIP policy launched by LIC in the year 2020. Along with SIIP LIC has also launched single premium ULIP plan called as LIC Nivesh Plus Plan No 849. This plan is available in online as well as offline mode. You can invest in four different fund options under this policy.

Let’s take a look at LIC SIIP plan key features, eligibility, benefits in detail and try to figure out is it worth investing or not.

LIC SIIP Plan No 852 – Key Features & Eligibility 

  • LIC SIIP is regular premium policy with monthly saving option of Rs.4000 or yearly saving option of Rs.40000.
  • The insurance coverage will be 7 times if age is above 55 and 10 times for others.
  • Premium paid will be converted to unit as per the unit price on the date payment.
  • You can select from four different fund options bond, secured, balanced and grwoth. This is similar to LIC Nivesh Plus policy.
  • Switching is allowed between all four funds four times in a year. This is to ensure higher returns from the investment.
  • You can withdraw money from this plan after 5th The withdrawal will be in the form of fixed amount or fixed number of units. Partial withdrawal is not allowed to minor.
  • This plan provides life risk cover option.
  • Guaranteed addition offered in addition to unit fund value. The percentage of guaranteed addition will be a percentage of the fixed annualized premium.
  • You cannot get loan facility under this plan.
  • The facility of surrender is available after the lock-in period of 5 years. The fund value available as on date is paid in case of surrender.
  • This plan also provide additional riders such as accidental riders.

LIC SIIP Plan

Eligibility 

Minimum Entry Age – 90 days

Maximum Entry Age – 65 days

Minimum and Maximum Maturity Age – 18 years to 85 years

Policy tenure – 10 years to 25 years

Lock-in period – 5 years

Sum Assured – 10 times of annualized premium for age below 55 years and 7 times of annualized premium age above 55 years.

LIC SIIP Investment Fund Options

Bond Fund – Bond fund is relatively safe and suitable for low risk investors. This fund does not invest any money in the equity shares.

Secured Fund – Secured fund is intended to offer steady income to the investor with the combination of equity and fixed income securities.

Balanced Fund – Balance Fund provides balance and growth to the investors. This fund is for medium risk investors. This fund invests in equity and fixed income securities.

Growth Fund –  Growth fund is for aggressive investor. This fund is intended to provide capital growth to the investor.

LIC SIIP Benefits

Maturity Benefit 

If insured survives till the maturity date, the plan will offer an amount to the policy holder which is equal to fund value. 

Death Benefit 

On the death of policy holder before commencement of risk during the policy tenure, the plan will pay an amount equal to fund value to the nominee. On the death after the date of commencement risk, higher of sum assured or unit fund value is paid to the nominee. 

LIC SIIP Plan Review – Should You Invest?

In order to conclude that SIIP is worth for investment or not let’s take a look at positive and negative of this plan.

LIC SIIP Plan  – Positive & Negatives
Positives Negatives
(1)   Four fund option for the selection (1) Overall charges applicable are very high
(2)   Facility to switch between funds (2) Risk is high as returns are market linked
(3)  Mortality charges will be refunded by LIC (3) Low sum assurance for age above 55 years
(4)   Guaranteed addition of 5-25% at specific intervals (4) Premium allocation charges and other charges are very high.
(5)   Expected returns from this policy is low

SIIP is policy is projected as systematic investment plan and mainly launched to attract salaried people who are looking for last minute tax saving option. The expected return from this policy will be low as charges are very high. I would not recommend investing in LIC SIIP Plan. Instead of SIIP, you can invest in other tax saving instruments such as ELSS, PPF, Tax saving FD etc.