Blog Page 227

Children Gift Fund – Is it the best investment option for Child Education?

Children Gift Fund – Saving and Investing Money for child education has become a primary need. Education cost is skyrocketing in India as well as abroad. The growing cost of education is a concern for everyone. It seems that being a parent if you have not planned or invested money for the higher education of your children, you may end up taking a loan.

Let’s take a look at child education cost numbers. The cost of getting an education in a reputed school today is around Rs.15000 per month and it is increasing year on year. The estimated cost of an engineering course in a good institute today is 8 Lakh and that would cost Rs.18 Lakhs by 2030 and by 2040 it would cost Rs.40 Lakhs. Similarly, course of MBA in reputed university is offered at Rs.15 Lakhs today and it is expected to reach Rs.30 Lakhs by 2030 and may cross Rs.60 Lakhs by 2040.

Don’t get scared by these numbers. Numbers given here are not to threaten you but to awake you to plan for your child’s education.
Children Gift Fund

If you are planning for child education, you may come across an investment avenue called a Children Fund (mutual fund) or Children Gift Fund & you may be planning to invest your money in it. Here is complete information about the children’s fund that will help you in knowing whether – children’s fund is the best investment option for child education or not?

What is Children Gift Fund? 

Children fund or children gift fund is one type of mutual fund that is designed with objectives specific to child-related goals. Most of the children’s funds invest in both equity as well as debt. An investor can select between equity-oriented or debt-oriented funds based on the risk appetite.

Children’s funds come with a mandatory lock-in period of 5 years and it can be extended further until the child becomes an adult. Few children’s plans come with the optional add-on benefit of life insurance. The maturity amount of this fund is taxable. However, parents can take benefit of section 80C tax deduction claim up to 1.5 Lakhs by investing money in the children’s fund.

The prime purpose of the children’s fund is to create a fund for necessary expenses of a child such as higher education, boarding, relocation, etc.

Children Gift Fund Comparison with Other Investment Options

Here is a comparison of a children fund with respect to other popular investment options for a child such as PPF, FD & Sukanya Samriddhi Scheme.

Investment Options Risk Tenure Liquidity Type of Return Expected Return
Children Fund Moderate High 5 Years Limited Market Linked 10 -15%
PPF Low Risk 15 Years Partial Fixed 7.1%
FD Low Risk 6 Months to 10 Years High Fixed 5  – 7%
Sukanya Samriddhi Scheme Low Risk 8-10 Years Limited Fixed 7.6%
High Risk Equity Oriented Mutual Funds High Open Ended High Market Linked 15-20%


Note – Above returns are indicative only.

After making a comparison of children fund with other investment options let’s take a look at the benefits and drawbacks of children fund.

Benefits  

  • Children fund is a long-term investment option where parents can select a fund based on investment objective and risk appetite. 
  • Investment in this fund eliminates the chance of future financial burden and turns out as financial assistance for child education and other goals.
  • Few children funds also come with an additional optional add-on of life insurance.
  • The parents can avail tax benefits while investing in this fund.
  • Tax indexation benefits on maturity can reduce the tax burden.
  • One can invest in this fund via SIP and Lumpsum route. 

Drawbacks 

  • This fund has a lock-in period of 5 years and above hence liquidity is limited.
  • The return is linked with the market and lower compared to equity-oriented mutual funds.
  • Children fund is a categorization made by SEBI but it does not offer anything special compared to mutual funds except add-on benefits and a lock-in period.

Children Gift Fund – Is it best investment option for Child Education?

Looking at the comparison, benefits, and drawbacks, children fund is a very good investment option for child education. However, it is not the best investment option.

As per me, Children funds are like a hybrid fund with few additional benefits and a lock-in period of 5 years and above.

Children education is a long-term affair and from a long term return point of view equity mutual funds with the SIP route offers much higher returns compared to the children gift fund.

If you are worried about the increasing cost of higher education you should create a diversified investment portfolio with major investment in equity-based mutual funds and high risk, high return investment options to get superior returns.

However, if you are a low-risk or conservative investor you can go for PPF or Sukanya Samriddhi Scheme to invest for your child’s future.

Happy investing!
DIY – Free Financial Planning Tools – Recipe

Financial planning means bringing the future into the present so that you can do something about it now. Financial planning is a process of utilizing available financial resources in the best possible manner to achieve your goals.  It is not just about investing money; it is about investing money the right way, to achieve specific financial goals.

But why do we need to do financial planning and which tools should be used to do it?

Why is financial planning necessary?

Let’s try to understand the need for financial planning through a story.

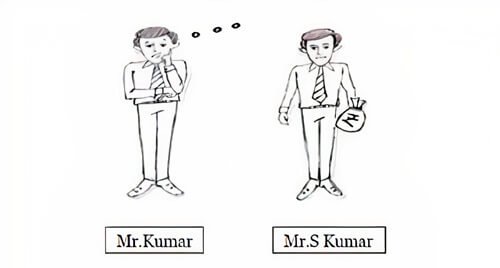
This is the story of  Mr Kumar & Mr S.Kumar.

Mr Kumar is 40 years old. He has a job in an MNC and he earns a decent salary. Like the rest of us, he works hard, earns well & makes sure that he enjoys life off the money he makes. Despite earning well, most of the time, Mr Kumar remains under pressure due to lack of money at the end of every month, not only that he is still living in a rented home & uses public transport for his commute.

Financial Planning

Now let’s meet Mr S Kumar, a colleague of Mr Kumar’s (Age 35 years) with the same salary structure. Mr S Kumar manages his finances well and by the end of every month, unlike Mr Kumar, has spare money left with him. Not only Mr S Kumar lives in a self-owned house and owns a car, he also has sufficient savings and has done investments in multiple avenues.

Why? What’s changed?

It is because Mr S Kumar understands the importance of financial planning.

He knows very well that –

Inflation Kills

Inflation eats away your money. You must have heard from your father that he would purchase petrol at Rs.30 per litre and today petrol costs around Rs.100 per litre. This steady rise in the price of goods and services is called inflation.

Emergency Fund is extremely important

You never know when a financial emergency could come knocking at your door. Whether it is unexpected medical situations, accidents or loss of job. Uncertainty is the only certainty in life.

Retirement Corpus is vital

With pensionable jobs, our parents had it easy. The government used to wholly fund an individual’s retirement by contributing to the pension funds. Today, a part of our salary is deducted for the same.

Owing to the increased cost of living, our parent’s retirement funds might have been sufficient in the past. But we need to plan better, to live a comfortable retired life with sufficient funds to our name.

Insurance is essential

Insurance is a protection against unforeseen events that can cause financial distress. Insurance provides protection against events such as accidents, unforeseen damage to property, medical mishaps and even death.

Investments are attached to goals

Each investment you make must take you a step closer to your financial goals. Investment without goals is like firing a bullet into the vacuum. Goals could be planning your taxes, a dream holiday, buying a car etc.

Cash Flow management is Key for success

You need to utilize your financial resources effectively. This is where cash flow management – earning and spending money plays an important role in financial success.

Financial Viability is crucial

We need to understand that financial viability is crucial. Financial viability means generating sufficient income and constantly upgrading lifestyle with a growing need.

So, from above it is clear that Mr S Kumar has better financial management & control compared to Mr Kumar. He has planned his finances and invested accordingly to achieve his goals.

Also read – Financial Planning Real conversation – Vaniya Buddhi

So if you want to be like Mr S Kumar or if you are in a situation similar to Mr Kumar’s you plan your finances.

There are two ways of managing your finances:

#1 DIY – Free Financial Planning Tools – Recipe

Financial planning done by oneself with limited help of an expert, excel sheet, or tools is known as DIY (Do It Yourself) financial planning. This type of financial planning is preferred by people like Mr S Kumar who understand the basics of financial planning.

Here are the steps to follow while doing financial planning –

Step -1 Know how much you can invest.

Step-2 Set your goals.

Step -3 Invest in line with the goals you set.

Step-4 Keep an eye on your investments. But do not get overly involved with every minute detail.

Step -5 Maintain a prudent emergency fund to be able to cushion possible adverse situations.

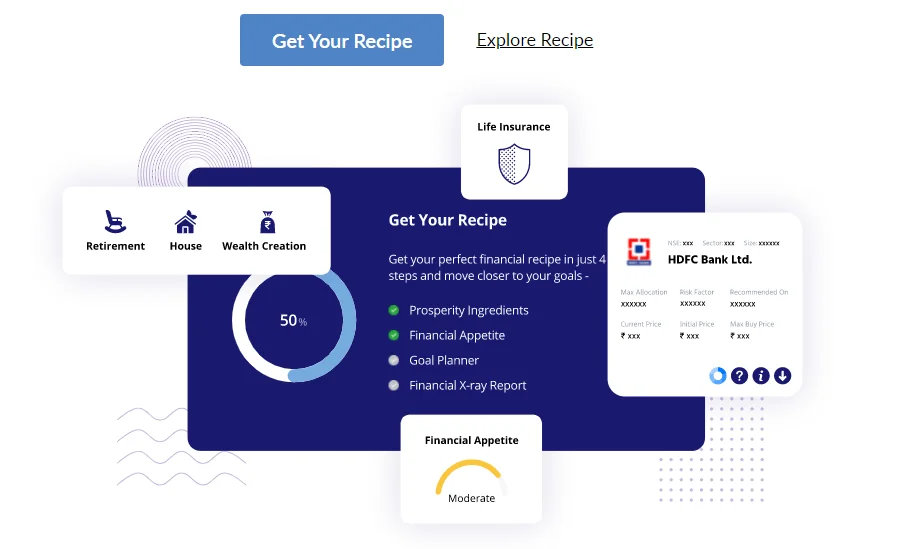
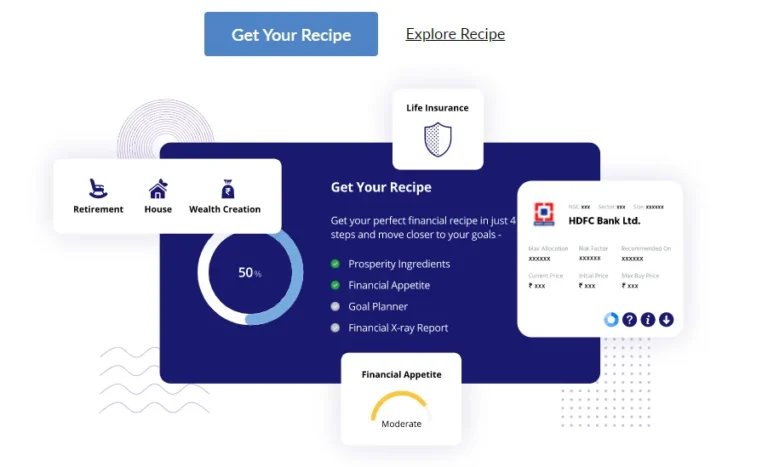
If you are interested in planning your own finances, you can use a tool called Recipe by Finology that will help you in managing your finances. Recipe is easy to use, and free from human bias due to A.I. based recommendation.

recipe-finology

This tool has four segments, Prosperity Ingredients, Financial Appetite, Goal Planner and Financial X-ray. 

Prosperity Ingredients

It is extremely important to know your current financial status before engaging in financial planning. The Prosperity Ingredient segment helps you in assessing your financial position. This segment has four “ingredients”.

  1. Emergency Fund

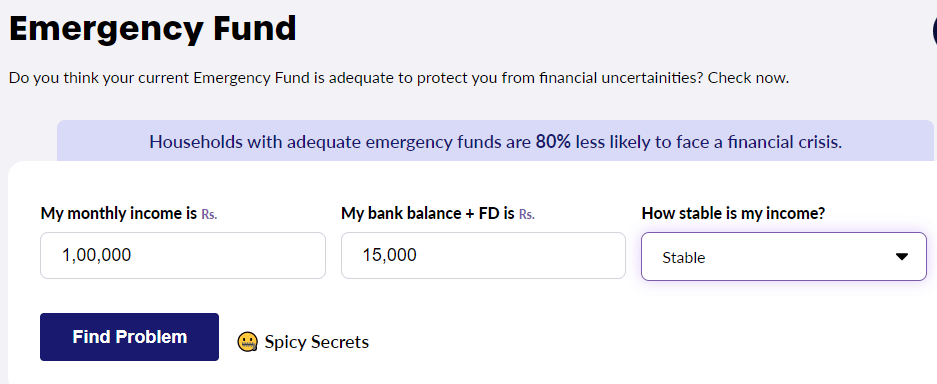
Under the Emergency Fund section, you can check if you have sufficient emergency funds for the future or not. You need to input your monthly income, details about your bank balance and select ‘stability’ of your income from the dropdown.

emergency fund

Once you click the “Find Problem” button, Recipe automatically gives you a response about your required emergency funds. It also displays your emergency fund score.

  1. Insurance Planner

Under the Insurance Planner segment, you need to provide information about your current life and health insurance amounts. You will get an instant answer whether you have adequate insurance cover or not.

  1. Debt Diagnosis

The Debt Diagnosis segment is for analysing your debt situation. Here, you need to enter your income, loan, EMI and savings details to get a debt diagnosis.

  1. Spending Habits

The Spending Habit segment helps you gauge your income and expenses. Based on your income as well as spending habits, Recipe will find out for you whether you are overspending or saving.

Also Read – DIY, Salesman or Financial Planner what is your choice?

Financial Appetite

The ‘financial appetite’ section assesses your financial standing and your attitude towards risk and determines the right investment style that suits your income, goals and risk preferences.

Goal Planner

Goal planner contains readymade goal sections such as child marriage, vacation planning, wealth creation, dream car, dream home, children’s education, retirement planning etc. You can plan for each goal by giving simple inputs.

Financial X-ray

The ‘financial x-ray’ section gives your complete 360-degree financial report. This report will help you in managing your finances and taking clever steps to boost your net worth.

Importance of Investment

As we learn that investing money in the right investment option is extremely important for financial planning, if you keep on investing money without properly analyzing, you may end up in a messy situation. You should have defined financial goals as the knowledge to execute those investments. There is a tool called Quest that offers courses on complete personal finance.

These courses cover the following –

  • Importance of saving money
  • Why investing is so important
  • Why debt funds & insurance are essential
  • Importance of Goal planning & asset allocation

#2 Hire Financial Planning Services – Paid

You need financial planning services if you –

  • Don’t have time & energy to do your own financial planning
  • Don’t have sufficient expertise in areas of investment, insurance, retirement planning.
  • Don’t know how to manage finances in a better manner
  • Seeking professional opinion about your financial plan

If any of the above questions apply to you, it may be time to take help from a financial planner to achieve financial success.

Conclusion

Financial planning is crucial nowadays. You should do financial planning for a better financial future. You can make use of DIY financial planning tools or hire financial planning services for financial planning.

Top 5 Best Performing ESS to Invest in 2022 – More than 80% returns in 3 Years

0

ELSS (Equity Linked Saving Scheme) is one of the best investment options. ELSS not only helps you to save taxes but also gives opportunity to grow your money. You can claim a tax deduction of 1.5 Lakh under section 80C by investing in ELSS. ELSS comes with 3 years lock-in period.

Tax saving season is almost at its peak only one month is left to complete your tax planning and investment exercise for FY 2021-22. If you are interested to save tax by investing in ELSS, here are the Top 5 Best performing ELSS to invest in 2022 along with the evaluation method.

How to evaluate ELSS for investment?

You should consider the following parameters while evaluating ELSS for investment.

Fund Returns

You should check fund returns and compare them with other peer funds. Fund, where you are investing your money, should be consistently giving higher returns. But please note that a higher return in the past does not mean that in the future also a similar return is guaranteed. Fund return is an indicative parameter. Fund return is completely dependent on market movement and the fund manager’s capability. 

Fund History

Select the fund that has performed consistently over the long run. You must check the fund performance history of the last five years before investing in the fund. 

Expense Ratio

The expense ratio indicates how much money is going into the fund management. A lower expense ratio means higher returns. That’s why if you come across two funds with similar track record performance you should select the fund with a lower expense ratio.

Financial Ratios 

You also need to check various financial ratios such as standard deviation, sharp ratio, alpha, and beta to analyze the fund. You should avoid the fund where standard deviation and beta are higher. It is advisable to invest in a fund with a higher sharp ratio.

Top 5 Best Performing ESS to Invest in 2022

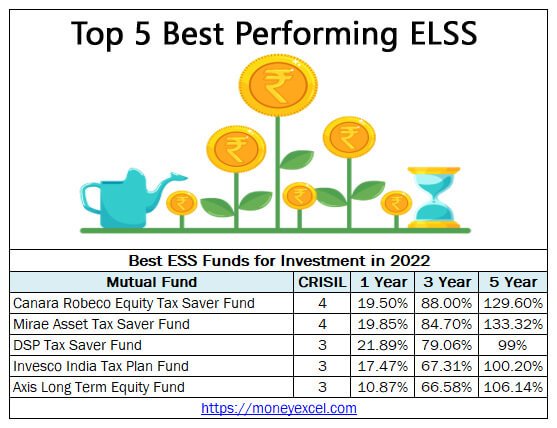
Top 5 Best Performing ELSS 2022

Note – Above returns are as of Feb 2022

Canara Robeco Equity Tax Saver Fund – Growth

Canara Robeco Equity Tax Saver Fund is one of the best ELSS for investment in 2022. This fund has given consistently higher returns to the investors. In the last five years, this fund has given more than 125% absolute return to the investors. The expense ratio of this fund is slightly higher. However, if you have the risk-taking capacity you can go with this fund.

Mirae Asset Tax Saver Fund – Growth

Mirae Asset Tax Saver Fund is one of the top-performing ELSS funds where you can invest your money in 2022. Mirae Asset Tax Saver Fund has given consistent two-digit returns to the investors in the last 3 years. The expense ratio of this fund is low. The major investment of Mirae Asset Tax Saver Fund is in blue-chip stocks such as Infosys, Reliance, HDFC Bank, etc.

DSP Tax Saver Fund – Growth

DSP Tax Saver Fund is next in the list of top-performing best ELSS for investment in 2022. DSP Tax Saver Fund has given 21% returns to the investors last year. This fund is consistently performing well. The expense ratio of this fund is manageable. 

Invesco India Tax Plan Fund – Growth

Invesco India Tax Plan Fund is another top-performing ELSS fund where you can plan to invest your money. Invesco India Tax Plan fund has given 67% returns to investors in the last three years. The expense ratio of this fund is slightly higher.

Axis Long Term Equity Fund – Growth

Axis Long Term Equity Fund is one of the best performing ELSS funds. This fund was able to deliver 106% absolute returns for the investors in the last five years. If you are planning to invest money for the long term you can go for Axis Long Term equity fund.

Things you should consider before investing in ELSS

You should consider the following things when you consider ELSS for investment.

Lock-in-Period 

ELSS comes with a lock-in period of 3 years and it is mandatory. There is no provision to withdraw your money before 3 years. This means if you are selecting ELSS for the investment you are completely blocking your money for 3 years.

Risk Factor

ELSS funds are linked with equity and it is subject to market risk. The returns given by ELSS are completely dependent on market movement. You should evaluate your risk profile before investing your money in the ELSS.

SIP or Lumpsum

You can invest your money in two ways SIP (Systematic Investment Plan) or lump sum. It is always advisable to go for the SIP route while investing in mutual funds. It gives you the benefit of rupee cost averaging in the long run. Lumpsum investment in a mutual fund is not advisable. 

Over to you

You can invest in ELSS fund for tax saving purpose.

Please note that If you are new investor and finding difficulty in identifying good ELSS fund for investment you should consult expert while selecting mutual fund for investment.