Blog Page 64

e-PAN Card Download:How to Download e PAN Card in Minutes?

An e-PAN card is an electronic PAN (Permanent Account Number) card utilized as identification evidence.

Ever found yourself in a hurry to submit your PAN details for a job, loan, or investment, only to realize you’ve misplaced your physical PAN card?

Don’t sweat it! Welcome to the age of digital documents where the e PAN Card saves the day.

Using an e-PAN card is more convenient and simpler than a physical PAN card since it can be kept digitally. Once the application is submitted, the e-PAN card is emailed to you and can be downloaded from official sites like NSDL, UTIITSL, or the Income Tax portal. You can subsequently save it electronically and utilize it wherever a PAN card is needed.

This handy digital version of your PAN card is just as legal and valid as the original physical one. And the best part? You can download your e PAN Card from the comfort of your couch — no queues, no paperwork, and absolutely no waiting!

Whether you’ve just applied for a new PAN or need a duplicate for emergencies, this guide will walk you through how to download your e PAN Card step-by-step. We’ll also answer common questions, address concerns, and help you navigate both the NSDL and UTIITSL portals with ease.
ePAN Card Download

e PAN Card

Before we get into the how, let’s clarify the what.

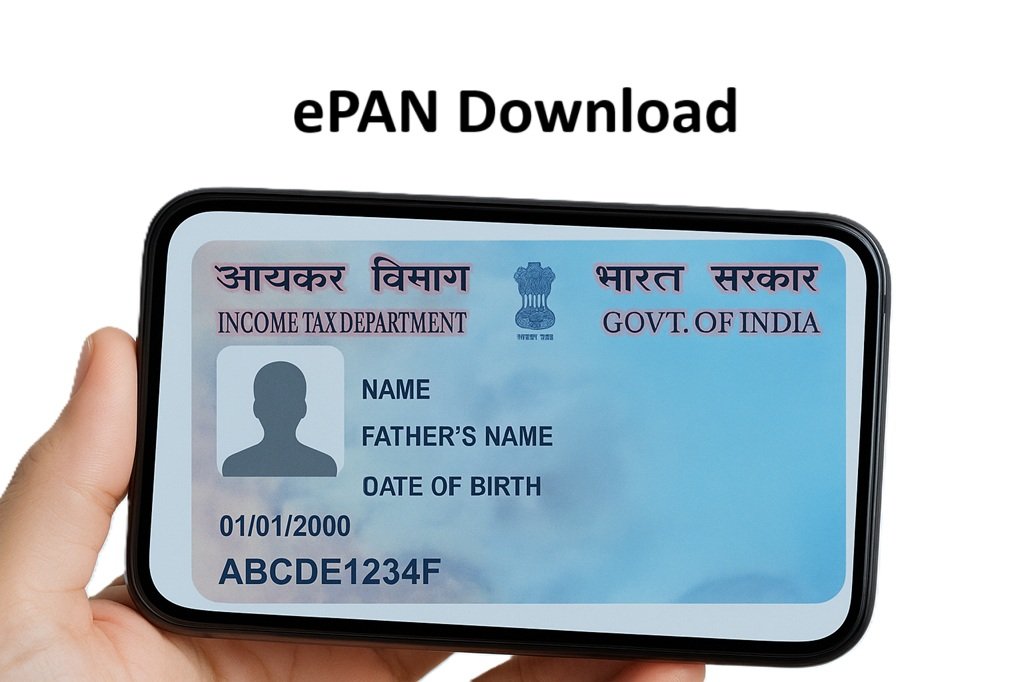
An e PAN Card is the electronically issued version of your physical PAN card, provided in PDF format. It’s digitally signed by the Income Tax Department and can be downloaded online. Not only does it carry the same details — name, PAN number, date of birth, photograph, and signature — but it’s also accepted across India as a valid proof of identity.

Think of it as your PAN card’s smarter, sleeker, and faster cousin.

Once the e-PAN card is generated, you will be able to download it after applying. Typically, the e-PAN card will be created and issued within 15 days of applying on the NSDL or UTIITSL website. The e-PAN card requested on the Income Tax website will be created within 10 minutes of submission.

Please be aware that you can only download the e-PAN card from the NSDL website if you have submitted your application on the NSDL website. In the same way, the e-PAN card can be downloaded from the UTIITSL website only if you have submitted an application on the UTIITSL website. The e-PAN card requested instantly on the Income Tax website can solely be downloaded via the Income Tax e-Filing portal.

Key Features of e PAN Card:

  • Digitally signed and encrypted
  • Valid for all legal and official purposes
  • Free for first-time applicants (if applied through Aadhaar-based method)
  • Quick to generate — usually within 10 minutes!
  • Downloadable anytime, anywhere

Here are a few common situations where having an e PAN Card on your device can be a lifesaver:

  • You lost or damaged your physical PAN card
  • You just applied for a PAN and want the soft copy
  • You need it urgently for digital KYC, banking, or tax filing
  • You’re traveling and forgot to carry the original
  • You want a backup for safekeeping

Let’s face it — the convenience of being able to download your e PAN Card whenever you want is unbeatable.

Eligiblity

Good news — not just new applicants! You can download your e PAN Card if:

  • You’ve applied for a new PAN through the NSDL or UTIITSL portals
  • You’ve linked your Aadhaar with PAN
  • You’ve recently updated details on your PAN
  • You lost your card and need a digital copy
  • You already have a PAN number or acknowledgment number

Just make sure your mobile number is registered with Aadhaar and PAN for OTP authentication.

How to Download e PAN Card: A Step-by-Step Guide

Now, let’s get to the juicy part — how to download your e PAN Card. You’ve got two main portals to choose from, depending on where you applied: NSDL and UTIITSL.

Method 1: NSDL Portal

If you applied for your PAN through the NSDL (now Protean) website, follow these steps:

Step 1: Go to the NSDL Protean website.

Step 2: Scroll down to find the ‘PAN Services Links’. Choose either the ‘Download e-PAN/e-PAN XML (PANs allocated in the last 30 days)’ or the ‘Download e-PAN/e-PAN XML (PANs allocated before 30 days)’ option, depending on your needs.

Step 3: Select ‘Acknowledgement Number’, input the acknowledgement number, date of birth, and captcha code, then click ‘Submit’.

Step 4: Choose email ID, mobile number or either one and press the ‘Generate OTP’ button.

Step 5: Input the OTP sent to your email address, mobile number, or both, and press ‘Validate’.

Step 6: Press the ‘Download PDF’ button. You can obtain the e-PAN card at no cost within 30 days of it being issued. To download the e-PAN card after 30 days of its issuance, you need to select the ‘Continue with paid e-PAN download facility’ option and pay a fee of Rs.8.26 for the download.

The e-PAN card’s pdf file will be downloaded. To access the e-PAN card, you need to input the e-PAN card password.

To open the e-PAN card downloaded from the NSDL, UTIITSL, or the Income Tax website, input the e-PAN card download password to access the pdf file containing your e-PAN card. To access the e-PAN card PDF file, use your date of birth or date of incorporation formatted as DDMMYYYY.

DIY Income Tax Return Filing: Prepare These Documents and Skip the CA Fees!

Method 2: Income Tax Portal (Using Aadhaar)

This is ideal if you’ve applied recently using your Aadhaar card and didn’t get your PAN yet.

Step 1: Go to the Income Tax e-Filing site.

Step 2: Choose the ‘Instant E-PAN’ option found in the ‘Quick Links’ section.

Step 3: Press ‘Continue’ located under the ‘Check Status/ Download PAN’ section.

Step 4: Input your Aadhaar number and press ‘Continue’.

Step 5: Input the OTP sent to your mobile number linked to Aadhaar, tick the checkbox, and press ‘Continue’.

Step 6: Press the ‘Download e-PAN’ button to obtain the e-PAN card.

Method 3: UTIITSL Portal

Applied through UTIITSL? No worries — here’s how to grab your e PAN from their portal.

Step 1: Navigate to the official UTIITSL website.

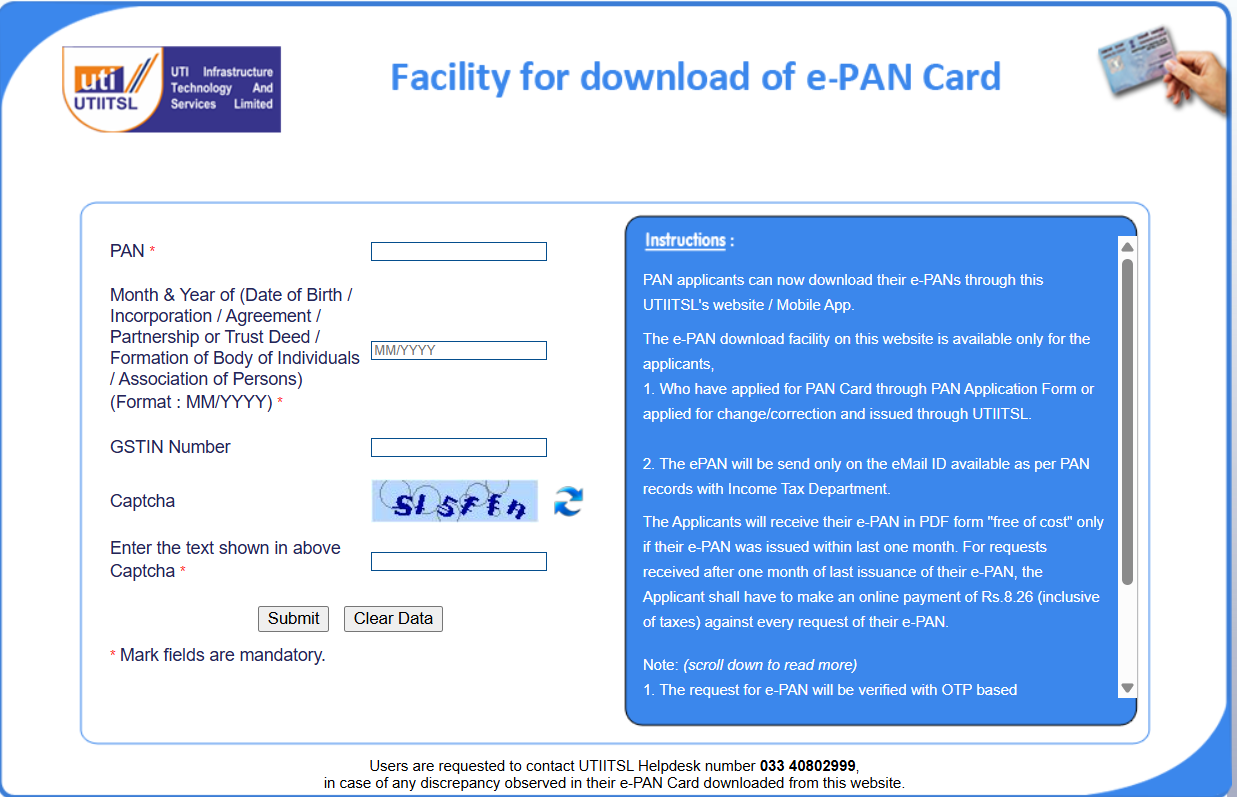
Step 2: Go to the homepage, find the ‘Download e-PAN’ section, and select ‘Click to Download’.
e-PAN Card

Step 3: Input the PAN, birth date, GSTIN number if relevant, and captcha code, then press the ‘Submit’ button.

Step 4: A link will be sent to your email address.

Step 5: Tap the link to obtain your e-PAN card by using the OTP.

You can obtain the e-PAN card for free within 30 days of its issuance. To download the e-PAN card after 30 days from its allotment, you need to pay a fee of Rs.8.26.

Forgot PAN or Acknowledgment Number? Here’s What To Do

If you’re scratching your head trying to remember your PAN or acknowledgment number, here’s how to recover it:

🔍 Find PAN Number Using Aadhaar:

  • Visit: https://www.incometax.gov.in
  • Click on Know Your PAN
  • Enter your Aadhaar number and verify with OTP

Voilà! Your PAN details will appear on the screen.

🔍 Retrieve Acknowledgment Number:

  • Check your email inbox (from NSDL or UTIITSL)
  • Log into your PAN application account
  • Or call their helpline (provided at the time of applying)

Quick Checklist Before You Start Downloading

Here’s what you need to keep handy:

  • PAN Number or Aadhaar Number
  • Registered Mobile Number (for OTP)
  • Date of Birth
  • Internet access (obviously!)
  • PDF viewer to open the e PAN Card file

Frequently Asked Questions (FAQs)

1. Is the e PAN Card valid like a physical card?

Yes! It’s digitally signed and valid for all government and private sector purposes.

2. Can I use the e PAN Card for KYC?

Absolutely. It’s accepted by banks, financial institutions, and during online KYC.

3. What if my mobile number is not linked with Aadhaar?

You’ll need to visit a PAN center or Aadhaar Seva Kendra to update your mobile number.

4. Is there a fee for downloading e PAN?

If it’s a new PAN via Aadhaar, it’s free. For re-issue or duplicate download via UTIITSL, a small fee may apply.

5. What if I lose access to my registered mobile number?

You must update your mobile number in Aadhaar or PAN records before downloading the e PAN Card.

Final Words 

Let’s be honest — in today’s fast-paced, digital-first world, waiting days for a piece of plastic feels ancient. The e PAN Card gives you the power to download your PAN instantly, anywhere, anytime, and without the red tape.

With just a few clicks, your PAN details are securely stored on your phone or PC, always within reach. No more fretting about losing it, carrying it, or even reapplying.

So the next time someone asks, “How do I download my e PAN Card?” — you’ll not only know the answer, you’ll ace it like a pro.

Now that you know the ropes, go ahead and download your e PAN Card today — it’s quick, it’s easy, and it’s 100% official.

✨ Quick Recap – e PAN Card Download in a Nutshell:

  • ✅ Use NSDL or UTIITSL portals
  • ✅ Or download via Aadhaar from the Income Tax site
  • ✅ Keep mobile, Aadhaar, and PAN details handy
  • ✅ Verify with OTP and download the PDF
  • ✅ e PAN is legal, fast, and free (in most cases)

It’s simple to download your e-PAN card from the Income Tax website, NSDL, or UTIITSL. To download your e-PAN card, you only require your acknowledgement number, PAN number, or Aadhaar number along with your date of birth. After downloading your e-PAN card, you may use it as identification for various financial transactions or other needs.
Car Loan Guide – Meaning, Features & Eligibility

0

Car is an expensive asset and it may not always be feasible to make a full payment on it. Car Loan gives you the facility of buying your preferred car through borrowing some money from a bank or a financial institution and paying them back through affordable EMIs within a definite period. The flexibility in the loan tenures, lower interest rates, and facilities of taking loan for purchasing both used and new cars have made it easy for the Indian population to buy a car through loan facility.

While selecting the right car loan, you must consider more factors other than just the interest rate. The amount of loan, down payment, processing fee, tenure of the loan, credit score, EMI and the total interest amount that you will pay are some other parameters that would help you in making your decision regarding which car loan to apply.

In this article, we will learn about the working of car loans, eligibility, interest rates, documentation, EMI calculation process, application process and the best way to select the car loan in India.

Car Loan

What’s a Car Loan?

A car loan is a financial instrument where you can buy a new or a used car but not in cash but in installments. Car loans are offered by banks, NBFCs, or any other financial institution to the eligible people who pay back the money borrowed along with interest through monthly EMIs over a certain tenure.

In most cases, the individual needs to pay an initial amount of money which will be a percentage of the total cost of the car and the rest of the amount will be paid back over a certain period of time through monthly EMIs.

A car loan helps you buy a vehicle at ease by dividing the cost of the vehicle through monthly payments. However, it is essential for the individual to compare the interest rate, processing charges, loan tenure, EMI, down payment amount, and other charges offered by different lenders before applying for a car loan.

Key Features of Car Loans

Interest Rates  

Let us begin with interest rates, which denote additional money paid for borrowed funds. These can either be fixed and remain constant for the whole period of the loan or variable and change depending on various factors. With a fixed interest rate, your payments will be predictable and quite stable; however, if they are variable, you may experience both drops and hikes that will affect your monthly payments in one way or another.

Loan Term

After this, there is the loan term which is a period when you have to pay off the debt. For auto loans, the period may range from 3 to 7 years, although there are longer ones as well. Shorter loan periods mean that you will be making larger monthly payments; nevertheless, you will be paying less interest. On the contrary, longer periods allow reducing payments but increase the interest cost.

Down Payment

The down payment is the first thing you should do before starting the process. It is the money you put aside as a down payment, typically 10-20% of the cost of the vehicle. The larger down payment you make, the smaller the amount you will have to take a loan for, and, consequently, your monthly payments will become lower, and interest paid on loans will also decrease. There are some lenders that provide you with zero-down options – sounds great, doesn’t it? Yet, be prepared to pay higher amounts later on.

Monthly Payments

Your monthly payment is a key aspect of your loan – how much you pay monthly to the lender. It depends on the amount of the loan, interest rate, and the term. The task here is to find an appropriate balance which won’t require too much effort from your part. After all, you have to save something for gas, insurance, and even coffee sometimes!

Fees 

Don’t forget about the fees! In some cases, the loan might have some additional charges such as an origination fee (a fee for setting up the loan), a late fee if you do not make a payment on time, or even an early repayment penalty. What a scam, right? Make sure to read the fine print!

Collateral 

And here is the catch—you use the vehicle as your collateral. It simply means that in case you fail to make the required payments, the creditor can seize it. It provides them with an additional safety measure.

Who’s Eligible for a Car Loan?

Car loan eligibility varies according to the lending institutions, but typically, banks and NBFCs provide car loans to salaried persons, self-employed individuals, and businessmen based on some requirements.

Car Loan Eligibility Requirements

  • Age – Typically, the applicant needs to be 18-21 years old, and the upper age limit is usually 60-70 years at the time of repayment of the loan.
  • Income – The applicant must have an adequate and regular source of income.
  • Job/Business Stability – Lenders would typically prefer an applicant who has a stable job/profession or business.
  • Credit Score – Having a good credit score might increase your chances of being approved for a car loan.
  • Residential Status – Indian resident and, under some conditions, NRIs can avail of various types of car loans.
  • Financial Obligations – Your EMI commitments, credit card payments, and other financial obligations are taken into consideration by the lenders while deciding your eligible loan amount.
  • Documents – You will require identity and residential proofs, income proofs, bank statement, and vehicle-related documents.

In general, the following people can apply:

  • Salaried employees of private firms, government organizations, or government departments.
  • Professionals who run their own practice like doctors, lawyers, consultants, and architects.
  • Owners of businesses and enterprises with an established business income stream.
  • Existing customers of banks and NBFCs, who may sometimes get pre-approved loans.

Being eligible to apply for a loan doesn’t mean that your application will be accepted by the lender. The bank can still analyze your credit record, salary, debt-to-income ratio, job stability, etc.

Different Types of Car Loans

Various kinds of car loans can be found based on the purpose or the type of loan taken by the borrower who wishes to buy a new or used car or any specific car. Factors like interest rate, amount of loan, tenure of loan, and eligibility criteria of the loan may differ according to the nature of loan taken and the financial institution providing the loan.

Following are some of the commonly known types of car loans in India:

1. New Car Loan

This type of loan is taken to buy a new car from the authorized dealerships of the car. Banks/NBFCs may provide a major part of the cost of the car whether on road or ex show room depending upon the terms and conditions of banks/NBFCs.

2. Used Car Loan

This kind of car loan is taken to buy a used car. Interest rate charged by the bank or NBFC may be higher because of factors such as age, condition, model, etc. of the car.

3. Electric Vehicle (EV) Car Loan

There are special car loans available for electric cars offered by some lenders who might provide good interest rates or have other incentives depending on the lender and the programs.

4. Pre-Approved Car Loan

A customer of the bank with an excellent credit score will be offered pre-approved car loan. This is a loan which could facilitate the process but is still subject to approval from the lender.

5. Car Loan for Self-Employed Individual

A businessman and self-employed individual can take out a car loan according to his income, stability of the business and credit rating and the ability to repay the loan. The lender could ask for extra documentation like income tax returns and business documentation.

6. Car Loan for Salaried Individual

The individuals who receive salaries can get car loans by taking into consideration their monthly salary, experience in job, credit history and debts. Salary slip and bank statement can be used for analyzing repayment ability.

7. Car Loan for Luxury Cars

A few financial institutes and banks offer loans that cater to purchasing luxurious cars. The conditions for such loans are usually different from other loans.

Conclusion

Getting a car loan will be an easy way of buying a new car or a used one since the cost of purchasing the vehicle will be divided into monthly installments. The car loans available include loan for buying a new car, loan for buying a used car, loan for buying electric cars, loan for a salaried individual and loan for a self-employed person, depending on the borrower.

Taking a car loan requires making a long-term financial plan for the future. Before applying for a car loan, it is necessary to compare the interest rates, loan term, processing fees, advance payment, foreclosure, total cost of loan repayment offered by various banks. Equally important is choosing an installment that you can afford per month.

It will be wise to take a loan and buy the car you want while maintaining good financial planning.

Fixed Deposit Laddering: A Strategy to Maximise Your Returns in 2025

Most individuals who look for stability in their investments choose instruments like Fixed Deposits (FDs). However, looking ahead to 2025, investing right is not just about choosing the most stable financial product but also strategising on how to maximise the returns one can earn from them. A smart approach to boost your returns is FD laddering. In this blog, we will explore the concept of FD laddering, highlighting its benefits and implementation for optimal financial growth.

Fixed Deposit Laddering

What is FD Laddering?

Fixed Deposit laddering is an investment strategy that divides a lump sum into multiple FDs of varying maturity periods instead of placing all funds into a single fixed deposit.

For instance, if you invest INR 5 lakh, you could allocate INR 1 lakh each in 1-year, 2-year, 3-year, 4-year, and 5-year FDs. As each FD matures, you gain liquidity and can reinvest the same funds at current interest rates. In this way a portion of your savings remains accessible while still benefiting from higher interest rates on long-term deposits.

How to Implement FD Laddering

  • Determine Your Investment Horizon: Begin by evaluating your financial goals and timelines. Assess your short-term liquidity needs along with potential future expenses and risk factors. This helps ensure you have accessibility to funds when needed. 
  • Divide Funds into Segments: Allocate your total investment into multiple segments, each corresponding to a fixed deposit with varying maturity periods. This segmentation creates a ladder-like structure where you can spread the funds.
  • Select Maturity Periods: Choose maturity periods that suit your financial plans. For instance, one deposit could mature in one year, while another could mature in two and continue this pattern.
  • Maintain Consistency: Regularly assess the maturity dates of your FDs and reinvest both the principal and accrued interest into new FDs with longer maturities. As interest rates fluctuate or your financial goals change, adjust your ladder accordingly by reinvesting in different tenures for better returns.

Benefits of FD Laddering

  • Better Liquidity: The varying maturities of the FDs provide regular access to funds, ensuring greater liquidity and flexibility for short-term financial needs without the need to break long-term deposits prematurely.
  • Tax Efficiency:  By spreading out FD maturities across different financial years, you can effectively manage tax liabilities, potentially keeping your taxable income within a lower bracket each year.
  • Consistent Income: With different FDs maturing at regular intervals, you create a steady income stream. This is especially beneficial for retirees who rely on consistent income. It allows them financial flexibility without a long-term commitment.
  • Optimised Returns: Diversifying your investments across various FDs with different maturity dates allows you to capitalise on changing interest rates. By combining short and long-term FDs, you can earn better overall returns compared to investing in just one type of deposit.
  • Reduced Reinvestment Risk:  Reinvestment risk comes into play when you have to reinvest the money from a matured fixed deposit at a lower interest rate than before. In FD laddering, since only a portion of your total investment matures at any given time, you can reinvest at current market rates without adversely impacting the total returns.
  • Fosters Financial Discipline:  FD laddering encourages long-term planning and prevents impulsive withdrawals, helping you stay aligned with your financial objectives and reducing unnecessary expenses.

Unlock the Full Potential of Your Investments: Explore FD Laddering

When considering fixed deposit laddering, it’s essential to pay attention to the segmentation, maturity periods, and interest rates. Avoiding premature withdrawals is crucial to fully reap the benefits of this approach. By reinvesting whenever your FD matures, you can create a continuous cycle of growth and enhance your financial stability.

If you’re in search of a feature-rich FD, IndusInd Bank offers attractive fixed deposits with flexible tenures. Enjoy competitive fixed deposit interest rates and the convenience of an auto-renewal option. Additionally, you can save significantly through IndusInd Bank’s 5-year tax-saver FDs. Open an FD online in just three easy steps, plan your FD laddering scheme and make the most of your money!

10 Clever Ways for Making Money in Real Estate

Let’s face it—real estate’s always had this irresistible charm. There’s just something about bricks and mortar that screams stability, security, and serious cash. From rags-to-riches landlords to those “accidental investors” who flipped a house at the right time—making money in real estate has become the ultimate dream for many.

But hold your horses! Before you start visualizing yourself sipping cocktails in your sea-facing penthouse, you need to know the how behind the wow. And that’s exactly what we’re diving into today.

So whether you’re a complete newbie, a semi-pro investor, or just plain curious—this article lays out the 10 best ways for making money in real estate, minus the jargon and with a whole lot of real talk.

Making Money Real Estate

10 Best Ways to Make Money in Real Estate

1. Rental Properties: The Evergreen Money-Maker

When people say “real estate investment,” chances are they’re thinking about good old rental properties. And it’s not just hype—rental income is the bread and butter of many real estate moguls.

Why it works:

  • Regular monthly income (a.k.a. passive cash flow!)
  • Property value typically appreciates over time
  • Tax benefits galore!

Tips to make it work:

  • Choose the right location (schools, jobs, amenities)
  • Vet your tenants (bad ones = nightmares!)
  • Maintain the property well to avoid legal trouble

Pro tip: Start small with a single-family home or a condo, and then scale your rental empire.

2. House Flipping: Quick Profits, If You Play it Smart

Seen those flashy YouTube videos where someone flips a house in 90 days and walks away with ₹25 lakhs? Yep, that’s house flipping.

You buy low, fix it up, sell high. Easy? Not quite. Profitable? Absolutely—if done right.

How to flip successfully:

  • Find undervalued properties (foreclosures, distressed sales)
  • Know your renovation budget and timeline
  • Sell in a hot market for a fat profit

Warning: This isn’t for the faint-hearted. Market crashes, construction delays, or over-renovation can eat into your returns.

3. REITs (Real Estate Investment Trusts): Real Estate on Autopilot

Not everyone wants to deal with tenants or tiles. If you’d rather invest in real estate without buying property, REITs are your jam.

What’s a REIT?

A REIT is a company that owns or finances income-producing real estate. You can invest in them just like stocks.

Benefits:

  • Low entry barrier (start with as little as ₹500!)
  • Diversified portfolio exposure
  • High liquidity (buy/sell anytime)

Ideal for: People who want to dip their toes in real estate without getting their hands dirty.

4. Short-Term Vacation Rentals: Airbnb-Style Income

Want a taste of hospitality with your investment? Renting out your property on platforms like Airbnb or Vrbo can be incredibly lucrative.

Why short-term rentals shine:

  • Higher nightly rates than traditional rentals
  • More flexibility (use it yourself when it’s vacant!)
  • Great for tourist-heavy locations

What to watch out for:

  • Frequent maintenance and cleaning
  • Regulatory hurdles in certain cities
  • Seasonal fluctuations

Insider trick: Design your place Instagram-worthy—people love staying where they can snap a good selfie.

5. Real Estate Crowdfunding: Power of the People

Can’t afford to buy an entire property yourself? Join the crowd—literally. Real estate crowdfunding platforms let you invest alongside others in big projects.

Here’s how it works:

  • You pool your money with hundreds of other investors
  • A professional team manages the project (commercial, residential, etc.)
  • You earn dividends or profits based on your share

Pros:

  • Low investment threshold
  • Diversify across locations and property types
  • Hands-free involvement

Best for: Beginners who want to start small and learn the ropes.

6. Pre-Construction Investments: Buy Early, Profit Big

Imagine buying an apartment before it’s even built—and then watching its value skyrocket by the time it’s ready. Sounds like magic, right?

The upside:

  • Prices are lowest during the pre-launch phase
  • You can lock in better deals and payment plans
  • Potential for high appreciation by possession

But beware:

  • Project delays
  • Builder credibility matters
  • Risk of market slowdown

Golden rule: Always check the builder’s track record and RERA registration before signing anything!

7. Real Estate Wholesaling: Zero Ownership, Zero Hassle

Here’s a cheeky one—make money in real estate without actually buying anything!

What’s wholesaling?

  • You find a distressed or motivated seller
  • You put the property under contract
  • You flip the contract to a buyer for a profit

Why it works:

  • No need to invest your own money
  • Fast transactions, quick cash
  • Great learning curve for real estate negotiation

Heads-up: You’ll need great networking skills and a nose for good deals.

8. Commercial Real Estate: Big Bucks for Big Thinkers

If residential real estate feels a bit too vanilla, commercial real estate might tickle your fancy.

Think office spaces, retail stores, warehouses, etc.

Why commercial rocks:

  • Higher rental yields than residential
  • Long-term leases (less vacancy stress)
  • Tenants often handle interior maintenance

The flipside:

  • High initial investment
  • More legal and regulatory hoops
  • Market is closely tied to economic cycles

Hot tip: Co-working spaces and shared warehouses are booming in Tier 1 and Tier 2 Indian cities.

9. Co-Living or PG Spaces: Modern Twist on Old-School Boarding

With urban migration soaring, especially among students and young professionals, co-living spaces have become a sweet spot for investors.

What makes it lucrative:

  • Shared spaces = higher returns per square foot
  • Predictable demand in student hubs or tech parks
  • Monthly rental + services = higher income streams

Must-dos:

  • Offer good WiFi, clean bathrooms, and security
  • Use tech platforms for bookings and management
  • Keep up with hygiene and reviews

Reality check: Treat it like a hospitality business, not just a rental.

10. Land Banking: Buy Dirt, Get Rich Slowly

Last but not least—land banking is all about buying land now and cashing in big later.

Why it’s smart:

  • No maintenance costs
  • High appreciation potential in developing zones
  • Can be converted into commercial, residential, or industrial plots

But it’s not instant noodles:

  • Might take years before it yields results
  • Legal checks (titles, zoning, disputes) are crucial
  • Returns are not monthly but massive over time

Best strategy: Buy on the outskirts of fast-growing cities and hold for 5–10 years.

FAQs – All About Making Money in Real Estate

1. Can I start making money in real estate with little or no money?

Yes! Try real estate wholesaling, REITs, or crowdfunding platforms. These require minimal or no capital investment.

2. What’s the riskiest method on the list?

House flipping can be risky due to market unpredictability and renovation delays. Always budget for surprises.

3. Is making money in real estate passive or active?

It depends. Rentals and REITs can be passive, while flipping or co-living setups require hands-on involvement.

4. How do I pick the right city for investing in India?

Look for cities with:

  • Growing job markets (like Bengaluru, Hyderabad)
  • Infrastructure development (metro, expressways)
  • Rising rental yields and housing demand

5. Can I lose money in real estate?

Absolutely. Poor location, bad tenants, legal troubles, or market crashes can eat into your profits. Always research and plan.

Conclusion 

There you have it—the 10 best ways for making money in real estate that are working right now, especially in 2025. Whether you’re playing it safe with REITs or going bold with co-living spaces, there’s no one-size-fits-all.

But here’s the real deal—real estate is not a lottery ticket. It takes patience, planning, and persistence. Do your homework, take baby steps if needed, and don’t let FOMO rush your decisions.

After all, as the old saying goes, “Don’t wait to buy real estate. Buy real estate and wait.”

So, which of these methods are you excited to try first? Ready to take that first step toward making money in real estate?