Blog Page 62

7 Steps to Take Immediately After an Unexpected Job Loss

0

There’s no sugar-coating it: losing your job without warning can be one of the most disorienting and stressful financial experiences. Whether it’s due to redundancy, company restructuring, or a sudden downturn, the emotional weight is matched only by the practical pressure of keeping your head above water.

But panic doesn’t pay the bills—action does. Here’s a step-by-step approach to stabilise your situation, protect your finances, and begin rebuilding your career momentum.

after Job Loss

1. Take Stock of Your Finances

Before anything else, open your banking app or log into your internet banking and go through your last month of transactions. Note:

  • What’s coming in (final pay, tax refund, any Centrelink payments)
  • What’s going out (mortgage/rent, utility bills, subscriptions, food)

Use this to create a basic cash flow overview. Tools like the Moneysmart budget planner or Frollo can help automate this process, pulling in real-time data from all your accounts.

Goal: Understand how long you can realistically sustain your current lifestyle with existing savings.

2. Apply for Government Support Immediately

Don’t wait. File a claim through myGov for:

  • JobSeeker Payment: For those actively looking for work
  • Rent Assistance: If you’re a tenant
  • Energy Supplement or Crisis Payment (in some cases)

The Services Australia site can be confusing, so make use of community legal centres or welfare advocacy groups if you need help navigating it. Processing times can take weeks, so the sooner you start, the better.

3. Manage Existing Debts and Essential Bills

This is where things can start to snowball if not handled carefully. Begin by contacting your:

  • Bank: Ask about financial hardship programs, loan pauses or repayment adjustments
  • Energy and telco providers: Request hardship support or bill smoothing
  • Landlord or mortgage broker: Explain your situation, ask for a temporary rent reduction or deferment

Losing your income can, unfortunately, impact your credit score if you begin missing payments. If you need to consolidate high-interest debts to lower your monthly outgoings or cover a large, essential expense during this period, traditional lenders may be hesitant. This is a situation where researching options like large loans for bad credit becomes a practical step for survival and financial restructuring.

Some providers of bad credit personal loans in Australia offer more flexible approval criteria, assessing your current ability to repay rather than solely relying on your credit history. But always review the comparison rate, fees, and loan term carefully to avoid locking yourself into a worse position later.

4. Pause Non-Essentials and Reassign Your Budget

Now is the time to shift into crisis budgeting mode—not forever, but just to get through the transition.

Pause:

  • Streaming services
  • Subscription boxes
  • Gym memberships
  • Delivery apps

Redirect that money towards:

  • Rent or mortgage
  • Utilities
  • Groceries
  • Emergency travel or medical needs

This is also a great time to lean on tools like Pocketbook or WeMoney to get visibility over where your money is leaking.

5. Tap Into Redundancy or Superannuation (If You Have To)

If your redundancy package included a payout, prioritise using it for necessities and debt management, not lifestyle.

In some cases, you may be eligible to access your superannuation early under compassionate grounds or severe hardship, but this comes with long-term retirement trade-offs. Always speak to a financial counsellor before making this call. The National Debt Helpline (1800 007 007) offers free, confidential advice.

6. Rebuild Your Career Narrative

Don’t jump into job applications blindly. First, get your documents in order:

  • Resume (update roles, skills, measurable achievements)
  • Cover letter templates
  • LinkedIn profile (set to “Open to Work”)

Then, reflect: What kind of role are you really looking for now? Do you want to stay in the same industry? Would short-term contracting or casual work help stabilise things?

Look into:

  • gov.au
  • Seek & Indeed with saved keyword alerts
  • Upwork or Airtasker for freelance or short gigs

You might also explore retraining options or government-subsidised upskilling through TAFE or Skills Checkpoint.

7. Prioritise Mental and Physical Wellbeing

Financial stress has a way of bleeding into everything—relationships, sleep, and even physical health. Keep your daily rhythm:

  • Get dressed each morning
  • Go for a walk or move your body
  • Eat consistently, even if cheaply
  • Keep talking to friends or support groups

If you’re feeling overwhelmed, services like Beyond Blue, Head to Health, and local community mental health programs are just a phone call away.

This isn’t just about getting a job again—it’s about surviving this season intact.

Final Word

An unexpected job loss can feel like the ground has shifted beneath you, but it doesn’t mean your financial footing is gone for good. The key is to take things one step at a time.

Start by getting a clear picture of your budget so you know exactly where you stand. From there, secure the support available to you, whether that’s government assistance, hardship programs, or help from community services. It’s also important to protect your credit—missing payments now could limit your options later, so communicate early with lenders or explore short-term restructuring. Stay open to different types of work, even if they don’t align perfectly with your past roles. Most of all, don’t isolate yourself. Staying connected—to your finances, to the people around you, and your sense of purpose—can make all the difference.

A new opportunity will come. For now, focus on what you can control and take small, steady actions that move you forward.
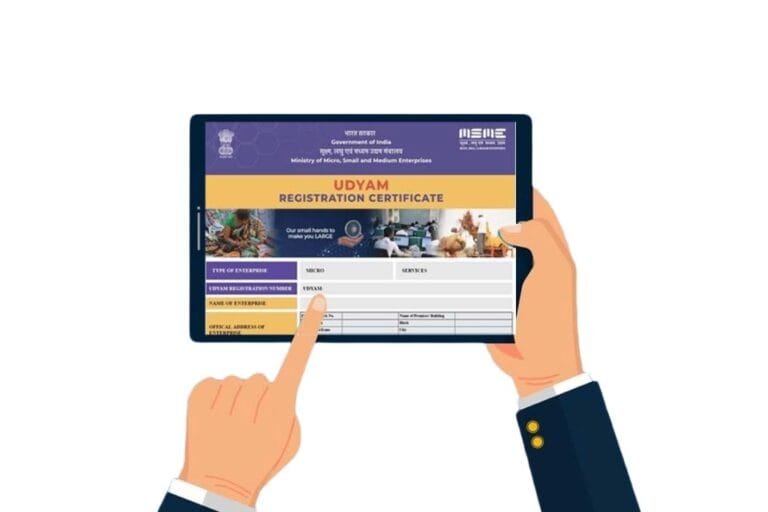
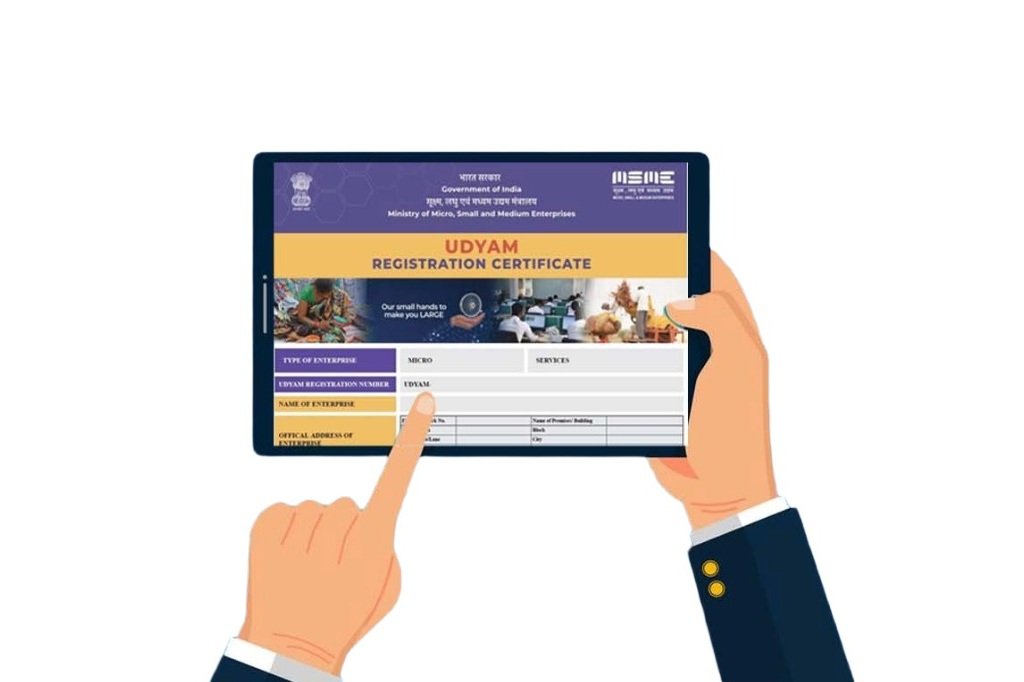
Udyam Registration Certificate in India – How to Register?

Hey, if you’re a small business owner in India, you’ve probably heard the buzz about Udyam Registration. It’s that golden ticket, y ou know, the one that officially stamps your enterprise as a Micro, Small, or Medium Enterprise (MSME). But let’s face it, navigating government procedures can feel like wading through molasses – slow and sticky! Don’t worry, though; this article’s got your back. We’re diving deep into the Udyam Registration Certificate in India, explaining how to register without breaking a sweat.

Launched back in 2020 by the Ministry of Micro, Small and Medium Enterprises, Udyam Registration replaced the old Udyog Aadhaar system. It’s all online now, super streamlined, and hey, it’s free! Whether you’re starting a cozy cafe or scaling up a manufacturing unit, getting this certificate opens doors to loans, subsidies, and protections that can make your business thrive. By the end, you’ll know the ins and outs, from eligibility to troubleshooting common hiccups. Excited? Let’s jump right in!

Udhyam Certificate Register

What Exactly is Udyam Registration?

Picture this: You’re running a little shop, hustling day in and day out, but without official recognition, you’re missing out on a ton of perks. That’s where Udyam Registration comes in – it’s basically the government’s way of saying, “We see you, and we’ve got tools to help you grow!”

The Basics of Udyam Registration

At its core, Udyam Registration is a simple online process for classifying businesses as MSMEs. Based on your investment in plant and machinery or equipment, plus your annual turnover, you get slotted into micro, small, or medium categories. For instance, a micro enterprise might have investments up to Rs. 1 crore and turnover up to Rs. 5 crore. These thresholds got a refresh in recent years, making it easier for more folks to qualify.

Why bother, you ask? Well, once registered, you snag a unique Udyam Registration Number (URN) and a certificate that’s like your business’s ID card. It’s valid forever, no renewals needed – talk about a relief! And get this: It’s integrated with Aadhaar and PAN, so no more endless paperwork.

Evolution from Old Systems

Remember the days of SSI registration or EM-I/II? Those are ancient history now. Udyam Registration streamlined everything under one umbrella, cutting red tape. Launched amid the pandemic, it was a game-changer, helping businesses bounce back with easier access to credit. If you’re transitioning from the old Udyog Aadhaar, you can re-register seamlessly on the Udyam portal.

Why Should You Go for Udyam Registration?

Okay, so you’re thinking, “Is this really worth my time?” Absolutely! The benefits are like hidden treasures waiting to be unearthed. Let’s break it down.

Key Benefits of the Udyam Registration Certificate

First off, financial perks galore. Banks offer collateral-free loans under schemes like Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE). Interest rates? Often lower, saving you bucks in the long run. Plus, subsidies on patents, ISO certifications, and even electricity bills – who wouldn’t want that?

Protection-wise, you’re shielded from delayed payments. Suppliers can’t drag their feet beyond 45 days without owing interest. And in tenders, MSMEs get exemptions from earnest money deposits. Wow, that levels the playing field against big players!

Boosting Your Business Growth

Beyond money, Udyam Registration opens networking doors. You can join government e-marketplaces (GeM) for direct procurement opportunities. Exporting? Get reimbursements on expenses through schemes like Market Development Assistance. It’s like giving your business a turbo boost!

And don’t forget the pride factor. Having that certificate screams legitimacy, attracting investors and customers alike. In a competitive market, standing out is key, right?

Who Can Apply for Udyam Registration?

Not everyone’s eligible, but the criteria are pretty inclusive. Let’s see if you fit the bill.

Eligibility Criteria Explained

Any enterprise – proprietorship, partnership, company, or even Hindu Undivided Family – can apply, as long as it’s in manufacturing or services. The catch? Your investment and turnover must fall within MSME limits:

  • Micro Enterprises: Investment ≤ Rs. 1 crore; Turnover ≤ Rs. 5 crore.
  • Small Enterprises: Investment ≤ Rs. 10 crore; Turnover ≤ Rs. 50 crore.
  • Medium Enterprises: Investment ≤ Rs. 50 crore; Turnover ≤ Rs. 250 crore.

Note: These figures include exports but exclude certain items like retail trade in some cases. If you’re a trader, recent updates might include you under services – check the portal for the latest.

Special Cases and Exclusions

What if you’re already registered under Udyog Aadhaar? You need to migrate by a deadline, but it’s straightforward. Startups, beware: While Udyam helps, it’s separate from DPIIT recognition for tax benefits.

Exclusions? Big no for enterprises in mining, forestry, or those exceeding limits. Also, if you’re a foreign entity, local rules apply. Dangling on the edge of thresholds? Better calculate accurately to avoid rejections.

How to Register for Udyam Registration Certificate in India

Alright, the meat of the matter – how to actually get this done. It’s online, so grab your laptop and let’s roll!

Preparing Before You Start

Before diving in, gather your docs. You’ll need:

  • Aadhaar number (mandatory for proprietors; PAN and GSTIN for others).
  • PAN of the enterprise.
  • Bank details (IFSC, account number).
  • Investment and turnover figures (self-declared, but be honest!).
  • Business address and contact info.

No uploads required – it’s all self-certification. But hey, keep records handy for future audits.

Navigating the Udyam Portal

Head to udyamregistration.gov.in. It’s user-friendly, but if you’re tech-shy, no sweat – follow these steps:

  1. Click on ‘New Registration’: For fresh applicants. If migrating, choose the option for Udyog Aadhaar holders.
  2. Enter Aadhaar and Validate: OTP comes to your phone. Easy peasy!
  3. Fill Enterprise Details: Name, type, address, etc. Select NIC code for your activity – there’s a search tool if you’re unsure.
  4. Investment and Turnover: Input numbers. System classifies you automatically.
  5. Bank and Other Info: Add IFSC, account, and any social categories (SC/ST/Women-owned) for extra benefits.
  6. Verify and Submit: Double-check, get another OTP, and boom – your URN is generated!

The certificate downloads instantly. Print it, frame it if you want – you’ve earned it!

Common Mistakes to Avoid During Registration

Rushing through? Big mistake! Typos in Aadhaar or PAN can lead to rejections. Overstating turnover? That could bite you later during verifications. And forgetting to update if your business grows? You’ll need to re-classify.

If stuck, the portal has helplines. Or, walking into a District Industries Centre, experts there can guide you for free.

Documents Required for Udyam Registration

We touched on this, but let’s expand. Since it’s self-declaration, minimal docs, but accuracy matters.

  • Mandatory: Aadhaar (individual) or PAN/GSTIN (entity).
  • Optional but Helpful: Partnership deed, MoA/AoA for companies, bills for investment proof (though not uploaded).

For updates later, like changing address, log in with URN and edit. Simple, right?

After Getting Your Udyam Registration Certificate: What Next?

Congrats! But the journey doesn’t end there. Let’s talk maintenance and maximization.

Updating Your Udyam Details

Business evolving? Update annually by April 1st with latest turnover. Miss it? No biggie, but do it to stay compliant. Re-classification happens automatically if you cross thresholds.

Leveraging the Certificate for Schemes

Now, apply for goodies! Head to schemes like PMEGP for loans or ZED for quality certifications. Track tenders on MSME Samadhaan portal. It’s like unlocking a treasure chest – dive in!

Common pitfall: Not monitoring emails. The portal sends updates, so stay alert.

Challenges and Troubleshooting in Udyam Registration

Not everything’s smooth sailing. Let’s address bumps in the road.

Technical Glitches and Fixes

Portal down? Try later or use incognito mode. OTP not coming? Check network or Aadhaar linkage. If all fails, email support at udyam@msme.gov.in – they’re responsive.

Handling Rejections or Errors

Wrong classification? Re-apply with corrections. Duplicate registrations? Merge them via the portal. And if audited, have proofs ready – transparency’s key.

FAQs

Q1: Is Udyam Registration mandatory?

Not for all businesses, but if you want MSME benefits, it’s essential.

Q2: How long does it take to get the certificate?

Usually within minutes if your details match.

Q3: Do I need GST for Udyam Registration?

If your business is GST-eligible, yes—it’ll auto-fetch your details.

Q4: Can I register more than one business?

Yes, but each business needs a separate Udyam Registration.

Q5: Does the certificate expire?

No, it’s valid for a lifetime unless your business outgrows MSME limits.

Conclusion

Wrapping up, the Udyam Registration Certificate in India isn’t just paperwork – it’s a launchpad for your business dreams. From easing loans to shielding against delays, the perks are endless. We’ve walked through how to register, sidestepped pitfalls, and even shared success tales. So, what are you waiting for? Head to the portal, get your Udyam Registration done, and watch your enterprise soar!

Remember, in the world of MSMEs, being registered is like having a superpower.  

Direct Benefit Transfer – DBT Beneficiary and Payment Status Check

As a beneficiary of any government program, including the PM Kisan scheme, LPG subsidy, or state welfare initiatives, you can verify your DBT payment status online to see if you have received the payment directly in your bank account.

Ever found yourself scratching your head, wondering where your government subsidy is or if you’re even eligible for it? You’re not alone. With over a billion people and numerous welfare schemes in India, staying in the loop about DBT beneficiary and payment status checks can feel like navigating a maze.

But don’t sweat it! We’re breaking it down for you—step-by-step—in the simplest language possible. Whether you’re a farmer waiting for a PM-Kisan installment, a student expecting a scholarship, or just someone looking to understand how Direct Benefit Transfer (DBT) works, this guide’s for you.

Let’s pull back the curtain on how to check your DBT status, what it means to be a DBT beneficiary, and why your money might be taking its sweet time.

DBT - Direct Benefit Transfer

What Is DBT and Who’s a DBT Beneficiary?

DBT, short for Direct Benefit Transfer, is a government initiative in India that aims to send subsidies and financial benefits directly to the bank accounts of eligible citizens. It reduces middlemen, delays, and corruption. Pretty slick, right?

Here are a few common schemes that fall under the DBT umbrella:

  • PM-KISAN (for farmers)
  • LPG Subsidy (PAHAL Scheme)
  • Scholarships (for school/college students)
  • MGNREGA (for rural employment)
  • Janani Suraksha Yojana (maternity support)

If you’re registered and qualified for any of these, you’re what we call a DBT beneficiary.

Who Can Be a DBT Beneficiary?

A DBT beneficiary is someone who has:

  • Enrolled in a DBT-enabled scheme
  • Linked their Aadhaar number with their bank account
  • Verified their identity through Know Your Customer (KYC)
  • Fulfilled scheme-specific eligibility criteria

If that’s you—congrats, you’re in the club!

Why DBT Matters More Than Ever

DBT isn’t just about convenience—it’s a game-changer for transparency and efficiency in welfare distribution. Here’s why it’s worth your attention:

  • Instant payments: No waiting weeks or months for benefits.
  • Reduced fraud: No middlemen means fewer scams.
  • Better targeting: Only verified, eligible people receive funds.
  • Eco-friendly: Say goodbye to paperwork and manual processing.

DBT Payment Status Verification

On January 1, 2013, the Government of India launched the Direct Benefit Transfer (DBT) to deliver subsidies from Central and State Government schemes straight to the accounts of beneficiaries. It allows beneficiaries to verify fund distributions for any government programs without needing intermediaries. Thus, it guarantees that only the account of the beneficiaries gets the funds without any corruption.

How to Verify DBT Payment Status?

Step 1: Access the DBT Status Tracker on the PFMS Portal.

Step 2: Choose the Category, set ‘DBT Status’ to ‘Payment’ and input your bank name.

Step 3: Input your Bank Account Number, Application ID, or Beneficiary Code.

Step 4: Enter the Captcha code displayed on the screen.

Step 5: Press ‘Search’ to check your DBT payment status.

How to Verify DBT Beneficiary Status?

You can conveniently verify your DBT beneficiary status by following these simple steps:

Step 1: Access the DBT Status Tracker through the PFMS Portal.

Step 2: Choose the Category, set ‘DBT Status’ to ‘Beneficiary Validation’ and specify your bank’s name.

Step 3: Input your Bank Account Number, Application ID, or Beneficiary Code.

Step 4: Input the Captcha code shown on the screen.

Step 5: Press ‘Search’ to verify the status of your DBT beneficiary validation.

How to Verify Linked Account in DBT?

You can use the process outlined below to verify your DBT link account:

Step 1: Go to the official UIDAI website.

Step 2: Go to the ‘My Aadhaar’ section and choose the ‘Bank Seeding Status’ option found in the ‘Aadhaar Services’ area.

Step 3: On the following page, select the ‘Bank Seeding Status’ tab.

Step 4: Input your Aadhaar number, the Captcha code shown on the screen, and click ‘Login With OTP’.

Step 5: Input the OTP and press ‘Login’. Select the ‘Bank Seeding Status’ section.

Step 6: The status of your bank account linked to Aadhaar DBT will appear on the screen.

DBT Status for Aadhaar Bank Link

To verify the status of your Aadhar-DBT Bank link, you can utilize the following procedure:

Step 1: Go to the official UIDAI website.

Step 2: Go to the ‘My Aadhaar’ section and choose the ‘Bank Seeding Status’ option found under ‘Aadhaar Services’.

Step 3: On the following page, select the ‘Bank Seeding Status’ tab.

Step 4: Input your Aadhaar number, the Captcha code shown on the screen, and select ‘Login With OTP’.

Step 5: Input the OTP and press ‘Login’. Select the ‘Bank Seeding Status’ option.

Step 6: The status of your bank account linked to Aadhaar DBT will appear on the screen.

DBT Status Verification with Mobile Number

Step 1: Access the Payment Page on the PFMS Portal.

Step 2: Input your Bank name, Account number, Captcha code, and press ‘Send OTP via SMS’.

Step 3: Input the OTP received on your mobile for confirmation.

Step 4: Choose the government program (e.g., PM-KISAN, LPG subsidy) for which you wish to verify the payment status.

Step 5: Once verified, the portal will display your DBT payment information.

Popular DBT Programs

The DBT initiatives comprise a variety of programs executed by both the national and state authorities. Here is a comprehensive list of various DBT schemes that you can utilize as needed.

Direct Benefit Transfer (DBT) increases transparency and improves the payment methods of government welfare programs. Under DBT, benefits and payments from government schemes will be directly credited to the beneficiaries’ accounts. You can conveniently verify your DBT payment status online via the PFMS website and confirm that you have received the payment promptly.

Common DBT Beneficiary Issues (And Fixes)

Even though DBT is a major step forward, hiccups do happen. Here’s what might be messing things up and how you can fix it:

1. Aadhaar Not Linked with Bank

  • Visit your bank branch with Aadhaar and PAN
  • Fill out the linking form or request Aadhaar seeding via mobile banking

2. KYC Not Completed

  • Complete eKYC via PM-Kisan portal or in person at CSC
  • Make sure biometric verification is successful

3. Incorrect Bank Details

  • Update your bank information on the scheme’s portal
  • Confirm with your bank that your account is active and functional

4. Payment Under Process

  • Be patient—sometimes delays happen due to backend processing
  • Check again in a few days

FAQs

Q1: How do I know if I’m a DBT beneficiary?

A: If you’ve registered and been approved for a DBT-linked scheme (like PM-Kisan or LPG subsidy), you’re officially a DBT beneficiary. Check on the relevant scheme portal using your Aadhaar or bank details.

Q2: What if my DBT payment is showing “Pending”?

A: It could be due to Aadhaar issues, KYC problems, or technical delays. Recheck your KYC, confirm Aadhaar seeding, and wait a few days before escalating.

Q3: Can I update my bank account for DBT online?

A: Yes! Most schemes let you update bank details via their official websites or mobile apps.

Q4: What if my name is spelled wrong in the DBT portal?

A: Visit your nearest CSC or bank to update your name. Use the same spelling as on your Aadhaar card.

Q5: How frequently should I check my DBT status?

A: Once a month is ideal, but especially around scheduled payment dates.

Conclusion

Being a DBT beneficiary isn’t just about receiving money—it’s about empowerment, inclusion, and trust in the system. Whether you’re a farmer, student, homemaker, or worker, the DBT system ensures that what’s rightfully yours gets to you—on time and without hassle.

And now that you know how to check your DBT beneficiary and payment status, you’re in control.

So, don’t wait around! Check your status, update your details, and make sure you’re getting every rupee you’re entitled to. Government support is just a few clicks away.

Everything You Need to Know About Internal vs External Auditors for UK Companies

As a UK business owner, understanding the differences between internal and external auditors is crucial for maintaining a robust financial system and ensuring compliance with legal and regulatory requirements. While both types of auditors play essential roles in your business, their functions, objectives, and scope of work differ significantly.

In this guide, we’ll break down everything you need to know about internal and external auditors, and help you understand which one your company needs, depending on your goals and business needs.

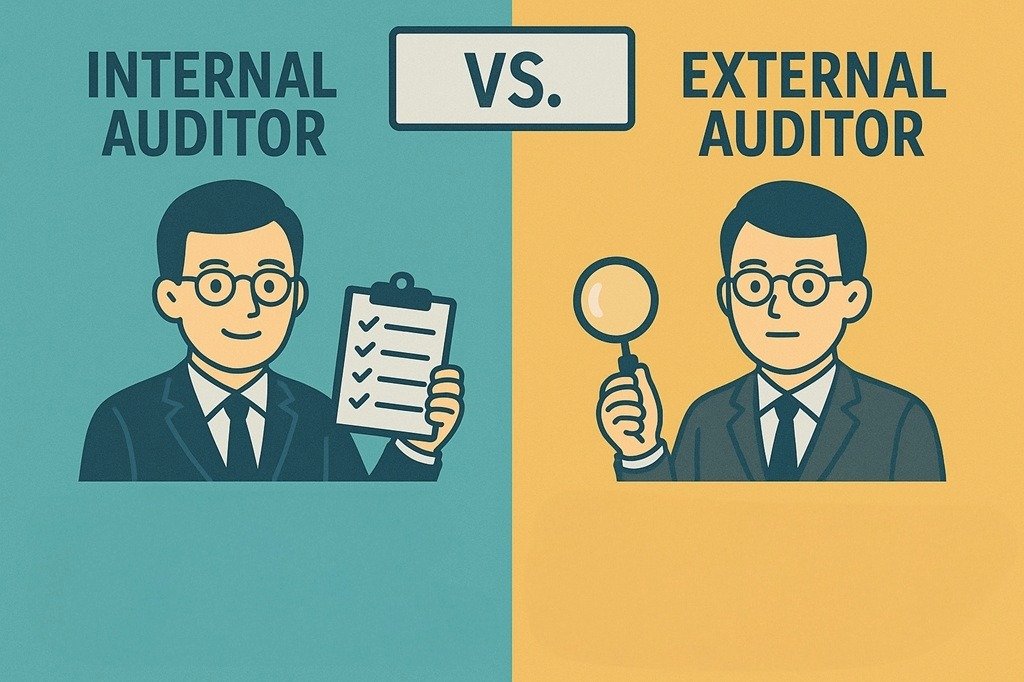
Internal vs External Auditor

What is an Internal Auditor?

An internal auditor is an employee within your company who evaluates and improves the effectiveness of your internal controls, risk management, and governance processes. The primary focus of an internal auditor is to help your business operate more efficiently and safeguard its assets, rather than providing an independent opinion on financial statements.

Key Responsibilities of an Internal Auditor:

  • Assessing Internal Controls: Internal auditors review your company’s internal controls to ensure they are effective in preventing fraud, errors, and mismanagement. They check whether financial transactions are properly authorised and recorded.
  • Identifying Risks: They help identify operational, financial, and compliance risks that could impact the business’s performance and suggest ways to mitigate them.
  • Improving Business Processes: Internal auditors focus on making recommendations for improving business processes, efficiency, and cost savings. This could include streamlining operations or implementing better accounting software.
  • Compliance Monitoring: They monitor compliance with laws and regulations relevant to your industry and ensure that your company is adhering to both internal policies and external legal requirements.
  • Ongoing Monitoring: Internal auditors are part of your business on an ongoing basis, regularly assessing business operations and financial records.

Benefits of an Internal Auditor:

  • Provides continuous oversight of company activities.
  • Helps identify inefficiencies and improve business processes.
  • Provides insight into risk management and ensures compliance with internal policies.
  • Offers cost-effective guidance for improving operations.

Tip: If you’re looking for someone to consistently monitor internal processes, flag potential issues before they become problems, and improve your operations over time, an internal auditor is the right choice.

What is an External Auditor?

An external auditor, on the other hand, is an independent third party (usually from a firm) that is hired to conduct an audit of your company’s financial statements and provide an objective assessment. The primary focus of an external auditor is to ensure that your financial records are accurate, compliant with regulations, and provide a fair representation of your business’s financial health.

Key Responsibilities of an External Auditor:

  • Independent Financial Review: External auditors assess your business’s financial statements to determine whether they accurately reflect the financial position of your company. This includes verifying the accuracy of balance sheets, income statements, and cash flow statements.
  • Legal and Regulatory Compliance: They ensure that your financial statements comply with UK accounting standards, such as UK GAAP or IFRS, and are in line with regulatory requirements set by HMRC and other authorities.
  • Providing Assurance to Stakeholders: An external auditor provides an independent opinion on the fairness of your company’s financial records, which is important for stakeholders such as investors, creditors, and lenders.
  • Detecting Fraud or Misstatements: External auditors are trained to detect fraud, misstatements, or other irregularities in financial records and highlight areas where your company may be at risk.

Benefits of an External Auditor:

  • Provides independent verification of financial statements.
  • Enhances trust with investors, lenders, and regulatory bodies.
  • Provides objective feedback and highlights areas for improvement.
  • Ensures legal and regulatory compliance to avoid penalties.

Tip: If your business is looking for an independent, unbiased review of its financial health, especially to provide confidence to external stakeholders, then an external auditor is essential.

Key Differences Between Internal and External Auditors

While both internal and external auditors assess financial records, they differ significantly in their approach, objectives, and scope. Here’s a breakdown of the key differences between internal and external auditors for UK companies:

Aspect Internal Auditor External Auditor
Independence Not independent (employee of the company) Independent third party
Focus Internal controls, risk management, and process improvement Financial statement accuracy, compliance, and fairness
Scope Ongoing, broad evaluation of operations Limited to annual financial audit
Reporting Reports to management or board of directors Reports to stakeholders (shareholders, investors, regulators)
Frequency Continuous or periodic audits throughout the year Typically once a year for the audit of financial statements
Goal Improve internal processes, prevent fraud, and manage risks Provide an independent opinion on the accuracy of financial records

Tip: If your business is looking for comprehensive, ongoing monitoring and improvement of operations, an internal auditor is ideal. However, for an unbiased evaluation of your financial statements for external stakeholders, an external auditor is necessary.

When Do You Need an Internal Auditor?

Not all businesses need an internal auditor, especially if they are small or just starting out. However, if your business is growing in complexity, has multiple departments, or operates in a highly regulated industry, an internal auditor can provide substantial value.

When You Should Consider an Internal Auditor:

  • Large Companies: As your business grows, the complexity of managing financial operations increases. An internal auditor helps monitor and improve your internal controls and processes.
  • Multiple Locations or Departments: If your business operates in multiple locations or has various departments, an internal auditor can ensure consistency and compliance across the board.
  • High-Risk Operations: If your company handles sensitive data, has large cash flows, or faces significant regulatory oversight, an internal auditor can identify risks and help mitigate them.
  • Ongoing Monitoring: If you want continuous monitoring and improvement of internal controls and business processes, an internal auditor will provide regular assessments and feedback.

When Do You Need an External Auditor?

In the UK, businesses that meet certain size thresholds are legally required to have an external audit. External audits are necessary to provide independent verification of your company’s financial statements, offering confidence to stakeholders and ensuring compliance with regulatory standards.

When You Must Have an External Auditor:

  • Large Companies: If your company meets certain criteria (e.g., turnover of over £10.2 million, total assets exceeding £5.1 million, or more than 50 employees), you must have an external audit.
  • Public Companies: If your business is listed on the stock exchange, you are legally required to have an external audit.
  • Investors or Lenders: If you are seeking investment or funding, external audits provide independent assurance on the accuracy of your financial records, which is essential for gaining trust from investors or banks.
  • Regulatory Compliance: If your business operates in highly regulated sectors (e.g., finance, healthcare, charity), you may be legally required to undergo an external audit for compliance purposes.

Can an Internal Auditor Also Be an External Auditor?

While some firms offer both internal and external auditing services, the two roles must remain distinct. Independence is a critical factor for external auditors, and it would be a conflict of interest for someone who works as an internal auditor to also perform an external audit for the same business.

An internal auditor works closely with the business to help improve operations, while an external auditor provides an independent, unbiased review. Keeping these roles separate ensures transparency, accuracy, and integrity in the audit process.

How to Choose Between Internal and External Auditors

The decision to hire an internal auditor or external auditor depends on your business’s size, complexity, industry, and needs. Here’s how to determine which auditor your business requires:

  • Small Businesses: If you run a smaller business and don’t need regular oversight, you may only need an external auditor to verify your financial statements annually.
  • Medium to Large Businesses: As your business grows in size and complexity, having an internal auditor can help manage operational risks, streamline processes, and enhance internal controls. An external auditor will still be needed for independent verification of your financial statements.
  • Highly Regulated Industries: If you operate in a highly regulated industry, such as finance, healthcare, or charity, you may need both an internal auditor for day-to-day management and an external auditor for regulatory compliance.

Tip: Consider your company’s growth, complexity, and external stakeholder requirements when deciding whether you need internal, external, or both types of auditors.

Conclusion: Strengthening Your Business with the Right Auditor

Understanding the differences between internal and external auditors is essential for any UK business owner. Internal auditors help you improve operational efficiency and manage risk, while external auditors provide an independent review of your financial health and ensure compliance with regulations. Both auditors offer valuable insights, but knowing which one to choose depends on your company’s size, structure, and objectives.

Key Takeaways:

  • Internal auditors focus on internal controls, process improvement, and risk management.
  • External auditors verify the accuracy of your financial statements and provide an independent opinion.
  • Both types of auditors play essential roles, but businesses may only need one or both depending on their size, industry, and regulatory requirements.

By understanding their distinct roles and knowing when to engage each type of auditor, you can ensure the financial health of your business, meet compliance standards, and build trust with stakeholders.