Blog Page 58

FD Calculator – Your Smart Guide to Fixed Deposit Returns

Let’s be honest—when it comes to safe investments in India, Fixed Deposits (FDs) still rule the roost. While the financial world is buzzing with stocks, mutual funds, and cryptocurrencies, FDs continue to be the go-to option for millions of Indians who value stability over high risk.

But here’s the twist—although everyone knows about FDs, very few people actually calculate their real returns before investing. And that’s where an FD Calculator in India steps in like a financial superhero. With just a few clicks, you can estimate your maturity amount, interest earned, and plan your finances without scratching your head over complex math formulas.

In this detailed guide, we’ll break down everything you need to know about the FD Calculator in India—from how it works, to why it’s important, and how you can use it to make smarter financial decisions.
FD Calculator

What is an FD Calculator in India?

An FD Calculator in India is an online tool that helps you calculate the maturity value of your fixed deposit based on:

  • The amount you invest (principal)
  • The tenure of your deposit
  • The rate of interest offered by the bank or NBFC
  • The compounding frequency (monthly, quarterly, half-yearly, or yearly)

In simple terms, it does the heavy lifting for you. No more messy pen-and-paper calculations or complicated interest formulas—just enter the details and voila! You instantly know how much money you’ll have at the end of your FD term.

Why Should You Use an FD Calculator in India?

Now, you might be thinking, “Why do I even need an FD Calculator when I can just trust the bank?” Well, here’s why it’s a game-changer:

Clarity Before Investment

Instead of blindly parking money, you get a crystal-clear picture of how much you’ll earn.

Comparisons Made Easy

Different banks offer different FD rates. With a calculator, you can compare returns and pick the best option.

Saves Time and Effort

No manual calculations, no confusion—just accurate results in seconds.

Helps in Financial Planning

Whether you’re saving for your child’s education, wedding, or retirement, knowing your maturity value helps you plan better.

How Does an FD Calculator in India Work?

Behind the scenes, an FD Calculator uses the compound interest formula to give you the maturity amount.

Here’s the formula:

A = P(1 + r/n)^(nt)

Where:

  • A = Maturity Amount
  • P = Principal (your investment amount)
  • r = Rate of Interest (annual)
  • n = Number of compounding periods in a year
  • t = Tenure of investment (in years)

For example:
If you invest ₹1,00,000 in an FD for 5 years at 7% annual interest compounded quarterly, the FD Calculator will instantly show you the final maturity value without you having to crunch numbers.

Types of FD Calculations in India

When you use an FD Calculator in India, you’ll come across two common scenarios:

Cumulative FD (Compounded Interest)

  • Interest is compounded and reinvested.
  • You receive the total amount (principal + interest) at maturity.
  • Best for long-term savers who don’t need regular income.

Non-Cumulative FD (Periodic Payouts)

  • Interest is paid out monthly, quarterly, or yearly.
  • Useful for retirees or those seeking regular income.
  • FD Calculator helps you see how much you’ll earn per payout.

Step-by-Step: How to Use an FD Calculator in India

Using an FD Calculator is as easy as ordering food online. Just follow these steps:

  1. Enter the Investment Amount (Principal):
    Example: ₹2,00,000
  2. Select the Tenure (Time Period):
    Example: 3 years
  3. Choose the Rate of Interest:
    Example: 6.5%
  4. Pick Compounding Frequency:
    Monthly, quarterly, half-yearly, or yearly
  5. Click Calculate:
    The tool will instantly show your maturity amount and total interest earned.

Benefits of Using an FD Calculator in India

Still wondering if it’s worth your time? Let’s break down the benefits:

  • ✅ Accuracy: Avoid human errors in calculations.
  • ✅ Quick Comparison: Compare FDs across multiple banks.
  • ✅ Goal Planning: Helps in mapping FDs with financial goals.
  • ✅ Transparency: No hidden surprises when the FD matures.
  • ✅ User-Friendly: Anyone can use it—no financial degree required!

FD Calculator vs Manual Calculation – Who Wins?

Let’s face it—manual calculations are outdated. Here’s why:

Factor

Manual Calculation

FD Calculator in India

Time Taken

Several minutes

Instant (seconds)

Chances of Error

High

Zero

Convenience

Low

Very High

Comparison Feature

Not possible

Super easy

Clearly, the FD Calculator takes the trophy here! 🏆

Things to Keep in Mind While Using an FD Calculator in India

Before you dive into calculations, here are a few quick tips:

  • Interest Rates Vary: Different banks offer different FD rates, so always cross-check.
  • Tenure Matters: Longer tenure usually means higher interest rates.
  • Premature Withdrawals: Breaking your FD before maturity reduces returns.
  • Taxation: Interest earned on FDs is taxable, so factor that in.

Real-Life Example of FD Calculator in India

Let’s take a practical case.

Ramesh wants to invest ₹5,00,000 in an FD for 5 years. His bank offers 7% interest compounded annually.

  • Principal = ₹5,00,000
  • Tenure = 5 years
  • Interest Rate = 7%

Using the FD Calculator in India:

  • Maturity Value = ₹7,03,999 (approx)
  • Total Interest Earned = ₹2,03,999

So, Ramesh knows exactly what he’ll get after 5 years—no confusion, no surprises!

FD Calculator in India vs Other Investment Calculators

You may wonder—how does the FD Calculator compare with others?

  • SIP Calculator: Helps estimate returns on mutual funds.
  • PPF Calculator: Shows maturity value of Public Provident Fund.
  • EMI Calculator: Calculates monthly loan payments.

Each has its purpose, but the FD Calculator in India is all about fixed deposits—your safe and steady investment.

Frequently Asked Questions (FAQs)

Is the FD Calculator in India free to use?

Yes, most banks and financial websites provide it free of cost.

Can the FD Calculator show post-tax returns?

Not always. Some calculators do, but usually, you’ll need to adjust manually based on your tax bracket.

Does the FD Calculator work for all banks?

Yes, as long as you enter the correct interest rate and tenure.

Can I use the FD Calculator for senior citizen FDs?

Absolutely! Just enter the higher interest rate offered to senior citizens.

How accurate is the FD Calculator?

It’s 100% accurate if you input the right details.

Does the FD Calculator work for recurring deposits?

No, RD calculations are slightly different. You’d need an RD calculator.

Conclusion

An FD Calculator in India is more than just a digital tool—it’s your financial compass. It takes away the guesswork, gives you confidence, and helps you compare options so you can make the most of your hard-earned money.

Whether you’re a young professional planning short-term savings, or a retiree seeking steady returns, the FD Calculator ensures you never walk in blind. So, the next time you think of opening an FD, don’t just rely on assumptions—fire up an FD Calculator and let numbers guide your decision.

SWP Calculator – Calculate Mutual Fund Withdrawals

0

Have you ever wondered how long your money will last after you retire? That’s the million-dollar question (literally for some of us!). You’ve worked for decades, built up a tidy nest egg, and now it’s time to enjoy life without worrying about paychecks. But here’s the catch—how do you make sure your investments don’t dry up too soon?

Enter the SWP Calculator. This nifty tool is like your retirement GPS, helping you figure out how long your mutual fund investments can sustain systematic withdrawals while still keeping the growth engine running. With the right strategy, you don’t just withdraw money—you make your money work for you while enjoying a steady income stream.

In this article, we’ll break down everything you need to know about an SWP Calculator: how it works, why it’s a game-changer for retirement planning, and how you can use it to design a foolproof retirement income strategy.

So grab a cup of coffee, sit back, and let’s dive into this financial lifesaver!

SWP Calculator

What is an SWP Calculator?

At its core, an SWP Calculator is an online financial tool that helps you calculate:

  • How long your mutual fund investment will last when you withdraw a fixed sum every month (or quarter/year).
  • The impact of withdrawal amounts on your investment sustainability.
  • How market returns affect your retirement kitty.

Think of it like a crystal ball that shows you whether your retirement funds will be enough—or if you’ll need to tweak your plan.

Why Use an SWP Calculator for Retirement Planning?

When planning retirement, uncertainty is the biggest stress factor. Will inflation eat into your savings? What if your expenses shoot up? How much should you withdraw without burning through your investments too quickly?

An SWP Calculator helps answer these tricky questions. Here’s why it’s so useful:

  1. Predicts longevity of funds – You’ll know whether your savings can last 15, 20, or even 30 years.
  2. Customizes your income strategy – Adjust withdrawal amounts until you find a sustainable balance.
  3. Balances growth and safety – Lets you withdraw systematically while the remaining corpus continues to earn returns.
  4. Eliminates guesswork – You don’t need to crunch numbers manually or make risky assumptions.

How Does an SWP Calculator Work?

Using an SWP Calculator is simple. You’ll typically need to input:

  • Initial investment amount (say ₹50 lakh).
  • Expected annual return rate (for example, 8% per year).
  • Withdrawal amount per month (say ₹40,000).
  • Duration of withdrawal (number of years).

Once you plug in the numbers, the calculator shows:

  • How long your investment will last.
  • Whether you’ll run out of money sooner than planned.
  • The balance left after the chosen duration.

It’s like testing different financial “what-if” scenarios without losing a single rupee.

Benefits of Using an SWP Calculator

Let’s be honest: retirement planning isn’t just about saving money—it’s about making sure the money lasts. That’s where an SWP Calculator shines.

Peace of Mind

Nothing beats the relief of knowing your investments won’t run out prematurely.

Helps Maintain Lifestyle

You can match withdrawals to monthly expenses—be it groceries, travel, or even your Netflix subscription.

Inflation-Proofing

By simulating returns vs. withdrawals, you’ll know if your corpus can beat inflation.

Easy Adjustments

Want to increase or decrease your withdrawals? The calculator shows the impact instantly.

Smarter Tax Planning

Systematic withdrawals are often more tax-efficient than lump-sum redemptions.

Example: SWP Calculator in Action

Let’s say you invested ₹50 lakh in a mutual fund that gives an 8% annual return. You plan to withdraw ₹40,000 every month.

  • If you run this through an SWP Calculator, you’ll see your funds can comfortably last around 20–22 years.
  • If you increase withdrawals to ₹60,000 per month, the money may run out in just 13–14 years.

See the difference? Small tweaks in your withdrawal plan can completely change your retirement outlook.

SWP vs SIP – What’s the Difference?

You’ve probably heard of SIP (Systematic Investment Plan), right? Well, SWP (Systematic Withdrawal Plan) is the opposite.

  • SIP: You invest small amounts regularly to build wealth.
  • SWP: You withdraw small amounts regularly to enjoy your wealth.

And here’s the kicker—using an SWP Calculator helps you balance both sides of the equation if you’re transitioning from a wealth-building phase to a retirement-income phase.

Who Should Use an SWP Calculator?

The beauty of an SWP Calculator is that it’s not just for retirees. Here’s who benefits most:

  • Retirees – To plan monthly income without exhausting savings.
  • Pre-retirees – To test whether their corpus is sufficient.
  • Freelancers/self-employed – To create steady income streams during slow months.
  • Parents – To fund children’s education systematically.

Basically, if you’ve got investments and a need for regular income, this tool’s for you.

Tips to Maximize the Benefits of an SWP Calculator

Want to get the most out of this tool? Here are some pro tips:

  1. Be realistic with return expectations – Don’t assume 12% when markets may only give 8%.
  2. Factor in inflation – Expenses today won’t be the same 10 years later.
  3. Recalculate annually – Update inputs to reflect new market conditions.
  4. Start small, then adjust – Begin with modest withdrawals and increase only if sustainable.
  5. Diversify funds – Don’t rely on just one mutual fund for your SWP.

Common Mistakes to Avoid When Using an SWP Calculator

Even the best tools can’t save you from bad inputs. Watch out for these pitfalls:

  • Overestimating returns.
  • Ignoring inflation.
  • Setting withdrawal amounts too high.
  • Forgetting taxes on capital gains.
  • Not reviewing the plan regularly.

Remember, the calculator’s output is only as good as the data you feed into it.

FAQs  

Is an SWP Calculator free to use?

Yes! This calculator is free to use.

Can I change my SWP amount later?

Absolutely. You can modify withdrawals anytime based on your needs.

Does an SWP Calculator guarantee returns?

No—it’s only a simulation tool. Actual returns depend on market performance.

How often should I use an SWP Calculator?

Ideally, review your plan at least once a year or whenever your expenses change.

Is SWP better than fixed deposits for retirees?

For many, yes. SWPs can offer better post-tax returns and inflation-adjusted growth compared to FDs.

Conclusion

Planning retirement isn’t about hoarding money—it’s about using it wisely. That’s exactly what an SWP Calculator helps you do. By showing how long your mutual fund investments will last with systematic withdrawals, it takes the guesswork out of retirement income planning.

Whether you’re a retiree looking for peace of mind, a freelancer seeking steady income, or a parent funding education goals, the SWP Calculator is your trusted companion.

So don’t leave your golden years to chance. Run the numbers, tweak your withdrawals, and craft a strategy that lets you live life king-size—without worrying about your money running out.

SIP Calculator Calculate Your Mutual Fund SIP Returns with Ease

0

Imagine planting a small seed every month and watching it grow into a mighty tree years later. That’s exactly what investing in mutual funds through a Systematic Investment Plan (SIP) feels like. But here’s the thing—most investors are often left wondering, “How much wealth will my SIP really create in the future?” This is where a SIP Calculator steps in, acting like a crystal ball for your investments.

A SIP Calculator is an online tool that lets you estimate the maturity amount of your investments based on the monthly contribution, duration, and expected rate of return. It’s quick, simple, and saves you from endless manual calculations. More importantly, it gives you a clear picture of your financial future so you can make smarter investment decisions.

In this guide, we’ll explore everything about SIP Calculators—how they work, their benefits, step-by-step usage, practical examples, and even some frequently asked questions. Whether you’re a first-time investor or a seasoned one, this detailed guide will help you navigate your way to financial freedom with confidence.

SIP Calculator Mutual Funds

What Is a SIP Calculator?

A SIP Calculator is a financial tool designed to calculate the estimated returns from mutual fund SIP investments. By entering just a few details like:

  • Monthly investment amount (installment)
  • Investment duration (in years)
  • Expected annual rate of return

…the calculator instantly tells you the expected wealth you’ll accumulate.

It doesn’t guarantee returns (since markets fluctuate), but it does give you a realistic projection. Think of it like a GPS for your investments—guiding you toward your destination with clarity.

Why Should You Use a SIP Calculator?

Ever heard the saying, “Failing to plan is planning to fail?” That’s especially true in investments. Here’s why using a SIP Calculator makes sense:

  • ✅ Clarity on Future Returns – No more guessing games. You’ll know exactly how much wealth you’re building.
  • ✅ Goal Planning – Whether it’s a dream vacation, your child’s education, or retirement, the calculator helps align SIPs with goals.
  • ✅ Time vs. Investment Balance – You’ll discover whether to increase the monthly investment or extend the investment duration.
  • ✅ Comparison Between Funds – Quickly compare different mutual funds’ potential returns.
  • ✅ Motivation to Stay Consistent – Seeing the projected growth encourages discipline.

How Does a SIP Calculator Work?

The formula behind the SIP Calculator is based on the future value of an annuity, which looks complex but works like magic in the background. The formula is:

M = P × [(1 + r/n)^(n × t) – 1] / (r/n) × (1 + r/n)

Where:

  • M = Maturity amount
  • P = SIP amount (monthly investment)
  • r = Annual rate of return (in decimal)
  • n = Number of installments in a year (usually 12)
  • t = Tenure (in years)

Don’t worry if that looks overwhelming—thankfully, online SIP Calculators do all the math for you in seconds!

Step-by-Step Guide to Using a SIP Calculator

Using a SIP Calculator is as simple as making a cup of coffee. Here’s how:

  1. Enter Monthly Investment – Example: ₹5,000 per month.
  2. Select Tenure – Example: 10 years.
  3. Input Expected Return Rate – Example: 12% annually.
  4. Click Calculate – The calculator instantly shows the total invested amount, estimated wealth gained, and final maturity value.

📌 Example:

  • Monthly SIP: ₹5,000
  • Duration: 10 years
  • Expected Returns: 12% annually

👉 Result:

  • Total Invested: ₹6,00,000
  • Estimated Wealth Gained: ~₹4,32,000
  • Final Maturity Amount: ~₹10,32,000

Pretty impressive, right? That’s the power of compounding!

Benefits of Using a SIP Calculator

Let’s face it—financial planning isn’t always fun. But with a SIP Calculator, the process becomes engaging and insightful.

  • Easy to Use: No formulas, no spreadsheets—just a few clicks.
  • Visual Growth Projections: Many calculators show graphs and charts for easy understanding.
  • Free and Accessible: Available on almost every mutual fund website and app.
  • Customizable: Change amounts, tenures, or return rates to see different scenarios.
  • Saves Time: Why spend hours when results come in seconds?

Real-Life Scenarios of Calculator Usage

To make this more relatable, let’s look at some practical situations:

🎓 Education Planning

A parent wants to save for their child’s higher education 15 years later. By entering ₹10,000 monthly for 15 years at 12% returns, the SIP Calculator shows a maturity amount of nearly ₹50 lakhs.

🏡 Buying a Dream Home

A young couple sets aside ₹20,000 monthly for 20 years. With 12% returns, the calculator projects a corpus of over ₹1.5 crore—enough for a luxurious home.

👴 Retirement Planning

An individual starts investing ₹5,000 monthly at age 25 for 35 years. With the power of compounding, the calculator shows a jaw-dropping corpus of nearly ₹3.5 crores by retirement.

Common Mistakes to Avoid While Using a SIP Calculator

Even though SIP Calculators are super helpful, investors sometimes make errors. Avoid these traps:

  • ❌ Assuming Fixed Returns: Markets are volatile; the calculator shows estimates, not guarantees.
  • ❌ Ignoring Inflation: A corpus of ₹50 lakhs today won’t have the same value 20 years later.
  • ❌ Starting Late: The later you start, the lesser the compounding magic.
  • ❌ Not Reviewing Periodically: Goals and incomes change; so should your SIPs.

SIP Calculator vs. Lumpsum Calculator

Both tools are handy but serve different purposes:

  • SIP Calculator: Best for those investing small amounts monthly.
  • Lumpsum Calculator: Useful for those investing a big amount at once.

📌 Pro Tip: Use both calculators to see how a mix of SIP and lumpsum investments can fast-track wealth creation.

Frequently Asked Questions (FAQs)

  1. Is the SIP Calculator accurate?

It’s accurate in terms of projections, but actual returns may vary depending on market conditions.

  1. Can I use the SIP Calculator for all types of mutual funds?

Yes, whether it’s equity, debt, or hybrid mutual funds, you can estimate returns with a SIP Calculator.

  1. Does the SIP Calculator consider inflation?

Most SIP Calculators don’t factor in inflation directly. You should account for it separately while planning.

  1. How often should I check my SIP returns?

Review at least once a year or whenever your financial goals change.

  1. Can I become rich just by using a SIP Calculator?

Not exactly—the calculator is just a planning tool. Discipline, patience, and consistent investing are what make you wealthy.

Conclusion

A SIP Calculator isn’t just a number-crunching tool—it’s a financial compass guiding you toward your dreams. By using it wisely, you can plan better, stay consistent, and harness the magic of compounding.

Whether your goal is to fund your child’s education, buy a dream home, or enjoy a stress-free retirement, a SIP Calculator helps you visualize the journey clearly.

So the next time you’re about to start a mutual fund SIP, don’t just invest blindly. Use a SIP Calculator, map your goals, and let your money work for you!

GST Rate Update 2025 (GST 2.0) –  A Clear Guide to What Gets Cheaper (and Costlier)

0

On September 22, 2025, the Indian government will introduce sweeping changes to the Goods and Services Tax (GST) system. This reform, called “GST 2.0,” simplifies the current confusing tax structure, rolling four rates down to just two: 5% and 18%—and introduces a special 40% bracket for luxury and “sin” goods. This overhaul aims to make life more affordable for ordinary households while discouraging certain indulgent or harmful purchases.

In this guide, we’ll walk through the key winners and losers of this change—highlighting how family budgets, festival-season spending, and even the insurance industry will be impacted. We’ll use clear examples and simple language to explain exactly what each change means.

GST Rate Update GST 2.0

GST Rate Update 2025 (GST 2.0)

What Will Get Cheaper (The Big Reduction List)

Daily Essentials & Food Products (GST drops to 5% or even 0%)

  • UHT milk (Ultra-High Temperature-treated) goes from 5% to 0%—so buying that long-shelf-life milk becomes more affordable.
  • Paneer (pre-packaged and labelled) also moves from 5% VAT or custom state slab to 0%, meaning your cooking ingredients cost less.
  • Butter, ghee, cheese, and dairy spreads shift from 12% down to 5%, easing the cost of rich cooking staples like tarka or toast.
  • Condensed milk, dried nuts (almonds, cashews, hazelnuts, pistachios), sweet snacks like biscuits and chocolate, cornflakes, pasta, malt, and starches now fall under 5%, down from 12–18%.
  • Namkeen/savoury snacks, dates, figs, dried fruits, fruit pulps, even ready-to-eat items like pizza bread and khakra—many of these traditional food items now cost less thanks to the 5% rate.

This means the groceries you reach for daily—milk, bread, snacks—will all become easier on the pocket, especially with festivals like Diwali just around the corner.

Everyday Personal & Home Care Items (All at 5%)

  • Toothpaste, toothbrushes, soap, shampoo, hair oil, shaving cream, toilet soap—all are now taxed at 5%, down from 12–18%.
  • Feeding bottles, baby nappies and napkins now cost less at 5%, down from 12%.
  • Tooth powder, tableware, kitchenware, utensils, umbrellas, bicycles, bamboo furniture, combs, and other everyday utility items now have a 5% tax, reduced from 12%.

Buying home goods or caring for children or personal hygiene just became more affordable across the board.

Health, Education & Insurance (0% or 5%)

  • Life-saving drugs, cancer medicines, rare-disease treatments, diagnostic kits, glucometers, test strips, medical grade oxygen, thermometers, and corrective spectacles now attract either 0% or 5% GST, making healthcare essentials cheaper.
  • Individual life and health insurance policies will attract 0% GST—a major relief for policy buyers.

This will reduce the effective cost of medical care and insurance premiums—especially meaningful for middle-income families.

Education & Stationery (0%)

  • Maps, charts, globes, pencils, sharpeners, crayons, pastels, exercise books, notebooks, erasers now come with 0% GST, down from 5–12%.

Good news for students and parents: school supplies just got cheaper.

Textiles, Apparel, Footwear (5%)

  • Basic footwear and mass-market clothing are now 5%, down from 12%. (Note: this doesn’t apply to premium apparel over ₹2,500—see the “costlier” section.)

Electronics & Appliances (18%)

  • Televisions (above 32″), air conditioners, dishwashers, washing machines, refrigerators, monitors, projectors now attract 18% GST, down from 28%.

So upgrading your home electronics will cost less, especially timely as festive season sales begin.

Automobiles & Components (18%)

  • Small cars (including CNG, petrol hybrid under specific engine size/length limits), motorcycles up to 350 cc, and auto components generally now face 18% GST, down from 28%.
  • Electric vehicles (EVs) remain at 5%, continuing to support the eco-friendly vehicle push.

Popular cars like the Mahindra Thar or Hyundai Creta may become noticeably cheaper to buy.

Construction & Infrastructure (18%)

  • Cement now has a GST of 18% (down from 28%), helping reduce building costs.
  • Agricultural machinery, farm implements, micro-nutrients, drip irrigation systems, and tractor parts now mostly fall under 5%, down from 12–18%.

What Will Get More Expensive (The 40% Bracket)

Not everything is cheaper. A new 40% GST slab is in effect for select “sin” or luxury products, making them significantly costlier:

  • Tobacco products: pan masala, gutka, cigarettes, chewing tobacco, unmanufactured tobacco.
  • Aerated/caffeinated beverages, including carbonated soft drinks like cola.
  • Luxury vehicles, yachts, private aircraft (e.g., single-owner aircraft).
  • Gambling and betting services, including casinos, lotteries, horse racing, and online gaming.

Notably, IPL (cricket match) tickets and high-value live event tickets may also carry much higher tax than before—potentially near the 40% level.

These steeper taxes are likely meant to reduce harmful consumption or luxury excesses—and help balance government revenues.

Why The Change? What It Means

  1. Simplification of the Tax Structure
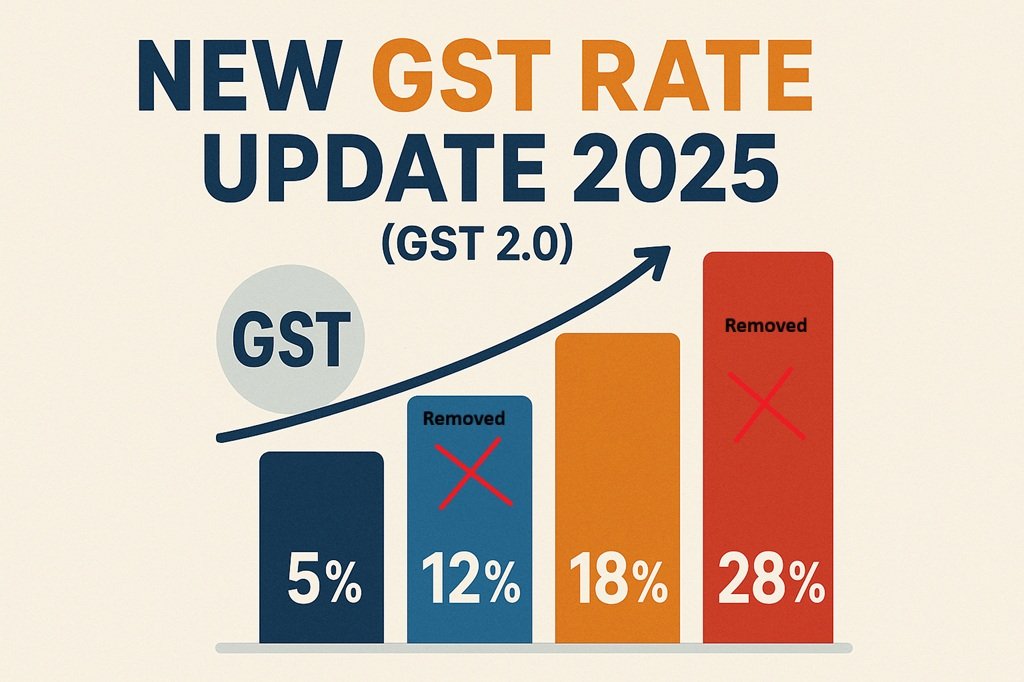
    By collapsing the GST slabs from four (5%, 12%, 18%, 28%) to just two (5% and 18%) plus the luxury 40% rate, the system becomes easier to understand, enforce, and comply with.
  2. Support for Consumers & Businesses
    Sharp cuts on daily-use items help ease inflationary pressure. Analysts say consumer prices might drop by up to 1.1 percentage points in inflation, depending on how much producers pass on savings.
    Companies like Hindustan Unilever, Nestle, Godrej (in fast-moving consumer goods) and appliance makers like LG or Sony may see higher demand. Car brands such as Maruti, Yamaha, Hyundai could also benefit.
  3. Revenue Impact
    The government expects a revenue loss of ₹48,000 crore (~$5.5 billion), though this is lower than earlier projections.
  4. Boost to Festive Sales & Domestic Demand
    Slashed GST rates come just before Navratri and Diwali. With electronics, furniture, clothing, cars, and home appliances getting cheaper, retailers and automobile dealers could see a surge in sales.
  5. Support for Farmers & Rural Economy
    Cuts in GST on tractors, irrigation systems, fertilisers, and farm machinery ease input costs for farmers.

Everyday Examples: What This Means For You

Example 1: Grocery Shopping

Earlier, buying butter (12%), paneer (5%), biscuits (18%), ghee (12%) could make your total tax bill feel heavy. Now, each of these is just 5%—or even 0% for some dairy items. You save money every time you buy essentials.

Example 2: Home Electronics Upgrade

A TV that used to carry 28% GST now comes with only 18%. A new AC, dishwasher, fridge, or washing machine is similarly cheaper—prompting many to invest in home comfort just in time for holidays.

Example 3: Buying a Two-Wheeler or Car

If you’re eyeing a budget motorcycle (≤350 cc), your car in the sub-1,200 cc range, or a small hybrid, the GST drop to 18% makes these vehicles more affordable. Electric vehicle buyers get even better deals at 5% GST.

Example 4: Health & Insurance Expenses

Paying for a glucometer, medicines, baby feeding supplies, or even medical check-ups is less burdensome. Plus, life or health insurance becomes GST-free—a welcome saving during tough times.

Example 5: Entertainment & Leisure

Movie lovers pay just 5% GST on tickets under ₹100 (down from 12%), giving low-cost ticket buyers relief. But if you attend an IPL match or a big live concert, expect much steeper ticket prices—possibly double the GST you paid before.

Final Thoughts: GST 2.0 in a Nutshell

What’s changed:

  • Simplified slabs: Replaced 12% and 28% with just 5% and 18%, plus a new 40% for luxury/sin goods.
  • Goods that got cheaper: Everyday essentials, personal care, food, electronics, vehicles, insurance, healthcare, stationery, and more.
  • Goods that cost more: Tobacco, soft drinks, luxury vehicles, gambling, and live-event entertainment.
  • Launch date: These changes come into effect on September 22, 2025, aligning with the Navratri festival start.

Big impacts to expect:

  • Lower prices on staple items and durable goods.
  • Stimulated demand, especially during festivals and holiday shopping.
  • Support for farmers, low-income households, and small buyers.
  • Balanced revenue pressures via higher tax on non-essentials.

Overall, GST 2.0 is about balance. It eases the burden on middle-class households by slashing taxes on food, healthcare, and personal items. For a family earning Rs 50,000 a month, savings on groceries and meds could add up to Rs 1,000-2,000 monthly. That’s money for education or savings. Businesses benefit from simpler compliance—fewer slabs mean less paperwork and errors.

But challenges remain. States need to agree on revenue sharing, and some industries like automotive might see mixed impacts. Luxury sectors could slow down, but essentials should boom. Investors are watching closely, as Praveen Nijhara noted, to see if this strikes the right balance between relief and revenue.

In the end, these changes starting September 22, 2025, reflect a push for a fairer system. Whether you’re shopping for milk or dreaming of a new bike, understanding these shifts helps you plan better. Keep an eye on official notifications for any fine print, and remember, small savings today can lead to big differences tomorrow. If you’re a consumer, celebrate the cheaper essentials; if a business owner, adapt to the new simplicity. This is GST evolving to meet modern needs, one rate at a time.