Blog Page 352

Buying Health Insurance Policy in India – Information Guide

Buying a health insurance policy is a vital need today. Let me share with you one incident, Last Saturday I visited the hospital to meet my friend, he is suffering from a severe heart problem. The doctor advised him to undergo heart surgery. However, due to a lack of money and health insurance, he is unable to complete his treatment.

Many Indians are like my friend, as they avoid buying a health insurance policy. They don’t understand that health problems do not give advance notice before knocking the door. One should be ready for medical emergencies at any time. One should buy adequate health insurance covering all family members against major diseases. The health insurance policy offers risk coverage against expenses caused by any medical emergencies.

In the last few years, health insurance products has become a bit complex. Earlier health insurance policies were only covering hospitalization expenses, but now even OPD, pre and post-hospitalization expenses including maternity and dental treatment have come under the insurance net. Apart from this many other interesting features are added in health insurance policies.

People get confused while buying a health insurance policy, in order to help them here is a complete information guide about buying the best health insurance policy in India.

health insurance policy india

Buying a Health Insurance Policy in India

Point #1 – Deciding Sum Assured

The first point that comes while buying a health insurance policy is deciding the sum assured. You need to decide how much coverage is enough for you and your family. In order to decide the right sum assured you need to assess your lifestyle.

If you and your family are fit, following healthy habits including regular exercise, don’t smoke, had a clean medical history, you are in a good situation and require less risk coverage. If not your risk coverage requirement is high.

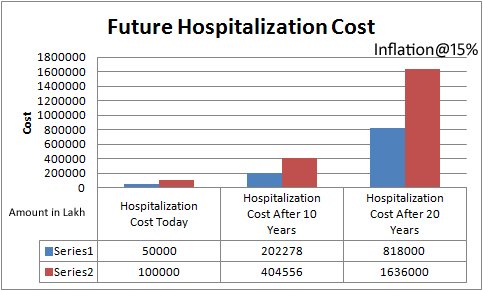
Another factor you need to consider before buying health insurance is inflation in the medical field. Medical expenses are growing at the rate of 15%. Hospitalization cost today is in the range of Rs. 50000 to Rs. 1 Lakh. Assume that you are 30 years old and inflation is in the range of 15% for the next 20 years, hospitalization bill will be in the range of 8 Lakh to 16 Lakh when you are 50 years old.

hospitalization cost

Looking at the current trend you should buy a health insurance policy with sum assured not less than 15 Lakh.

Point#2 – Individual Cover or Family Floating Plan

Secondly, you need to decide whether you want an Individual coverage plan or a Family floater plan.

Individual Coverage – Individual health insurance policy is a separate policy for the individual.

  • This type of policy is suitable for old age person where more risk coverage is required.
  • Individual coverage policy is more expensive

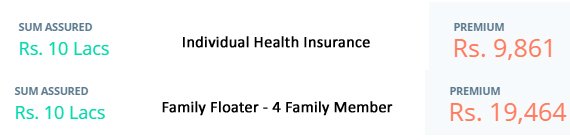
Family Floater – Family floater is a shared coverage policy that provides fixed coverage among all family members.

E.g If you take a family floater plan of 10 Lakh, all family members among the family have covered with maximum amount i.e 10 Lakh. Anyone can utilize this entire amount throughout the year. If a partial amount is utilized by one family member, coverage of the remaining amount is applicable to the remaining family member throughout the year.

  • The family floater plan is suitable for young families with low-risk coverage.
  • It is less expensive compared to individual health policy.
  • The only disadvantage of this policy is if one family member has utilized more amount coverage will be limited to the remaining amount.

family floater

Family floater plan means saving of money.

Point#3 – Room Eligibility Capping (Limit and Exclusion)

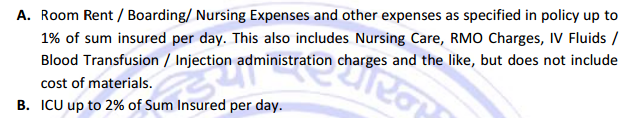
 Some Health insurance policies come with a clause of hospital room rent limit. The clause says that the room rent limit is 1% of the total sum assured or a fixed amount says Rs 5000 whichever is lower. This seems to be a very small restriction, however, this will have a huge impact on the insurance claim.

You need to be careful while accepting the actual clause mentioned in the policy document. Let’s take a look at the following clause taken from the New Indian assurance health policy.

room rent health insurance

One should not purchase policy mentioning clauses like the above. This will be a limiting factor to your claim.

Medical expenses are growing every day and restrictions like the above will take your policy on the toss.

Point#4 – Maternity Coverage

Special health insurance policies for women are available nowadays. If you are expecting growth in your family you can plan to buy a health insurance policy with maternity coverage benefit. It is add-on coverage to standard health insurance.

Maternity coverage offers cover for medical expenses incurred at the time of pregnancy and delivery.

Point#5 – Hospital Network coverage & Cashless claim

You should review and obtain information about Hospital Network coverage offered by health insurance policy. An Insurer with a broad list of the hospitals in its network across India should be given a preference.

Apart from this you should also look at the cashless claim facility available with the insurer. The cashless facility provides an additional advantage as you do need not to arrange for cash for treatment.

Point#6 – Sublimit or Co-pay

When you buy a health insurance policy, you should be sure that the policy has no expense or disease-specific sub-limit. There are clauses like sub limit or co-pay in most of health insurance policies.

It is a critical feature while evaluating health policy, a policy with a sub limit will put you in an unpleasant situation at the time of claim settlement.

Point#7 – Pre-existing disease coverage

If you are suffering from any disease you need to mention that while buying a health insurance policy. The insurer will not provide you coverage against these diseases at the time of buying the policy. However, depending upon policy terms and conditions these diseases will be covered after 1 year or 2 years.

Point#8 – No claim bonus

The insurer provides you No claim bonus if there is a year where no claim is made against the policy.  No claim bonus means an increase in coverage without additional premium. One should check the quantum of No claim bonus provided by the insurer. No claim bonus is in the range of 5% to 50%.  A high no claim bonus policy is advisable as it safeguards you against growing inflation.

Point#10 – Annual Free Checkup

Free Annual Medical Checkup is a term used by the insurer, but believe me “There is no such thing as a free lunch”. Everything has a cost and it is bundled. If you are keen on getting an annual medical checkup done every year you should opt for it.

Another fact is an insurance policy is getting renewed every year and it is a long-term affair. Think that you will be able to go for an annual free checkup every year?

Point#11 – Restore Benefits

This is a newly introduced feature by various insurance companies. It says that if you or your family member exhausts your sum assured during the year.  The health insurance policy will restore the full amount back for usage for any new disease without any charge. You should select this feature if it is really required by you.

Conclusion –

Buying a Health insurance policy is an important decision of your financial planning. Before buying health insurance, you should read all policy-related documents carefully.  If you are unable to understand the terms/clauses ask as many questions as you can to the Insurance advisor to clarify all your doubts. It is better to clear confusion before buying an insurance policy.

Missed Call Banking Phone Number of All Banks

missed call banking

Missed call banking is a new way of banking, where you can give missed call with your register mobile number to avail banking facility. Using missed call banking you can avail various banking facilities like balance enquiry, mini statement, blocking ATM card etc.

Missed call facility is a boon to the customer. It is like doing banking on finger tips. One can get all account related information over the phone. All major Banks including SBI, Axis Bank, ICICI Bank, HDFC Bank, Bank or Baroda offers this facility.

In this post, I will provide missed call banking phone numbers of all major Banks.

Missed Call Banking Phone Number of All Banks

State Bank of India

SBI offers a quick missed call banking facility. To avail this facility first, you need to register for this facility. You can register by sending SMS ‘REG(space)account number’ to 09223488888. Bank will send confirmation message indicating registration status successful or unsuccessful.

Once you are registered you can use this facility.

  • To know your bank balance give missed a call to 09223766666.

Axis Bank
This facility is also available for axis bank customers. Service offered by axis bank is free of cost.

  • Dial 1800 4195959 to know your account balance
  • Dial 1800 4196969 to get your Mini Statement

ICICI Bank

India’s largest private sector bank ICICI also provides a missed call banking facility.

  • Dial 02230256767 once connected ring will be made and a call will be disconnected automatically.

You will receive SMS from a bank which will contain your balance information.

HDFC Bank

HDFC Bank provides the free missed call banking facility.

  • Call 1800 2703333 to get your account Balance
  • Call 18002703355 to get your Mini statement
  • Call 18002703366 to give request for Cheque Book
  • Call 18002703377 to give request for Account Statement

Bank of Baroda

Bank of Baroda also provides this facility.

  • Call 09223011311 to know your bank balance.
  • You will get SMS containing details bank balance to your register mobile number.

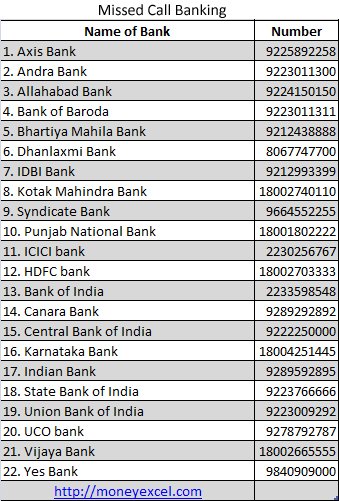
Ready Reference list containing information about all other banks is given below.

missed call banking

Hope you will find this information useful. Do share this information with your friends!

Cost of Child Education – Planning and Calculator

We always dream of giving the best education to our children but do we really think about the growing cost of child education? We want a child to become a doctor or engineer but do we really plan for this? As per me saving for child education is the most important goal for parents. Other goals like buying a car or buying a home can be compromised, but we cannot compromise our child’s education.

Education is often considered the best investment for the future. However, providing quality education for children in India seems like a huge financial challenge. Due to increasing tuition fees, expensive extracurricular activities, and a persistent rise in inflation, parents frequently experience feelings of being overwhelmed. Let’s explore the details of the expenses for child education in India and how inflation can impact your costs.

cost of education

Breaking Down the Cost of Child Education in India

If you’re a parent or planning to become one, you might have already caught yourself daydreaming (or panicking) about how much education is going to cost. Let’s break it down step by step:

Pre-Primary and Primary Education: The Foundation Phase

This is where it all begins, with toddlers heading off to preschools like Montessori or nursery schools. These early years are surprisingly expensive in India, especially if you’re aiming for premium schools.

  • Cost: Expect to shell out anywhere from ₹50,000 to ₹2,50,000 annually for private schools. The fees vary depending on whether it’s a local school or a prestigious international institution.
  • Additional Expenses: Transportation, uniforms, books, and school supplies can add ₹30,000 to ₹50,000 a year.

And this is just the start. Scary, right? But wait, there’s more!

Secondary and High School Education: The Real Investment Starts

When your child enters middle and high school, the stakes—and the expenses—start climbing. Schools begin to focus more on academics, sports, and overall personality development, which means more resources and higher fees.

  • Cost: Fees for secondary education in private schools range between ₹1,00,000 to ₹5,00,000 per year, depending on the school’s reputation and facilities.
  • Coaching and Tuitions: If your child is preparing for competitive exams like JEE or NEET, be prepared to spend an additional ₹50,000 to ₹3,00,000 annually on coaching.
  • Extracurricular Activities: Sports, music, robotics, and other after-school programs could add another ₹20,000 to ₹1,00,000 annually.

When you add all this up, it’s clear that high school is where education begins to pinch your wallet harder.

Higher Education: A Whole New Ballgame

Higher education, whether in India or abroad, can easily become the single largest expense in your child’s life. Whether it’s an engineering degree, medical school, or an MBA, the numbers are staggering.

  • Engineering and Medical Degrees: Private colleges charge ₹5,00,000 to ₹25,00,000 for a four- or five-year course.
  • MBA Programs: Premier institutions like the IIMs demand upwards of ₹20,00,000 for a two-year program.
  • Study Abroad: If your child dreams of studying in the US, UK, or Australia, the costs could range between ₹25,00,000 and ₹1 crore, depending on the course and university.

How Inflation Affects Education Costs

Inflation is that silent predator lurking in the background, making everything—yes, even education—more expensive over time. The average inflation rate for education in India is around 10-12% annually, which is significantly higher than the general inflation rate of 5-6%. Let’s understand this with a quick example.

The Snowball Effect

Imagine you’re paying ₹1,00,000 a year for school fees today. With a 10% inflation rate, this amount becomes ₹1,10,000 next year. Fast-forward 10 years, and you’re staring at a fee structure that’s doubled to ₹2,00,000 annually!

But inflation doesn’t just affect tuition fees. Everything from books to uniforms, extracurricular activities, and even transportation costs rises in tandem. Over 15-20 years, these incremental hikes can amount to a small fortune.

Why Are Education Costs Rising So Rapidly?

Ever wondered why education costs in India are skyrocketing? It’s not just inflation. There are a few other culprits at play:

Increasing Demand for Quality Education

India’s growing middle class aspires for world-class education, which has led to a surge in demand for premium schools and colleges. Naturally, when demand outstrips supply, prices go up.

Infrastructure and Technology Costs

Schools and colleges now invest heavily in smart classrooms, advanced labs, and high-tech infrastructure. While these advancements are great for your child’s learning, they come at a steep price.

Global Influence

Many schools, especially international ones, benchmark their pricing against global standards. This drives up costs even further.

Competitive Exam Preparations

With intense competition for top colleges, private coaching has become the norm. Institutions charge exorbitant fees, further adding to a parent’s financial burden.

How to Plan for Your Child’s Education Expenses

Now that you know how expensive education can get, let’s talk about solutions. Don’t worry—there’s light at the end of this tunnel. Here are some practical tips:

Start Early with Education Savings

The earlier you start saving, the better. Education inflation outpaces regular inflation, so it’s wise to invest in high-return instruments like mutual funds, stocks, or ULIPs designed for child education.

Explore Scholarships and Grants

Many schools, colleges, and even coaching centers offer scholarships based on merit or financial need. Make sure to explore these options early.

Invest in an Education Loan

For higher education, especially abroad, education loans can be a lifesaver. They offer flexible repayment options and tax benefits under Section 80E of the Income Tax Act.

Leverage Insurance Plans

Child insurance plans provide financial coverage for education in case of unforeseen circumstances. These can be a safety net against uncertainties.

Future of Education Costs in India: Is There Hope?

While education costs will likely continue to rise, governments and educational institutions are making efforts to ease the burden. Initiatives like subsidized loans, increased public school funding, and the promotion of online learning could provide some relief.

Online education, in particular, is emerging as a game-changer. With platforms like BYJU’S, Unacademy, and Coursera offering affordable alternatives, parents now have more choices than ever before. While it may not completely replace traditional education, it can definitely complement it.

Conclusion

The cost of child education in India is undeniably high, and inflation only makes it tougher. But with careful planning, strategic investments, and smart choices, you can ensure your child gets the education they deserve without breaking the bank. Think of it as a marathon, not a sprint. Start early, stay consistent, and you’ll cross the finish line with ease.

FAQs

How much should I save for my child’s education in India?

It depends on your child’s age, the type of education you’re aiming for, and inflation. A rough estimate is to save around ₹50,00,000 to ₹1 crore over 15-20 years for quality schooling and higher education.

Are there affordable alternatives to private schools in India?

Yes! Kendriya Vidyalayas and state-run schools offer quality education at a fraction of the cost. However, they might lack the infrastructure and extracurricular exposure of private schools.

Can inflation in education costs ever be controlled?

While it’s hard to eliminate inflation, steps like government subsidies, online education, and increased public funding could help slow down the rise in costs.

Is an education loan a good idea?

Absolutely, especially for higher education. Education loans come with flexible repayment options and tax benefits, making them a practical choice for many families.

What is the biggest contributor to rising education costs?

Apart from inflation, factors like demand for premium education, rising infrastructure costs, and private coaching fees significantly drive up costs.

By staying informed and proactive, you can navigate the maze of education expenses and secure a bright future for your child!

To extend help to you we have developed one calculator you can download it from below.

Download Child Education Calculator

Hope you find this calculator useful.

Do share this calculator with every parent you come across!