Blog Page 348

Payment Banks India – Features and Benefits

Ever heard of payment banks and wondered what they are and why they’re such a big deal in India? Don’t worry; you’re not alone. Payment banks might sound like some complicated financial jargon, but they’re actually quite simple and incredibly useful. In this article, we’ll break it all down for you – what they are, how they work, and why they matter. So, let’s dive in!
Payment Bank India

What Are Payment Banks?

Imagine a regular bank, but with fewer services and a sharper focus on making banking accessible to everyone. That’s what payment banks are. These are a special category of banks introduced by the Reserve Bank of India (RBI) to bring banking services to the masses, especially in rural and unbanked areas.

Payment banks can accept small deposits (up to Rs. 2 lakh per individual as of now), provide savings and current accounts, issue debit cards, and facilitate online and mobile banking. However, they don’t offer loans or credit cards, making them a unique addition to India’s banking ecosystem.

Why Were Payment Banks Introduced?

The concept of payment banks was born out of a need to promote financial inclusion in India. Let’s face it; traditional banking isn’t always accessible to everyone, especially people in remote areas. Many individuals don’t have a bank account or access to formal financial services, leaving them out of the economic loop.

Payment banks aim to bridge this gap. By leveraging technology and simplifying banking processes, they’ve made it easier for people to manage their money, transfer funds, and even save for the future. Pretty cool, right?

Key Features of Payment Banks

Now that you know the basics, let’s take a closer look at the features that make payment banks stand out:

1. Small Deposit Limits

Payment banks can accept deposits up to Rs. 2 lakh per individual. This makes them perfect for small savers who don’t need a full-fledged bank account.

2. Savings and Current Accounts

You can open both savings and current accounts with a payment bank. The interest rates on savings accounts are often competitive, making them an attractive option for individuals.

3. No Credit Facilities

Unlike traditional banks, payment banks don’t offer loans or credit cards. This keeps their operations simple and focused.

4. Digital Banking Services

Payment banks are all about convenience. They provide mobile banking apps, online services, and easy fund transfers through NEFT, RTGS, and IMPS.

5. Issuance of Debit Cards

You can get a debit card from a payment bank, which allows you to withdraw cash from ATMs and make online and offline payments seamlessly.

6. Focus on Financial Inclusion

Their primary goal is to bring banking to the unbanked and underbanked segments of the population, particularly in rural and semi-urban areas.

Benefits of Payment Banks

So, why should you care about payment banks? Here are some of the benefits they bring to the table:

1. Accessible Banking

Payment banks have revolutionized banking by making it accessible to people in remote areas. Thanks to their mobile-friendly approach, you can open an account and manage your money from the comfort of your home.

2. Cost-Effective

With low maintenance fees and no hidden charges, payment banks are a cost-effective alternative to traditional banks. This is especially beneficial for people with limited income.

3. Fast and Easy Transactions

Need to send money to a friend or pay a bill? Payment banks make it super quick and hassle-free, thanks to their digital-first approach.

4. Encourages Savings

By offering attractive interest rates on savings accounts, payment banks encourage people to save more. Even small savings can add up over time.

5. Enhanced Security

Payment banks use cutting-edge technology to ensure your money and personal information are secure. From encryption to two-factor authentication, they’ve got your back.

6. Bridging the Digital Divide

With their mobile-first strategy, payment banks are helping to bridge the digital divide in India. Even people without smartphones can access their services through SMS and IVR.

Popular Payment Banks in India

Several players have entered the payment bank space since the RBI gave the green light. Some of the most notable ones include:

  • Airtel Payments Bank: Known for its extensive reach in rural areas, this bank offers a range of services, including savings accounts and money transfers.
  • Paytm Payments Bank: A favorite among tech-savvy users, Paytm Payments Bank integrates seamlessly with the Paytm app for easy transactions.
  • India Post Payments Bank (IPPB): Operated by India Post, this bank leverages the vast postal network to deliver banking services to every corner of the country.
  • Fino Payments Bank: Focused on providing hassle-free banking solutions, Fino Payments Bank caters to both urban and rural customers.
  • Jio Payments Bank: Backed by Reliance, this bank is slowly but steadily gaining traction with its innovative offerings.

How to Open an Account with a Payment Bank

Opening an account with a payment bank is as easy as pie. Here’s what you need to do:

  1. Choose a Payment Bank: Decide which payment bank suits your needs best.
  2. Download the App or Visit a Branch: Most payment banks have mobile apps for easy account opening. Alternatively, you can visit a branch or agent point.
  3. Provide KYC Documents: You’ll need basic KYC documents like your Aadhaar card and PAN card.
  4. Complete Verification: The bank will verify your details, which might include biometric verification.
  5. Start Using Your Account: Once your account is set up, you can deposit money, make transactions, and enjoy the benefits of digital banking.

Are There Any Drawbacks?

While payment banks offer plenty of advantages, they do have a few limitations:

  • No Loan Facilities: If you need a loan or a credit card, you’ll have to look elsewhere.
  • Deposit Limits: The Rs. 2 lakh deposit cap might be restrictive for some users.
  • Limited Investment Options: Payment banks don’t provide investment products like mutual funds or fixed deposits.

The Future of Payment Banks in India

Payment banks have already made a significant impact, but their journey is far from over. With advancements in technology and increasing smartphone penetration, the future looks bright. As they continue to innovate and expand their reach, payment banks could play a pivotal role in shaping India’s financial landscape.

Final Thoughts

Payment banks are more than just a buzzword; they’re a game-changer for India’s banking sector. By making financial services accessible, affordable, and user-friendly, they’re empowering millions of people to take control of their finances. Whether you’re a tech enthusiast, a small saver, or someone looking for a no-fuss banking solution, payment banks have something to offer.

So, what are you waiting for? Explore the world of payment banks and see how they can make your life easier. Who knows? This might just be the financial revolution you’ve been waiting for!

FAQ

1. Can I open multiple accounts with different payment banks?

Yes, you can open accounts with multiple payment banks, but keep in mind the Rs. 2 lakh deposit limit applies per individual per bank.

2. Are payment banks safe to use?

Absolutely! Payment banks are regulated by the RBI and follow strict security protocols to protect your money and data.

3. Can I get a credit card from a payment bank?

No, payment banks don’t offer credit cards or loans. You’ll need to approach a traditional bank for those services.

4. How do I withdraw cash from a payment bank?

You can use the debit card provided by the payment bank to withdraw cash at ATMs or access agent points for cash withdrawals.

5. What happens if I exceed the Rs. 2 lakh deposit limit?

If your deposits exceed Rs. 2 lakh, the payment bank may freeze the excess amount or transfer it to your linked account in a traditional bank.

Capital Gain Tax Calculator – Download

0

capital gain tax

How to calculate capital gain for computing taxes? I have seen many people committing mistake while calculating capital gain tax. Many people believe that calculation of capital gain tax is complex. So, let’s try to simplify this calculation by understanding Capital Gain and Capital Gain Tax.

What is Capital Gain?

My friend recently sold property purchased by his father. This property was purchased at the cost of 25 lac in 2010. He sold this property in 50 lac recently. What will be profit 25 Lac simple right? If you are thinking it is 10 Lac you are wrong! Continue reading you are going to learn lot of things today.

Ideally capital gain is gain arising from sale or transfer of capital assets like property, shares, mutual funds, bonds etc. However when it comes to capital gains in taxes above definition of capital gain is not true.

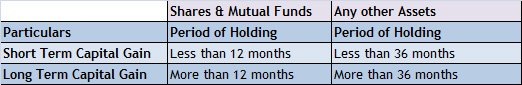
Capital gains is divided into two types (1) Short-term Capital Gain and (2) Long-term Capital Gain. This classification is based on holding period of assets.

Also Read – How to know your Gratuity Benefits – Calculator Download 

capital gain

How to Calculate Capital Gain Tax for Property?

Short Term Capital Gain Tax on Property

You can get calculate Gross Short Term Capital Gain by subtracting cost of purchase, expense on transfer/sell and cost of improvement from sale price.

Gross Short Term Capital Gain =

“Fair Market Value or Sale Price – Expense on Transfer – Cost of Purchase – Cost of Improvement”

  • Sale Price is price on which you have sold your property.
  • Expense on Transfer includes any cost incurred for selling this property i.e stamp duty, advertisement, legal expense etc.
  • A Cost of Purchase is amount paid by owner at the time of acquiring property.
  • A Cost of Improvement includes any cost incurred on improving or altering property since its acquisition.

You can get calculate Net Short-Term Capital Gain by subtracting Gross Short Term Capital Gain from Exemption.

Also Read – Cost of Child Education – Planning and Calculator 

Net Short-Term Capital Gain =

“Gross Short Term Capital Gain – Exemption (If any) (54B/54D/54G/54GA)”

  • 54B – Transfer should be of agricultural land. One should purchase New Agriculture land in 2 years from capital gain.
  • 54D – Property acquired for Industrial purpose. One should purchase new Industrial property within 3 years from capital gain.
  • 54G – Transfer should be of Machinery building or plant. Transfer should be due to shifting to any area other than an urban area.
  • 54GA – Transfer should be of Machinery building or plant. Transfer should be due to shifting to any Special Economic Zone.

Once you obtain this value calculate tax on this value as per normal income tax slabs, that amount will be your short term capital gain tax on property.

Long Term Capital Gain Tax on Property

Long Term Capital Gain Tax rate is 20%.

You can get calculate Gross Long Term Capital Gain by subtracting index cost of purchase, expense on transfer/sell and index cost of improvement from sale price.

Gross Long Term Capital Gain =

“Fair Market Value or Sale Price – Expense on Transfer – Index Cost of Purchase – Index Cost of Improvement”

  • Index cost of purchase is process by which the cost of purchase or acquisition is adjusted against inflationary rise in the value of asset. For this purpose Central Government notify cost inflation index (CII) every year.

Index cost of Purchase = Actual cost * CII for Year of Sale/ CII for Year of Purchase

Index cost of Improvement = Cost of Improvement * CII for Year of Sale/CII for Year of Improvement

Download Capital Gain Calculator

How to Calculate Capital Gain Tax for Shares & Mutual Funds?

Short Term Capital Gain Tax on Shares & Mutual Funds

Short Term Capital Gain Tax applicable on Transfer of shares and mutual funds is flat 15%, provided transaction is taking place at the recognize exchange and Security Transaction Tax (STT) is paid.

Short Term Capital Gain = Sale Price – Expense on Transfer – Cost of Purchase – Cost of Improvement

  • Sale price is price at which you have sold the shares or mutual funds.
  • Expense on Transfer in this case is brokerage charged by AMC or brokerage house.
  • Cost of purchase is purchase price of shares or mutual funds.

Also Read – All you want to know about your Salary Slip

Long Term Capital Gain Tax on Shares and Mutual Funds

Long term capital gain tax on shares and mutual funds is reintroduced in 2018.

  • As per new rule any person who sells shares after April 1, 2018, will pay a long-term capital gains tax at the rate of 10 percent on gains of more than Rs 1 lakh. For such shares, the cost of acquisition will be price as on Jan. 31, 2018.
  • If a person who has held shares for more than one year sells them before March 31, 2018, there will be no long-term capital gains tax.
  • No changes are made in short-term capital gain tax. Short-term capital gain would be taxed @15%.

Let’s try to figure out how this change will impact you.

Case 1 –

If you sell your equity or mutual fund investment before April,1,2018 you need not pay any LTCG as a new rule of LTCG will be applicable after April,1,2018.

Case 2 –

Suppose you sell shares after March,31,2018 you need to pay LTCG. LTCG is applicable beyond 1 Lakh. This means no tax is payable on profit amount up to 1 lakh per annum. Any amount beyond 1 Lakh will be taxed @10%. Suppose your long-term capital gain from equity and the stock market is 1.5 Lakh in a year. You need to pay tax on Rs.50000.

PAN Card mandatory for these 20 Financial Transactions

0

PAN card

PAN Card is important document issued by Income Tax department to the taxpayer. PAN Card contains 10 digit unique alphanumeric number. PAN card also serve purpose of valid identity proof. However, prime objective of PAN card is to track financial transactions done by tax payer. Income tax department enforced individual to mention PAN card while doing financial transactions. This is to eliminate tax evasion and malpractices like usage of black money.

20 Financial Transaction where quoting PAN card is Mandatory

  1. You need to quote PAN in case you are doing sale or purchase of immovable property worth 5 lac or above.
  2. PAN card is mandatory for sale or purchase of any goods costing 1 Lac or above.
  3. If you are planning sale your car or planning to purchase new car you need to mention PAN number.
  4. PAN is required for opening bank account. In case you are opening account on the name of minor PAN card of parents is required.
  5. PAN number is required If you want to deposit 50,000 Rs or above in cash for bank account.
  6. Quoting PAN number is mandatory if you purchase a bankers draft, pay order or bankers cheque exceeding 50,000 Rs.
  7. Any payment made to hotel or restaurant exceeding 25,000 Rs you need to mention PAN card.
  8. PAN card is required in order to apply for new telephone connection including mobile connection.
  9. You need to mention PAN number while buying financial securities (stocks, bonds, debenture) costing 50,000 Rs or above.
  10. Payment of 50,000 Rs or above for the purchase of Mutual Funds units.
  11. Applying for Credit Card or Debit Card.
  12. You need to mention PAN number if you are making payment for foreign travel exceeding 50,000 Rs or above.
  13. Quote PAN number if you are making payment of 50,000 Rs or above for the insurance premium payment.
  14. On purchase of gold jewelry worth 5 lac or above.
  15. PAN card is required if you want to obtain Sales tax, service tax or Excise registration number.
  16. Mention PAN number on rent receipt if rent value is exceeding 1 lac in financial year.
  17. PAN card is required if you are taking Fixed deposit exceeding amount 50,000 Rs.
  18. You need PAN number for the payment of Tax.
  19. While Filing Income tax return.
  20. You need PAN while submitting form 15G/15H.

You must be convinced  that PAN card is important document for financial transactions. If you have not got your PAN card follow the steps given in post – Apply and verify PAN card details online.

Points to Remember:-

  • You need to mention PAN number only if it is required.
  • Avoid mentioning PAN number anywhere else.
  • Do not give Xerox copy of PAN card in any other transaction. This is to reduce Benami/Hawala Transactions.
  • Avoid use of PAN card as identity proof.
  • If you lost your PAN card apply for new card. You can also file FIR to police in order to avoid liability.

Hope you find above information useful. Do share your views on above.

List of Certified Financial Planners (CFP) in India

Certified Financial Planners (CFP) – Who are certified financial planners (CFP) in India? How much fee do they charge? What should you look for while hiring a financial planner? If you are looking for these answer you are at right place. In this article, I will be sharing information about the point you should consider before hiring financial planner. I will also share a list of Certified Financial Planners (CFP) in India.

Who is a Financial Planner?

A Financial planner is an individual who helps you to deal with financial issues via proper planning. Just like we have doctors for medical problems, we have financial planners for financial problems.
To become a doctor, we have certification course MBBS, to become advocate we have certification course of LLB. Similarly in order to become financial planner certification course of CFP is offered by FPSB – Financial Planning Standards Board India.

Certified Financial Planners (CFP) are professional authorized to do financial planning. If you are planning to take help from financial planner you must opt for CFP (Certified Financial Planner).

Who is not a Financial Planner?

Today we find a lot of people advertise themselves as a financial planner. By education either they are CA, MBA (finance), ICWA or CS. Although they have knowledge in finance domain that does not mean that they can act as a financial planner.

In the same way Insurance agent, Mutual Fund agent, Wealth Manager or Relationship manager is not a financial planner. These people can definitely help for the selection of right investment product, but that does not mean that they are financial planners.

Financial planning is a personalized service. A financial planner makes a financial plan. This financial plan contains detailed information about the future financial goal, tax planning, insurance planning, investment advice, cash flow management, and lot more.

List of Certified Financial Planner CFP India

Where to Find Certified Financial Planners?

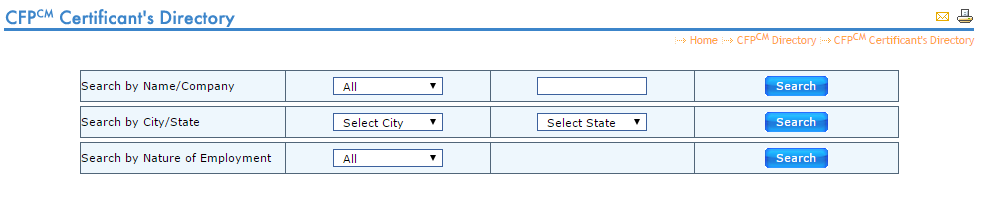
So, Big question is where to find certified financial planners? One good news is FPSB provides an online facility to search certified financial planners. Kindly visit FPSB website to search for certified financial planners nearby your area.

certified financial planners

You can find CFP based on Name/company, City/State and Nature of employment.

List of Certified Financial Planners in India

Here is a list of selected certified financial planners in India.

Sr No Name of Financial Planner Address Website
1 Mr. Jayesh R Parekh B-702, Ruchi Apt,
Devidas Road,
Borivali (West)  Mumbai
Maharashtra  400103
–
2 Mr. Ramesh Chouhan Max Secure Financial Planners Sector-20, CBD Belapur, Navi-Mumbai http://www.maxsecfp.in/
3 Mr.Amit Suri H-81/1, Shivaji Park, Punjabi Bagh,  Delhi 110026 http://amitsuri.com
4 Mr. Basavaraj 153, 19th Cross Road, 7th C Main Road, 3rd Block, 4th Stage,, Basaveshwara Nagar, Bengaluru, Karnataka 560079 http://basunivesh.com 
5 Soubhagya Patra BIIT Business Centre, # 257, First Floor, 9th ‘A’ Main , 3rd Block, Jayanagar, Bangalore – 560011  http://www.succinctfp.com
6 Mr.Sukhvinder Sidhu SCO-76, 2nd Floor, Mugal Canal
Karnal, Haryana – 132001
http://www.finlifecare.com
7 Salma Sony Flat No. 34, Zircon, Vatikaa Green City, Dimna Road, Mango, Within P.S Mango, East Singhbhum Jamshedpur, Jharkhand- 831018 https://salmasony.com/

Points you should consider before Hiring a financial planner

  • Education qualification
  • Experience
  • Knowledge and competence
  • Confidence
  • Trust and Credibility
  • Reference

How much fee Financial planner charge for financial planning?

Financial planner charge 150$ to 300$. This means 10,000 Rs to 20,000 Rs/- for financial planning. However, this fees varies from planner to planner.

Apart from financial planning these financial planner also offers services like tax planning, retirement planning, insurance planning, portfolio tracking advice etc.

Certified Financial Planner (CFP) or Registered Investment Advisor (RIA)

Apart from certified financial planner we have another category called as Registered Investment Advisor (RIA). An investment advisor registered with SEBI for offering investment advice on stock, mutual funds, bonds, ETF is known as RIA.

Registered Investment Advisors are authorized by SEBI to give investment advice relating to investing in, purchasing, selling or dealing in securities or investment products, and advice on investment portfolios containing securities or investment products for the benefit of the client and shall include financial planning.

Registered Investment advisors are equally capable of providing financial planning services, however, the decision of taking services is from them is entirely up to you.

RIAs generally charge fixed fee or hourly fees. Many RIA charges a percentage of the value of the assets they manage for a client.

Request-

If you have taken services from any financial planner and are satisfied with them. Do share with us so that we can expand the list of financial planners given here.

I would also appreciate it if you can leave a note sharing your experience in the comment section.