Blog Page 33

Critical Financing Inc Explains Why Reputation Now Matters as Much as Capital Access

0

Access to capital continues to play a vital role in determining business success in today’s competitive market. However, as the landscape of business lending evolves, companies are finding that their reputation plays an equally pivotal role in determining their financial prospects. A strong reputation can significantly influence a company’s ability to secure financing, with lenders placing growing emphasis on trustworthiness, transparency, and ethical conduct.

For businesses seeking growth opportunities, Critical Financing Inc emphasizes the evolving role of reputation in the lending process as essential. A positive reputation, built on years of good practices and reliable service, can lead to not only better financing terms but also a competitive edge in the marketplace. As the financial landscape becomes more sophisticated, companies must recognize that reputation is intertwined with access to capital, an asset that can no longer be overlooked.
reputation financial access

Changing Standards in Business Financing

Historically, businesses seeking funding were primarily evaluated based on their financials: profit margins, cash flow, and debt-to-equity ratios. A company’s financial health was often enough to secure funding from banks, investors, or other lending institutions. However, as the financial landscape has evolved, so too has the way lenders assess risk. In today’s market, reputation has become a key factor in the lending decision process.

Critical Financing Inc recognizes that as companies grow and expand into new markets, their reputation becomes a valuable intangible asset that lenders take into account. Lenders now look at how businesses operate within their industries, how they treat customers, handle financial transactions, and maintain corporate governance. This shift means that businesses must go beyond simply managing their financial statements; they must also be seen as trustworthy, ethical, and transparent. This trend highlights a broader industry shift where lenders place greater emphasis on a company’s overall reputation rather than relying solely on balance sheets.

In fact, businesses that have cultivated positive reputations are seen as less risky, more stable, and more likely to fulfill their financial obligations. As lenders become more discerning, businesses with strong reputations may find themselves with greater access to funding at better terms. The importance of maintaining a positive reputation cannot be overstated, and it has become an essential consideration in the modern business financing process.

Reputation and Its Impact on Risk Assessment

Risk assessment has always been central to the lending process, but in today’s business climate, this assessment has become much more nuanced. Lenders no longer rely solely on financial metrics to determine whether a business is worthy of investment. Instead, they now weigh factors such as company reputation, industry standing, and public perception. A business’s reputation can significantly influence how lenders perceive its overall risk. Companies that operate with integrity, engage in ethical business practices, and maintain a positive reputation among customers and stakeholders are viewed as lower-risk investments compared to those with questionable reputations.

Reputation is often seen as a reflection of a company’s internal practices and values. Lenders are keen to understand whether a business is likely to weather challenges, such as economic downturns, regulatory changes, or market shifts. A business with a reputation for upholding high standards is more likely to navigate these obstacles successfully. As Brandon Garcia, CEO at Critical Financing Inc, explained, “Access to capital is everywhere now, but access to trusted capital is not. Reputation is what separates firms that close deals from firms that build lasting relationships.” This highlights how, in today’s lending environment, a strong reputation can make a business more resilient and attractive to lenders.

For businesses, reputation management is not just about brand image; it’s a strategic tool that can lower the perceived risk for lenders. Companies that consistently deliver on promises, engage ethically with customers, and demonstrate financial responsibility are seen as more likely to thrive in the long term. This lowers the risk for lenders, making these businesses more attractive lending prospects. As lenders place increasing value on reputation, businesses that nurture positive, long-term relationships with stakeholders will find themselves better positioned to secure financing.

Power of a Strong Digital Reputation

In the digital age, a company’s reputation extends far beyond physical interactions. With social media, online reviews, and digital content shaping how the public perceives a business, reputation management has taken on a new dimension. Negative reviews, unresolved customer complaints, or misleading content online can significantly damage a business’s reputation and, by extension, its ability to secure financing.

Lenders are increasingly turning to digital platforms to assess a business’s reputation. They look for consistent positive feedback from customers, a well-maintained online presence, and transparent communication. This digital reputation is now a critical element in the lending process, as lenders are more likely to trust companies that maintain positive interactions online and have a track record of handling customer concerns effectively.

Critical Financing Inc highlights that businesses with strong digital reputations are more likely to be considered trustworthy by lenders. A robust online presence not only helps businesses build customer loyalty but also demonstrates transparency and accountability traits that lenders highly value. Companies must actively manage their online reputation to ensure that their digital presence aligns with their core values and ethical practices, ultimately enhancing their credibility in the eyes of potential lenders.

Reputation and Long-Term Sustainability

A strong reputation does more than just improve access to capital; it is also a key indicator of a business’s long-term sustainability. Lenders are increasingly focused on the long-term viability of businesses, and a company’s reputation is often seen as a reflection of its ability to adapt, innovate, and remain competitive.

A business with a positive reputation for ethical conduct, excellent customer service, and reliable performance is more likely to attract repeat customers, retain employees, and forge strong partnerships. This creates a stable foundation for future growth, which is highly attractive to lenders. Businesses with a good reputation are seen as more resilient in the face of market changes and economic fluctuations, making them safer investments.

Critical Financing Inc emphasizes that reputation plays an integral role in building a sustainable business. Companies that prioritize long term relationships with their stakeholders, including customers, employees, and investors, are more likely to remain competitive and maintain financial stability. Lenders value businesses that demonstrate the potential for steady growth, and a strong reputation is often the key to building that trust.

Leveraging Reputation for Better Financing Terms

For businesses with a well-established reputation, this intangible asset can be leveraged to secure better financing terms. Lenders may offer more favorable interest rates, larger loan amounts, or extended repayment periods to businesses that have demonstrated a track record of success, both financially and reputationally. A positive reputation gives businesses the confidence that they can negotiate more favorable terms, which can make a significant difference when securing capital for expansion or new initiatives.

Businesses with a positive reputation are also more likely to secure funding from a wider array of sources. In addition to traditional lenders, they may attract investors who are looking for businesses that align with their values. This increased access to funding options opens the door to better financing terms, ultimately allowing businesses to maximize the value of their capital.

Critical Financing Inc recognizes that businesses with strong reputations can differentiate themselves from competitors in a crowded market. By showcasing their ethical conduct, transparency, and customer-centric approach, businesses can attract the attention of lenders who are looking for low-risk investments. Reputation can, therefore, be a powerful bargaining chip when negotiating financing terms, ultimately helping businesses secure the capital they need to grow and scale.

Reputation as a Key to Securing Capital

Reputation has become a key factor for businesses seeking the capital required to grow in a competitive financial environment. While financial health remains vital, lenders are increasingly focusing on a company’s reputation, values, and track record when making funding decisions. Companies with a strong reputation for ethical conduct, transparency, and customer satisfaction are seen as more reliable and lower-risk investments, which increases their chances of securing financing. In today’s marketplace, businesses must realize that capital access alone is no longer sufficient. A solid reputation can open the door to better financing terms, access to more diverse funding sources, and long-term business sustainability.

Critical Financing Inc understands that businesses looking to thrive in the modern lending environment must prioritize both their financials and their reputation. A strong reputation not only facilitates the acquisition of capital but also strengthens relationships with stakeholders, builds trust, and positions a company for future success. By actively managing and cultivating their reputation, businesses can differentiate themselves from competitors, attract favorable financing terms, and lay the groundwork for long-term growth. Much like the practices Critical Financing Inc follows, companies that invest in reputation management alongside their financial health are best positioned to secure the capital they need to succeed in an ever-evolving business landscape.
Top P2P Crypto Exchanges for Zero-Fee Trading (2026)

Key Takeaways

  • Cost Efficiency: Zero-fee P2P exchanges allow 100% of your capital to be converted into crypto without platform commissions.
  • Top Pick: MEXC P2P leads the market in 2026 due to its 300+ payment methods and 99.9% anti-fraud security.
  • Security: Escrow services remain the standard for protecting both buyers and sellers in peer-to-peer transactions.
  • Flexibility: P2P trading supports diverse local payment options, including e-wallets and bank transfers, which are often unavailable on centralized exchanges.

Top P2P Crypto Exchanges

Understanding P2P Trading and Its Benefits

Peer-to-Peer (P2P) trading allows users to buy and sell cryptocurrencies directly with each other. Unlike traditional exchanges that use an automated order book, P2P platforms act as a marketplace where you select your preferred trading partner and payment method. To ensure safety, these exchanges use an escrow system: the platform locks the seller’s crypto until the buyer confirms payment.

Trading on a zero-fee P2P platform provides several distinct advantages:

  • Elimination of Fees: By removing the intermediary, users avoid the 0.1%–0.5% “taker” fees typical of centralized platforms. On MEXC P2P, for instance, a $100 trade stays exactly $100.
  • Flexible Payment Methods: Users can choose from hundreds of local options. This includes bank transfers, PayPal, and local e-wallets like Momo or ZaloPay, which are highly convenient for users in Vietnam.
  • Better Exchange Rates: Because prices are set by individual traders rather than a central engine, users can often find rates more favorable than the global market average.
  • Privacy and Accessibility: Many P2P platforms offer optional KYC for smaller transactions, allowing for a faster and more private onboarding process compared to traditional financial institutions.

Top P2P Crypto Exchanges for Zero-Fee Trading in 2026

1. MEXC P2P: The Leading Zero-Fee Gateway

MEXC P2P has established itself as the premier choice for zero-fee trading in 2026, combining high liquidity with a massive array of local payment integrations.

  • Zero-Fee Structure: MEXC maintains a strict 0% platform fee policy for P2P traders, ensuring that peer-negotiated prices are the only costs involved.
  • Extensive Payment Network: With over 300 payment methods, it caters specifically to local markets. In Vietnam, users can easily trade via popular e-wallets and all major domestic banks.
  • Advanced Security: The platform boasts a 99.9% anti-fraud rate. This is achieved through 24/7 real-time monitoring and a robust merchant verification system.
  • User Experience: For those prioritizing speed, MEXC offers an “Express” mode that matches you with highly-rated merchants instantly. Furthermore, the platform often hosts liquidity incentives; for instance, January 2026 saw deposit events with prize pools up to $200,000 for P2P users. Many traders also use these rewards to diversify into trending assets, often checking the PI Network price before executing their next move.
  • High Liquidity: MEXC ensures that even large trades can be executed with minimal slippage, matching the market rates of major pairs like USDT/VND or BTC/VND closely.
  • Flexibility: MEXC allows for optional KYC for smaller transaction volumes, providing a balance between regulatory compliance and user privacy.

2. Binance P2P

Binance continues to offer a high-liquidity environment for P2P trading. It supports over 100 fiat currencies and is particularly strong for high-volume traders who need deep order books. Their “Verified Merchant” program ensures a high level of reliability for VND transactions.

3. Bitania

Bitania is a specialized platform focused on privacy. It is often chosen by users who prefer trading without mandatory KYC. While its liquidity is lower than MEXC or Binance, it provides a streamlined experience for quick BTC and USDT swaps.

4. Bisq

As a decentralized exchange (DEX), Bisq offers full self-custody. There is no central authority, and trades are coordinated through a decentralized network. It is ideal for technical users who prioritize privacy and security.

5. Hodl Hodl

Hodl Hodl is a non-custodial P2P exchange that uses multisig escrow addresses. This means the platform never holds your funds directly. It is a preferred choice for large-scale, customized deals where users want to set specific contractual terms.

Comparison Table: 2026 P2P Leaders

Platform Zero-Fee Trades KYC Required Payment Methods Liquidity Key Highlight
MEXC P2P Yes Optional 300+ (Local/Global) Very High 99.9% Anti-Fraud
Binance P2P Yes Partial 100+ High Massive Volume
Bitania Yes No Global Majors Medium Privacy-First
Bisq Yes No Bank Transfers Medium Fully Decentralized
Hodl Hodl Yes No Local Varied Medium Multisig Escrow

Conclusion: While several platforms offer competitive services, MEXC P2P stands out as the most balanced option, offering the best combination of security, local payment flexibility, and a truly zero-fee environment.

How to Choose and Trade Safely

To maximize your success in P2P trading, consider the following criteria:

  1. Merchant Reputation: Always select traders with a completion rate above 95% and at least 100 successful trades.
  2. Liquidity: Ensure the exchange has enough active ads for your specific currency pair (e.g., VND/USDT) to get the best market rate. It is often helpful to monitor the real-time BTC USDT market to understand the broader market trend before finalizing your peer-to-peer transaction.
  3. Use Official Channels: Never move the conversation outside of the platform’s chat system. MEXC’s escrow only protects you if the trade is conducted within their secure environment.

Safety Pro-Tips:

  • Always verify that the name on the bank account matches the name on the P2P platform.
  • Only click “Payment Received” after you have physically logged into your banking app and verified the balance.

Conclusion

In 2026, zero-fee P2P trading has become an essential tool for cryptocurrency users looking to maximize their returns and maintain privacy. While platforms like Binance, Bisq, and Hodl Hodl offer unique advantages, ranging from high volume to full decentralization, MEXC P2P provides the most comprehensive package for the average trader.

Whether you are a beginner looking to buy your first USDT via e-wallet or a seasoned trader seeking tight spreads, selecting a platform that prioritizes security and cost-efficiency is key. As always, remember to trade only with highly-rated merchants and keep all communications within the official platform to ensure your assets remain protected.

Frequently Asked Questions

Why is MEXC P2P considered the top exchange in 2026?

It offers the highest number of payment methods (300+) and maintains a near-perfect security record while charging zero fees.

Is P2P trading on MEXC safe for beginners?

Yes, the combination of a 24/7 support team and a mandatory escrow system makes it one of the safest environments for those new to crypto.

Do I need to complete KYC to use these platforms?

On MEXC, KYC is often optional for small-scale trades. However, decentralized platforms like Bisq or Hodl Hodl require no KYC at all.

Daily SIP or Monthly SIP: Which One is Better?

Investing your money wisely is something everyone thinks about at some point. You might have heard about mutual funds and how they can help grow your savings over time. One popular way to get into mutual funds is through something called a SIP, which stands for Systematic Investment Plan. It’s like setting up a regular habit of putting money aside, but instead of just saving it in a bank, you’re investing it in funds that could earn more. But here’s the thing: SIPs come in different flavors, like daily or monthly. People often wonder which one is better. In this article, we’ll break it all down in simple terms, look at the pros and cons, and help you figure out what might work for you. We’ll go into a lot of detail so you can really understand the differences and make a smart choice.

Let’s start from the basics and build up from there. I’ll explain everything step by step, with examples to make it clearer. By the end, you’ll feel more confident about picking the right SIP for your situation.

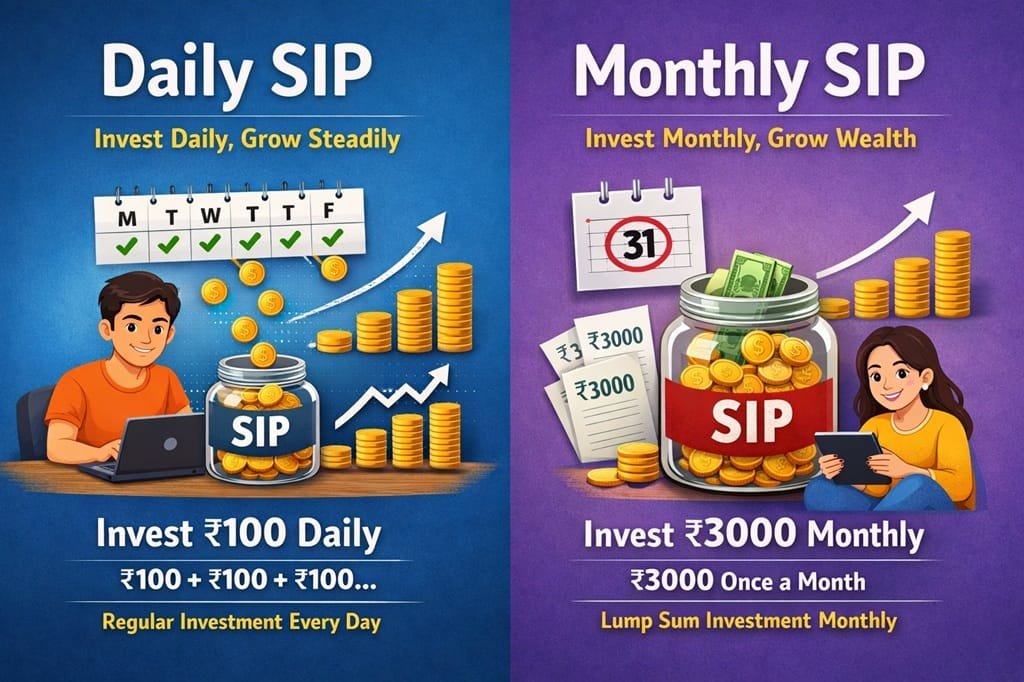
Daily SIP Monthly SIP

Understanding SIP 

First off, what exactly is a SIP? Imagine you’re trying to build a house. You don’t buy all the bricks at once if you can’t afford it; instead, you get a few every week or month until you have enough. A SIP works similarly for investing. It’s a method where you put a fixed amount of money into a mutual fund at regular intervals. This could be every day, week, month, or even quarter, but the most common ones are daily and monthly.

The beauty of a SIP is that it takes away the stress of trying to guess the perfect time to invest. Markets go up and down like a rollercoaster, and if you dump all your money in at a high point, you might lose out. With SIP, you’re spreading your investments out, so you buy more units when prices are low and fewer when they’re high. This is called rupee cost averaging, and it’s a big reason why SIPs are so popular.

For example, suppose you have Rs. 10,000 to invest each month. In a SIP, instead of investing it all at once in a lump sum, you commit to putting that money in regularly. Over years, this can add up big time because of compounding – that’s when your earnings start earning more earnings. It’s like a snowball rolling down a hill, getting bigger as it goes.

SIPs are great for beginners because they’re disciplined and automatic. You can set it up with your bank to deduct the money automatically, so you don’t even have to think about it. They’re also flexible – you can start with small amounts, like Rs. 500, and increase as your income grows. Mutual funds invested through SIPs can be in stocks, bonds, or a mix, depending on your risk level. If you’re young and okay with some ups and downs, go for equity funds. If you’re closer to retirement, maybe debt funds for stability.

Now, within SIPs, the daily and monthly options are the stars of the show. They both follow the same core idea but differ in how often you invest. Let’s dive into each one.

Exploring Daily SIP

A daily SIP is exactly what it sounds like – you invest a small, fixed amount into your mutual fund every single working day. Banks and markets don’t operate on weekends or holidays, so it’s typically Monday to Friday. For instance, if you choose Rs. 100 per day, that’s about Rs. 2,000 to Rs. 2,200 a month, depending on the number of working days.

This approach is like dripping water into a bucket steadily. It spreads your money across many days, which can help even out the bumps in the market. If the market dips on one day, you buy more units cheaply. If it rises the next, you buy fewer, but overall, it balances out.

Who might like this? People with daily income streams, like shop owners or freelancers who get paid often. Or even salaried folks who want to break their savings into tiny bits to make it feel less painful. It’s a way to build a habit of saving without noticing it much. Think about it: skipping one coffee a day could fund your daily SIP.

But it’s not for everyone. You need to ensure your bank account always has enough for those daily deductions. If it bounces, you might face charges. Still, many fund houses make it easy with apps that track everything.

Unpacking Monthly SIP 

On the other hand, a monthly SIP is more straightforward. You pick a date, say the 5th or 15th of every month, and a fixed amount gets invested automatically. This could be Rs. 5,000 or whatever fits your budget. It’s timed to match when most people get their salaries, so it’s super convenient.

Picture this: You get your paycheck, pay your bills, and the rest goes to savings and investments. A monthly SIP slots right into that routine. You don’t have to worry about daily checks – just one transaction per month.

This method still uses rupee cost averaging, but on a monthly scale. Over long periods, like 10 or 20 years, it can lead to solid growth. For example, if you invest Rs. 5,000 monthly in a fund that averages 12% returns, after 20 years, you could have over Rs. 50 lakhs. That’s the power of sticking with it.

Monthly SIPs are popular because they’re low-maintenance. Fewer transactions mean less hassle, and often lower fees from the fund company. It’s ideal for busy professionals who want to set it and forget it.

Daily SIP vs Monthly SIP

Now, let’s compare them side by side. Both are great, but they shine in different ways. I’ll use a table to make it easy to see, and then explain each point in more detail.

Feature Daily SIP Monthly SIP
Investment Frequency Every working day (small amounts, e.g., Rs. 100/day) Once a month (larger amount, e.g., Rs. 3,000/month)
Cash Flow Needs Needs small daily funds available; good for steady or irregular incomes Needs one lump sum monthly; aligns with salary cycles
Handling Market Swings Spreads risk over many days, reducing impact of single bad days Exposed to market on one day per month, but still averages over time
Ease of Management More transactions, requires daily balance checks Fewer transactions, easier to track and budget
Growth and Compounding Frequent investments mean quicker compounding starts Steady growth with monthly additions; compounding builds over years
Who It’s Best For Micro-savers, daily earners, or those wanting max risk spread Salaried workers, beginners, or anyone preferring simplicity

Let’s talk about these differences more. Frequency is the big one – daily means you’re in the market almost every day, which can feel more active. But monthly is like a monthly bill; it just happens.

On cash flow, if you’re a gig worker getting paid daily, daily SIP keeps your money working without sitting idle. But if you’re on a monthly salary, pulling out daily might leave your account low mid-month.

Market impact: Daily SIP is like buying groceries bit by bit – you catch sales more often. Monthly is buying in bulk once – you might miss some deals but it’s quicker.

Convenience wise, monthly wins for most because who wants to monitor daily? But apps make daily easier now.

Both grow your money through compounding, but daily might edge out slightly in volatile markets because you’re averaging more points.

Suitability depends on you. A young entrepreneur might pick daily; a office worker, monthly.

The Advantages of Going with a Daily SIP

Daily SIPs have some unique perks that make them appealing. Let’s explore them one by one, with real-life examples.

Better Rupee Cost Averaging in Action

This is the star feature. By investing every day, you’re hitting more price points. Suppose the market crashes on a Wednesday – you buy cheap that day. If it rebounds Thursday, you still invest, but at a higher price. Over a month, your average cost is lower than if you invested all at once. Studies show in choppy markets, daily can save you 1-2% on costs over years.

Building Discipline Through Small Steps

It’s like exercising – 10 minutes daily is easier than an hour weekly. Daily SIP forces you to save consistently. For someone starting out, Rs. 50/day feels doable, adding up to Rs. 1,500/month without shock.

The Magic of More Frequent Compounding

Compounding loves frequency. Each daily investment starts earning right away. Over 10 years, that extra day-by-day addition can mean thousands more. Use an online calculator to see: Rs. 100 daily at 10% vs. Rs. 3,000 monthly – daily often pulls ahead slightly.

Perfect for Tight Budgets

Not everyone has Rs. 5,000 spare monthly. But Rs. 200/day? Maybe. It opens investing to students or low-income folks. Start small, scale up.

Less Worry About Market Timing

No more “Is today the right day?” You’re always investing, so bad timing on one day doesn’t hurt much. It’s peace of mind in uncertain times.

Of course, daily isn’t perfect – more chances for failed deductions if funds are low, and some funds have minimums.

Why Monthly SIP Might Be Your Go-To Choice

Monthly SIPs are the classic option for good reasons. Here’s a deeper look at their benefits.

It’s All About Ease and Routine

Most lives run on monthly cycles: rent, salary, bills. Adding a SIP fits like a glove. Set it for the 10th, right after payday, and forget it. No daily fuss.

Saving on Fees and Costs

Each investment might have tiny fees. Daily means 20-22 per month; monthly, just one. Over time, savings add up, especially with no-load funds.

Still Great at Averaging Costs

Yes, it’s not daily, but monthly averaging works well. History shows markets trend up long-term, so monthly captures that without overcomplicating.

Ideal for Big Dreams Like Retirement

Planning for 20+ years? Monthly SIP builds steadily. Example: Rs. 10,000/month at 12% for 25 years could hit Rs. 1.7 crore. It’s reliable for goals like kids’ education or a house.

Simple to Fit Into Your Budget

Budgeting monthly is natural. You know your income, subtract expenses, allocate to SIP. No surprises.

Downsides? If the market tanks right before your date, you buy high. But over time, it evens out.

Is There a Huge Gap Between Daily and Monthly Saving?

Honestly, not really. Both are solid paths to wealth. The difference in returns is often tiny – maybe 0.5-1% over decades, favoring daily in volatile times. But consistency matters more than frequency.

Daily shines if you have variable income or love spreading risk max. It’s like nibbling snacks all day vs. one meal.

Monthly is king for simplicity. Most experts say start with monthly if you’re new; switch to daily if you want.

Run numbers with a SIP calculator. For Rs. 3,000/month equivalent, daily might give Rs. 10,000 more after 10 years at 12%. But effort counts too.

How Taxes Work for Both Daily and Monthly SIPs

Taxes don’t care about frequency – it’s the same rules. When you redeem (sell) your units, profits are capital gains.

For equity funds (mostly stocks): Hold under 1 year? Short-term gains at 15%. Over 1 year? Long-term at 10% on gains above Rs. 1 lakh.

Debt funds: Short-term (under 3 years) taxed at your slab rate. Long-term at 20% with indexation (adjusts for inflation).

Hybrid funds mix it. Always check fund type.

Taxes apply on withdrawal, not investment. So plan exits wisely. Use tools like ELSS for tax saves under 80C.

No difference between daily/monthly – it’s about holding period.

Key Things to Think About Before Choosing

Picking a SIP isn’t just daily vs. monthly. Consider these:

  • Your income pattern: Daily pay? Go daily. Monthly salary? Monthly SIP.
  • Effort level: Can you handle daily monitoring? If not, monthly.
  • Start small: Many funds let you begin with Rs. 100 daily or Rs. 500 monthly. Test waters.
  • Use calculators: Online tools show projections. Play with amounts, tenures, returns.
  • Fund choice: Pick based on goals. Equity for growth, debt for safety.
  • Emergency fund first: Don’t invest what you might need soon.
  • Review yearly: Life changes; adjust SIP.
  • Fees: Check expense ratios, exit loads.
  • Diversify: Don’t put all in one fund.

Think long-term. Investing is a marathon.

Wrapping It Up: Making the Right Pick for You

In the end, both daily and monthly SIPs are fantastic ways to grow your money without being a stock expert. Daily offers more averaging and discipline but needs more attention. Monthly is hassle-free, fits most lifestyles, and avoids daily balance worries. If I had to pick for most people, I’d say monthly – less chance of failed payments and charges if funds dip.

But hey, the best is the one you stick with. Start today, even small. Over time, you’ll thank yourself. If unsure, talk to a financial advisor or use apps like ClearTax for easy setups.

FAQs

Here are some FAQs to clear up doubts:

What sets daily and monthly SIP apart most?

Mainly the timing – daily is frequent small bits, monthly is one chunk. Both build wealth, but daily spreads risk more.

Do daily SIPs always beat monthly in returns?

Not necessarily. The gap is small, and market conditions matter. For long hauls, both perform similarly.

Who picks daily SIP?

Folks with daily cash, like business owners, or those wanting ultra-discipline.

Why monthly for salaried folks?

It matches payday, easier budgeting, fewer worries.

Taxes vary by frequency?

Nope, same for both – based on fund type and hold time.

Can I switch later?

Yes, most funds allow changing frequency or amount.

What’s minimum for each?

Varies, but often Rs. 100/day or Rs. 500/month.

Does daily mean weekends too?

No, only market days.

How to calculate returns?

Use online SIP calculators – input amount, tenure, expected return.

Is one riskier?

Both reduce risk via averaging, but daily might slightly less in volatiles.

There you have it – a full guide to help you decide. Investing is personal, so choose what feels right. Happy saving!

Income Tax Calculator FY 2026-27 (AY 2026-27) – Download

0

Budget 2026 did not revise the standard slab rates — meaning taxpayers use the same structure that was applicable in FY 2025-26 for FY 2026-27/AY 2027-28. To estimate tax for AY 2027-28 (i.e., for income earned Apr 2026–Mar 2027), you can use Income Tax Calculator 2026-27.

Hey there, if you’re like most people, dealing with income taxes can feel like a big headache every year. The rules seem to change just when you think you’ve got them figured out, and suddenly you’re scrambling to calculate what you owe. But don’t worry—I’ve put together this detailed guide based on the latest updates for the financial year 2026-27, which corresponds to the assessment year 2027-28. We’ll talk about everything from the basic ideas behind income tax to the newest tax slabs, and I’ll walk you through a handy Excel-based calculator that can make the whole process a lot simpler. This isn’t just a quick overview; I’m going to break it all down step by step, add some real-life examples, and share tips to help you save money on taxes without breaking a sweat.

First off, let’s clear up what FY and AY mean, because these terms pop up a lot and can confuse newcomers. FY stands for Financial Year, which is the period from April 1 to March 31 when you earn your income. For FY 2026-27, that’s April 1, 2026, to March 31, 2027. AY, or Assessment Year, is the year right after, when you file your tax returns and the government assesses what you owe based on that income. So, for the income you make in FY 2026-27, you’ll file taxes in AY 2027-28. Simple, right? Knowing this helps you stay organized and avoid last-minute surprises.

Now, why bother with an income tax calculator at all? Well, taxes aren’t just a flat fee on your salary. They depend on how much you earn, what deductions you claim (like investments or medical expenses), and which tax regime you choose. Without a tool to crunch the numbers, you might end up paying more than you need to or, worse, making mistakes that lead to penalties. That’s where this Excel calculator comes in—it’s free to download, easy to use offline, and updated with the changes from Budget 2026. It lets you plug in your details and see your tax liability instantly. Plus, it compares the old and new tax regimes so you can pick the one that saves you the most.

What’s New in Budget 2026? Key Changes to the Tax System

One of the biggest changes in Budget 2026 is the implementation of the Income Tax Act, 2025 from 1 April 2026. This replaces the old Income Tax Act of 1961. The intent is to simplify direct tax laws and make compliance easier for taxpayers and businesses.

Key structural impacts:

  • Simplified tax rules and law structure with fewer provisions.
  • Elimination of the traditional “previous year–assessment year” distinction; replaced with a single “tax year” concept.
  • Redesigned Income Tax Return (ITR) forms aimed at easier filing and reduced confusion.
  • Tax provisions, filing structure, and procedures are being rationalized to reduce litigation and disputes.

Income Tax Slabs for FY 2026-27

Tax slabs are basically brackets that determine how much tax you pay on different parts of your income. It’s progressive, meaning the more you earn, the higher the rate on the extra amount.

Contrary to expectations, the Budget did not change income tax slabs or basic rates for individuals for FY 2026-27 (AY 2027-28). Existing tax slabs under both the old and new regimes remain the same.

This means:

  • No revision in rate percentages.
  • Basic exemption limits and bracket thresholds stay unchanged.

The deadline for revising a filed income tax return has been extended from Dec 31 to Mar 31 (subject to a nominal fee). This is aimed at reducing stress for taxpayers who discover errors after filing.

Summary

Category What’s New / Changed
Income Tax Slabs Unchanged
New Income Tax Law Income Tax Act, 2025 effective 1 Apr 2026
ITR Filing Extended revisable return deadline to Mar 31
Compliance Simplified TDS/TCS & Nil Deduction Certificate
NRIs Higher overseas investment limit
Business Incentives Extended tax holiday at GIFT City
Rebate / Relief for Middle Class No change in 87A rebate

Option 1: The Old Tax Regime – For Those Who Love Deductions

This is the traditional system, and it’s sticking around because many people rely on it to reduce their taxes through various exemptions and deductions. It’s great if you have investments or expenses that qualify. The slabs vary based on your age, too, which is a nice perk for seniors.

For individuals under 60 years old, Hindu Undivided Families (HUFs), Bodies of Individuals (BOIs), and Associations of Persons (AoPs):

  • Income up to Rs 2.5 lakh: No tax at all. This is the basic exemption limit, so if your total income after deductions is below this, you’re off the hook.
  • From Rs 2.5 lakh to Rs 5 lakh: You pay 5% tax on the amount over Rs 2.5 lakh. For instance, if you earn Rs 4 lakh, tax is 5% of Rs 1.5 lakh, which is Rs 7,500. But there’s a rebate under Section 87A that can wipe this out if your income is under Rs 5 lakh.
  • From Rs 5 lakh to Rs 10 lakh: 20% on the excess over Rs 5 lakh. So, adding to the previous example, if you’re at Rs 7 lakh, you’d pay Rs 12,500 (from the first slabs) plus 20% of Rs 2 lakh (Rs 40,000), totaling Rs 52,500 before rebates.
  • Above Rs 10 lakh: 30% on anything over that. High earners feel this the most, but deductions can help soften the blow.

For senior citizens aged 60 to 80:

  • Up to Rs 3 lakh: Nil. A bit more breathing room than for younger folks.
  • Rs 3 lakh to Rs 5 lakh: 5%.
  • Rs 5 lakh to Rs 10 lakh: 20%.
  • Above Rs 10 lakh: 30%.

And for super seniors over 80:

  • Up to Rs 5 lakh: Nil. This recognizes that older people might have higher medical costs.
  • Rs 5 lakh to Rs 10 lakh: 20%.
  • Above Rs 10 lakh: 30%.

One thing to note: In the old regime, you can claim a bunch of deductions. Section 80C alone lets you deduct up to Rs 1.5 lakh for things like provident fund contributions, tuition fees, or home loan principal. Then there’s 80D for health insurance (up to Rs 25,000 for self and family), 80E for education loans, and more. If you’re renting, House Rent Allowance (HRA) can exempt a big chunk of your salary. Even donations to charities under 80G can lower your tax. It’s like a buffet of savings options, but you need to keep records.

Option 2: The New Tax Regime – Simpler and Often Cheaper

Here’s the slab breakdown:

Taxable Income (₹) Tax Rate
Up to ₹4,00,000 Nil
₹4,00,001 – ₹8,00,000 5%
₹8,00,001 – ₹12,00,000 10%
₹12,00,001 – ₹16,00,000 15%
₹16,00,001 – ₹20,00,000 20%
₹20,00,001 – ₹24,00,000 25%
Above ₹24,00,000 30%

Income Tax Calculator 2026

Income Tax Calculator FY 2026-27


Download Income Tax Calculator – Tax Year 2026 (FY 2026-27)

At its core, an income tax calculator is a tool that takes your

earnings, subtracts allowable deductions, applies the right slab rates, and spits out your tax due. It’s like having a mini accountant in your pocket. For FY 2026-27, with all these changes, a good calculator is essential because manual math can lead to errors—forget one deduction, and you overpay.

Why Excel specifically? Online calculators are fine, but they need internet, and some store your data (privacy concerns). Excel is offline, secure, and you can tweak it. For example, if you have unique income sources like freelance gigs or rental property, you can add formulas. It’s also great for “what-if” scenarios: What if I invest more in NPS? How does that change my tax?

Pros of using an Excel calculator:

  1. Spot-On Accuracy: Formulas don’t make mistakes. Enter data right, and you’re golden.
  2. Tailor-Made: Add rows for bonuses, side hustles, or even crypto gains (which are taxed differently).
  3. Time-Saver: No flipping through tax tables or apps. One file does it all.
  4. Long-Term Tracking: Save versions for each year, spot trends, and plan better.
  5. Free and Easy: No subscriptions—just download and go.

Cons? It assumes you know basic Excel, but even beginners can handle it with the built-in guides.

How to Get and Use the Income Tax Calculator for FY 2026-27

You can download this Excel tool from reliable sites like MoneyExcel.com—search for “Income Tax Calculator FY 2026-27” and grab the file. It’s a straightforward spreadsheet with cells for your inputs.

Key features include:

  • Dual-mode: Calculates for both old and new regimes side by side.
  • Comparison tool: See which regime saves you more at a glance.
  • Investment simulator: Play with deduction amounts to optimize.
  • Offline forever: No updates needed unless rules change big-time.
  • Basic scope: Handles salary, one house property; skips complex capital gains.

Using it is a breeze:

  1. Download and open in Excel.
  2. Enter your gross income (salary + other sources before deductions).
  3. Add deductions: Standard Rs 50,000 (old regime) or Rs 75,000 (new), 80C up to Rs 1.5 lakh, 80CCD(1B) for extra NPS, health premiums, etc.
  4. Input TDS (tax deducted at source from salary).
  5. Hit calculate—the sheet uses formulas like IF statements and VLOOKUP for slabs.
  6. Compare outputs and decide.

For example, plug in Rs 15 lakh gross, Rs 2 lakh deductions (old only), and see: Old might show Rs 1.5 lakh tax, new around Rs 1.2 lakh. Adjust as needed.

If you’re tech-savvy, you could even build your own from scratch. Start with columns for income brackets, rates, then use SUM and multiplication formulas. But the ready-made one saves time.

Common Deductions and Exemptions: Maximizing Your Savings

Even in the new regime, some perks remain, but the old one is deduction heaven. Here’s a deeper look at popular ones:

  • Standard Deduction: Rs 50,000 for old, Rs 75,000 for new—automatic for salaried.
  • Section 80C: Up to Rs 1.5 lakh for EPF, PPF, NSC, life insurance, home loan principal, kids’ tuition. Stack them wisely.
  • 80D: Health insurance—Rs 25,000 for self/family, extra for parents.
  • 80E: Education loan interest—no limit, great for students.
  • HRA: Based on rent paid, salary, and city—can exempt thousands.
  • Home Loan Interest: Under 24B, up to Rs 2 lakh for self-occupied house.

Tip: Start planning early. If your income is Rs 8 lakh, aim for Rs 1.5 lakh in 80C to drop into lower slabs. Use apps or advisors for personalized advice.

Real-Life Tips for Smart Tax Planning

Taxes aren’t just about calculation; it’s strategy. Here are some everyday ideas:

  • Invest Early: Don’t wait till March—spread investments to avoid rush.
  • Diversify Income: Side gigs? Classify right to minimize tax.
  • For Families: Use HUF for shared assets, split income legally.
  • Seniors’ Edge: Higher exemptions mean more savings—gift to parents if possible.
  • Avoid Pitfalls: Don’t fake deductions; audits hurt. Keep documents.
  • Future-Proof: With inflation, slabs might adjust—stay updated via government sites.

Remember, taxes fund roads, schools—paying right feels good.

Wrapping It Up:  

There you have it—a thorough rundown on the income tax landscape for FY 2026-27. Whether you stick with the old regime for its deductions or embrace the new one’s simplicity, the key is knowing your options. That Excel calculator is your best friend here—it demystifies the numbers and empowers you to make smart choices. Download it, play around, and see how small tweaks can lead to big savings.

I’ve shared this because I’ve seen friends stress over taxes, and a little knowledge goes a long way. If something changes (tax rules evolve), check official sources like the Income Tax Department website. Share this guide with your circle—it might just help someone out. Got questions? Drop them in email pros like those at MoneyExcel. Happy tax planning, and here’s to a prosperous year ahead!