Blog Page 24

Best Credit Cards for OTT & Movie Deals

India enjoys entertainment. From family movie plans on weekends to late-night streaming marathons, expenses on films and OTT services have become a routine aspect of life for many. However, the reality is that all this spending on entertainment accumulates more quickly than you realize. A ticket for a movie at a multiplex may range in price from Rs 200 to Rs 800. Incorporate popcorn, beverages, and a taxi fare, and a single movie night can swiftly exceed Rs 1,500. Add in monthly fees for Netflix, Amazon Prime, Disney+ Hotstar, SonyLIV, and Zee5, and you’re facing thousands of rupees each month, merely for entertainment.

Here is where the appropriate credit card can truly impact your situation. Multiple banks in India have created cards tailored to offer entertainment perks. They provide benefits such as Buy One Get One (BOGO) movie tickets, free OTT subscriptions, cashback on ticket purchases, and reductions at well-known food and beverage locations within cinemas. By using these cards wisely, you can save a considerable sum each year while still enjoying yourself.

In this article, we look at five of the best credit cards in India for entertainment benefits — covering everything from the fees and rewards to who each card is best suited for.
Credit Card OTT

Why Get a Credit Card for Entertainment?

Before jumping into the list, it is worth understanding why an entertainment-focused credit card makes sense. Here are a few simple reasons:

  • Movie tickets are getting more expensive. Premium multiplex chains like PVR INOX regularly charge Rs 300 to Rs 600 per ticket. A family of four can spend Rs 2,000 or more in a single outing. A credit card with BOGO or discount offers can cut that cost by half.
  • OTT subscriptions keep piling up. Most households today subscribe to at least two or three streaming platforms. That alone is Rs 500 to Rs 1,500 per month. Some credit cards offer complimentary annual subscriptions, which means you essentially get these for free.
  • Reward points and cashback can reduce your overall bill. Even if a card does not offer direct discounts on entertainment, accumulated rewards can be redeemed for vouchers and movie tickets later.
  • Annual fee vs actual savings — this is key. Many entertainment credit cards charge an annual fee of Rs 500 to Rs 5,000. But the value of benefits like free movie tickets, OTT memberships, and dining discounts can easily exceed the fee, making the card worth it.

Now, let us look at the top five cards.

1. Axis Bank MY ZONE EASY Credit Card

  • Joining Fee: Rs 500 (plus taxes)
  • Annual Renewal Fee: Rs 500 (plus taxes)
  • Best For: Movie lovers on a budget, first-time credit card users

Entertainment Benefits

The Axis Bank MY ZONE EASY Credit Card is a solid entry-level card that punches above its weight when it comes to entertainment. The card offers around 25% cashback on movie ticket purchases. Over the course of a year, this can add up to a maximum discount benefit of Rs 1,000 on movie tickets. While this may not sound like a lot, for someone who watches two to three movies a month, it is a meaningful saving.

This card also works well for those who want to save on everyday spending alongside entertainment. It offers 100% cashback (up to Rs 300) on the first utility bill payment made within one month of card issuance, which is a nice way to start things off.

Fuel Savings

One of the standout features of this card is its fuel benefit. Cardholders can save up to Rs 4,800 per year on fuel spends, which is a significant perk for anyone who drives regularly. If you combine the fuel savings with the movie discounts, the card’s effective annual value easily surpasses its Rs 500 renewal fee.

Who Should Get This Card?

This card is ideal for young professionals or students who are just entering the world of credit cards. If you go to the movies a couple of times a month and spend regularly on fuel, the Axis MY ZONE EASY Credit Card offers genuine value without burning a hole in your pocket. Its low annual fee makes it very accessible.

Things to Keep in Mind

The movie cashback is usually linked to specific platforms or conditions, so it is worth reading the fine print before assuming you will get 25% off every time. The maximum movie discount benefit in a year is capped at Rs 1,000, so heavy moviegoers may want to combine this card with another one that offers higher monthly limits.

2. Axis Bank MY ZONE Credit Card

  • Joining Fee: Rs 500 (plus taxes)
  • Annual Renewal Fee: Rs 500 (plus taxes)
  • Best For: Regular moviegoers, OTT subscribers, Swiggy users

Entertainment Benefits

The Axis Bank MY ZONE Credit Card is very similar to the MY ZONE EASY variant but often comes with richer entertainment benefits. This card is designed with lifestyle and entertainment in mind, making it a strong choice for people who regularly watch movies, order food online, and subscribe to OTT platforms.

One of its most attractive features is a complimentary SonyLIV Premium annual subscription. SonyLIV is home to popular content like The Kapil Sharma Show, ICC cricket matches, and a range of international shows. A SonyLIV Premium subscription is typically priced at around Rs 999 to Rs 1,499 per year, so getting it for free adds significant value on its own.

For movies, the card provides discounts on ticket bookings — often through the District app by Zomato or other partner platforms. You can get up to Rs 100 off on movie ticket bookings in a calendar month, which is a steady saving for regular film lovers.

Dining and Food Delivery Perks

Beyond movies and OTT, this card offers Rs 120 off on food orders from Swiggy, which is useful for those nights when you want to stay home and watch something on your streaming platform. There is also a 15% discount at partner dining restaurants.

Shopping Benefits

The card offers up to Rs 1,000 off on AJIO for a minimum transaction of Rs 2,999. If you are someone who shops for clothes and accessories online, this can be a nice bonus on top of the entertainment perks.

Who Should Get This Card?

The MY ZONE Credit Card is great for someone whose lifestyle revolves around movies, food delivery, and online shopping. The SonyLIV subscription alone makes it worthwhile for cricket fans and Indian content lovers. Paired with the movie discount and Swiggy cashback, you get consistent everyday value for just Rs 500 a year.

Things to Keep in Mind

The monthly movie discount is capped at Rs 100, and reward points are typically not earned on movie transactions with this card. If you watch movies frequently and want higher ticket savings, you may need to supplement this card with another option from this list.

3. HDFC Bank Platinum Times Credit Card

  • Joining Fee: Rs 1,000 (plus taxes)
  • Annual Renewal Fee: Rs 1,000 (plus taxes)
  • Best For: Entertainment-focused spenders, dining enthusiasts, OTT subscribers

Entertainment Benefits

If there is one card built specifically for entertainment lovers, it is the HDFC Bank Platinum Times Credit Card. This card comes loaded with perks across movies, OTT platforms, and dining, making it one of the most well-rounded entertainment cards available in India.

On movie tickets, you get a 50% discount when booking through BookMyShow. This discount applies to up to Rs 600 per transaction, and the benefit can be used for up to four tickets per month. At current multiplex prices, this means you could be saving Rs 200 to Rs 300 per ticket. Over a year, this adds up to thousands of rupees in savings.

In addition to the movie discount, you also get a one-time discount of Rs 50 on food and beverages when you purchase a movie ticket — a small but welcome bonus.

OTT and Streaming Benefits

The card comes with a complimentary Times Prime membership. Times Prime is a bundled subscription service that gives access to multiple OTT platforms including Zee5 and Gaana Plus, along with other lifestyle benefits. This membership alone is valued at several hundred rupees, and having it included in the card makes a tangible difference for streaming enthusiasts.

Dining Discounts

The HDFC Platinum Times Card gives you a 20% discount at over 1,000 partner restaurants across India. If you enjoy going out to eat, this benefit complements the movie discount perfectly for a complete evening-out experience. You also receive vouchers worth Rs 5,000 for dining, shopping, and apparel as part of the card’s benefits, adding further lifestyle value.

Additional Perks

The card also offers up to 5% cashback on utility bills and shopping spends, along with a 1% fuel surcharge waiver on transactions between Rs 400 and Rs 4,000, up to Rs 250 per month. These everyday perks make the card useful beyond just entertainment spending.

Who Should Get This Card?

This card is a strong choice for anyone who watches movies regularly at multiplexes and wants a card that rewards both entertainment and dining. If you tend to book through BookMyShow and eat out frequently, the combination of discounts and vouchers makes this card very cost-effective despite its Rs 1,000 annual fee.

Things to Keep in Mind

The 50% BookMyShow discount is a great deal, but it is a transaction-level discount capped at Rs 600, not a flat discount per ticket. So for very expensive premium seats, you may not get the full benefit. Also, the Times Prime membership is worth reviewing — it bundles several services, but not all of them may be relevant to you.

4. SBI Card ELITE

  • Joining Fee: Rs 4,999 (plus taxes)
  • Annual Renewal Fee: Rs 4,999 (plus taxes)
  • Best For: High spenders, frequent moviegoers, premium lifestyle seekers

Entertainment Benefits

The SBI Card ELITE sits at the premium end of the entertainment credit card spectrum. It is designed for people who spend regularly and want top-tier benefits across multiple categories. For movie lovers, this card is one of the best options available in India today.

The card offers free movie tickets worth Rs 6,000 every year. This roughly translates to about 15 to 20 free tickets depending on the multiplex and city, which is an enormous benefit for frequent moviegoers. The tickets are available once a month, with a discount of Rs 500 on up to two tickets per transaction. This means you effectively get two tickets every month at a heavily discounted rate.

OTT and Lifestyle Benefits

Beyond movies, the SBI Card ELITE provides complimentary memberships to multiple premium lifestyle services. It comes with a welcome benefit worth Rs 5,000 from popular brands including Yatra, Marks & Spencer, Shoppers Stop, and Westside. These vouchers can be used across dining, shopping, and travel categories.

The card also rewards loyal spenders with bonus reward points at milestones. When you spend Rs 2 lakh, Rs 3 lakh, and Rs 4 lakh annually, you receive 10,000 bonus reward points each time. Crossing Rs 5 lakh in annual spends earns you an additional 20,000 bonus points. These points can be redeemed for a range of benefits including more movie vouchers, travel bookings, and merchandise.

Travel Perks

This is where the SBI Card ELITE truly shines. The card comes with complimentary domestic and international airport lounge access, which is a significant perk for frequent flyers. You also get accelerated reward points on international spends, dining, and grocery purchases, making it useful for all kinds of spending.

Dining Benefits

Cardholders earn accelerated reward points on dining spends, and the card partners with several restaurant chains and food apps for additional discounts. Combined with the movie perks, you can build an entire entertainment budget around this one card.

Who Should Get This Card?

The SBI Card ELITE is best suited for someone who spends consistently and wants a card that rewards every rupee. If you watch movies at least twice a month, travel a few times a year, and dine out regularly, the total value of benefits easily exceeds the Rs 4,999 annual fee. This is a card for someone who treats their credit card as a tool to save money, not just a payment method.

Things to Keep in Mind

The high annual fee is a barrier for budget-conscious users. This card makes sense only if you are a consistent spender who can actually use the movie, travel, and lifestyle benefits. If movies are your only concern, a lower-fee card from this list may serve you better. But if you want an all-round premium card, the SBI ELITE is worth considering seriously.

5. RBL Bank Play Credit Card (BookMyShow RBL Play)

  • Joining Fee: Nil to low (check current offer)
  • Annual Renewal Fee: Varies
  • Best For: BookMyShow regulars, weekend moviegoers, food lovers

Entertainment Benefits

The RBL Bank Play Credit Card, often referred to as the BookMyShow RBL Play Credit Card, is co-branded with India’s largest online ticketing platform. If you regularly book movie tickets through BookMyShow, this card is designed specifically for you.

The welcome benefit alone is attractive — you receive a Rs 500 BookMyShow voucher on your first transaction within 30 days of getting the card. This means you can essentially book your first movie for free right after activation.

Once you are past the welcome bonus, the ongoing benefits are equally good. If you spend Rs 15,000 in a single transaction in a billing month, you receive two complimentary movie tickets worth up to Rs 250 each through BookMyShow. While the spending threshold is relatively high for a single transaction, it is useful for those who make large purchases or pay bills through their credit card.

Food and Beverage Discounts

Beyond the tickets themselves, the card gives you Rs 100 off on food and beverages at the theatre when you buy a monthly ticket via BookMyShow. If you are someone who cannot watch a movie without snacks, this is a practical saving on every outing.

Additional Perks

The card also offers a fuel surcharge waiver on transactions between Rs 500 and Rs 4,000, with a maximum waiver of Rs 100 per month. Like many other cards on this list, this makes it useful for everyday spending beyond just entertainment.

There are also discounts available on food delivery platforms, with cashback on orders from Swiggy. For those who love to order in on movie nights at home, this is an added plus.

Who Should Get This Card?

If BookMyShow is your go-to platform for booking movies, events, and plays, this card is an easy choice. The co-branded nature of the card means the benefits are deeply integrated with the platform, giving you maximum value on every booking. It is also a good option for those who attend live events like concerts, comedy shows, or theatre performances, as BookMyShow covers all of these.

Things to Keep in Mind

The Rs 15,000 single-transaction threshold for the complimentary ticket benefit is steep for everyday users. If your spending does not hit this level in a single transaction, you will mainly rely on the welcome voucher and food discounts. Also, the card’s benefits are quite focused on the BookMyShow ecosystem, so if you prefer PVR, INOX, or Paytm Movies for booking, you may not get the same level of value.

How to Choose the Right Card for You

Choosing the right entertainment credit card comes down to three simple questions:

How often do you watch movies?

If you go to the cinema once or twice a month, a card with a Buy One Get One or 25-50% discount offer will give you the most direct saving. Cards like the HDFC Platinum Times or the Axis MY ZONE EASY are perfect here.

How much do you spend on OTT each month?

If you subscribe to two or more streaming platforms, a card that offers complimentary memberships is incredibly valuable. The Axis MY ZONE’s free SonyLIV membership and the HDFC Platinum Times’ Times Prime subscription both cover a portion of your OTT bill.

What is your annual credit card budget?

If you want maximum value at a minimal cost, the Rs 500 annual fee cards from Axis Bank are the most efficient. If you are willing to pay more for a premium experience, the SBI Card ELITE offers unmatched entertainment and lifestyle benefits that can justify the Rs 4,999 fee for the right user.

Tips to Get the Most Out of Your Entertainment Credit Card

  • Always book through the partner platform. Most cards are linked to specific platforms like BookMyShow, Paytm Movies, or the District app by Zomato. Using the right platform ensures you get the discount or cashback.
  • Track your monthly limits. Most entertainment cards cap the movie benefits at a certain number of tickets or a fixed discount amount per month. Keep track of this so you do not miss out.
  • Activate your OTT subscriptions promptly. If your card comes with a complimentary OTT membership as a welcome benefit, activate it as soon as possible after card issuance, as these often have a limited window for activation.
  • Combine cards for maximum benefit. Many savvy users hold two cards — a budget card for daily entertainment and a premium card for travel. This combination covers all bases and maximises savings.
  • Use fuel and utility benefits regularly. Entertainment cards often include fuel waivers and utility bill cashback. Using these consistently helps you get more value beyond just movies and OTT.
  • Check for weekend-only restrictions. Some BOGO or Buy One Get One offers are valid only on weekends. If you prefer watching movies on weekdays, confirm whether your card’s offer applies.
  • Redeem reward points before they expire. Many cards have an expiry period of one to two years for accumulated reward points. Do not let them go to waste — redeem them for movie vouchers, travel, or shopping.

Final Thoughts

Entertainment is a big part of how Indians spend their time and money. Whether it is a blockbuster Friday release at the nearest multiplex or a quiet OTT binge over the weekend, these are the moments that make life enjoyable. A good credit card does not take away from those moments — it makes them more affordable.

Each of the five cards listed here serves a different kind of entertainment lover. The Axis MY ZONE cards are great for casual, budget-conscious users. The HDFC Platinum Times is perfect for the regular movie-and-dinner crowd. The SBI Card ELITE is for the high spender who wants the very best. And the RBL Play Card is a natural fit for anyone who lives on BookMyShow.

No matter which card you choose, the key is to align it with your actual spending habits. A card that perfectly matches how you spend is far more valuable than a premium card that you do not fully use. Read the terms and conditions carefully, understand the caps and restrictions, and pick the one that will genuinely make your entertainment life cheaper and more rewarding.

After all, the best movie is even better when you got the tickets for free.

Disclaimer: Credit card features, fees, and benefits may change at the discretion of the issuing bank. Please check the latest terms and conditions on the respective bank’s official website before applying for any card.
Money Market Vs Capital Market

To invest wisely or manage a business, it’s essential to understand the fundamentals of how money flows in the financial realm. Two major components of this world are the money market and the capital market. They may seem alike, but they function in quite distinct manners. One assists with immediate cash requirements, such as covering bills this month. The other backs significant, long-term projects, such as constructing a new manufacturing plant or increasing your savings over time.

Recognizing the distinction between money market and capital market is akin to realizing the difference between getting sugar from your neighbor for today’s tea and securing a mortgage to construct your home. Both entail financial aspects, yet the time, risk, and objectives differ. In this piece, we will clarify everything using plain language. We will discuss what each market entails, its operation, key characteristics, and provide a straightforward side-by-side comparison. Ultimately, you will gain confidence in understanding how these markets integrate into daily life and the Indian economy.

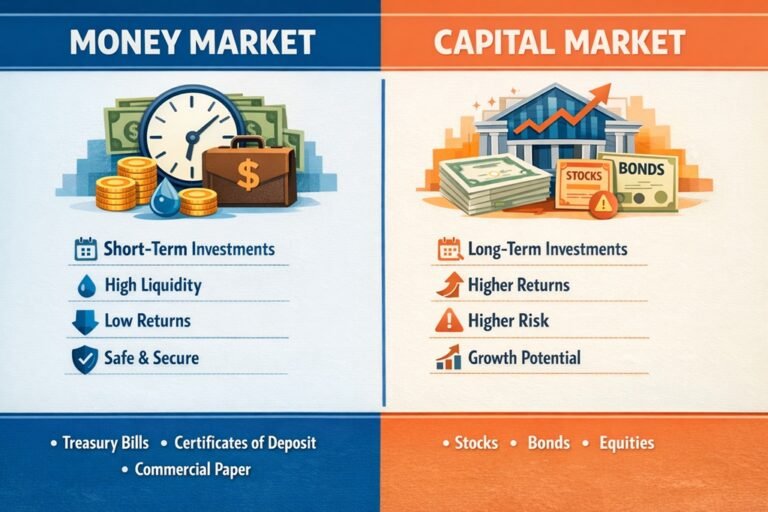
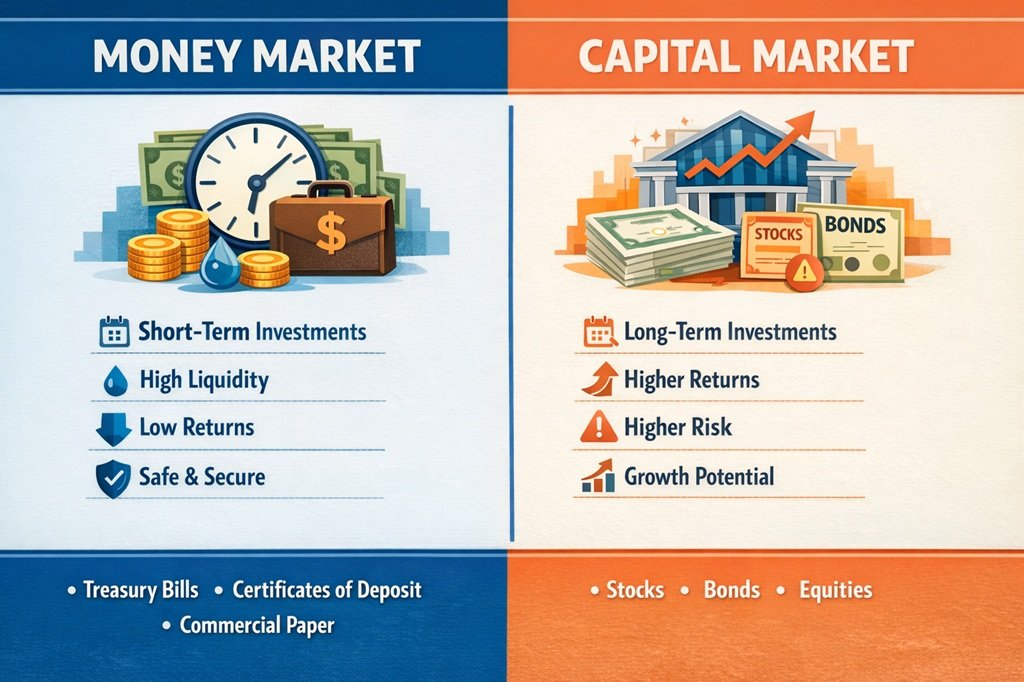
Money Market Capital Market

What is the Money Market?

The money market is all about short-term borrowing and lending. It deals with funds that usually come due in less than one year. Think of it as the place where banks, companies, and the government quickly fix their cash flow problems. Maybe a business needs money to pay suppliers right now, or a bank has extra cash it wants to lend out for a few days. This market keeps daily operations smooth.

In India, the Reserve Bank of India (RBI) plays a big role here. It makes sure the system runs safely. The money market is known for being safe and easy to enter or exit. You do not lock your money for long, so you get your cash back fast if needed.

Common instruments used in the money market include:

  • Treasury Bills (T-Bills): These are short-term government papers issued by the RBI. You buy them at a discount and get the full amount back after a few months. They are super safe because the government backs them.
  • Commercial Papers (CPs): Big companies with good credit issue these to borrow money for a short time, usually 7 to 365 days. No collateral is needed, but only strong firms can use them.
  • Certificates of Deposit (CDs): Banks issue these to people or companies who want to park extra money for a fixed short period and earn some interest.
  • Call and Notice Money: This is money lent for one day (call money) or up to 14 days (notice money). Banks use it to balance their daily cash needs.
  • Repurchase Agreements (Repos): One party sells securities to another and promises to buy them back soon at a slightly higher price. It is like a short-term loan using securities as guarantee.

The main goals of the money market are simple: provide quick liquidity, help with day-to-day funding, and keep the financial system stable. It acts like the oil that keeps the economy’s engine running smoothly every single day.

What is the Capital Market?

Now, let’s talk about the capital market. This is where long-term funds are raised and invested. Here, money stays locked in for more than one year—sometimes for many years or even forever. Companies and governments use it to fund big projects like building roads, expanding factories, or launching new products. Investors come here hoping for growth in their wealth over time.

In India, the capital market is regulated by the Securities and Exchange Board of India (SEBI). It has two main parts:

  • Primary Market: This is where new securities are issued for the first time. For example, when a company launches an Initial Public Offering (IPO), it raises fresh money directly from investors.
  • Secondary Market: This is the everyday trading place, like the National Stock Exchange (NSE) or Bombay Stock Exchange (BSE). Here, investors buy and sell already-issued shares, bonds, or other securities among themselves. No new money goes to the company, but the market stays active and prices are discovered.

Popular instruments in the capital market are:

  • Equity Shares (Stocks): Buying these makes you a part-owner of the company. You may get dividends and benefit if the share price rises.
  • Bonds and Debentures: These are like loans to companies or governments. You get fixed interest regularly and your principal back at the end.
  • Preference Shares: A mix of equity and debt—they give you priority for dividends but usually no voting rights.
  • Government Securities: Long-term bonds issued by the government for big infrastructure projects.
  • Mutual Funds and ETFs: These pool money from many investors and invest in a mix of stocks or bonds for long-term growth.

The capital market helps companies grow, creates jobs, and gives ordinary people a chance to build wealth. But it comes with ups and downs because prices can change a lot based on news, economy, or company performance.

Features of the Money Market

Here are some key things that make the money market special:

  • Short-term maturity: Everything ends in a year or less, so you get your money back fast.
  • High liquidity: You can turn investments into cash easily without losing much value.
  • Low risk and low return: Issued mostly by trusted players like the government or big banks, so the chance of loss is small. But you also do not earn huge profits.
  • Wholesale nature: Big players like banks, mutual funds, and corporations dominate. Small investors usually join through money market mutual funds.
  • Over-the-counter (OTC) trading: Deals often happen directly between parties, not on a formal exchange.

These features make the money market perfect for safety and quick access.

Features of the Capital Market

The capital market has its own personality:

  • Long-term focus: Funds stay invested for years, supporting big growth plans.
  • Higher risk but higher potential return: Share prices can go up a lot—or fall sharply.
  • Open to everyone: Retail investors (like you and me), institutions, and foreign investors all participate.
  • Formal exchanges: Trading happens on regulated platforms like NSE and BSE, with clear rules.
  • Wide variety of instruments: From simple stocks to complex derivatives.

This market is exciting for those who can handle some ups and downs in search of bigger rewards.

How Does the Money Market Work?

Picture this: A bank has extra cash on Monday but knows it will need it by Friday. It lends the money in the money market for a few days and earns a small interest. Or a company needs to pay salaries but is waiting for customer payments. It borrows through commercial paper.

Most deals happen over the phone or electronically between trusted parties. The RBI steps in to set interest rates and keep things stable. Transactions are fast, often unsecured (based on trust and credit rating), and focused on safety. The whole system helps the economy stay liquid so businesses do not stop working even for a day.

How Does the Capital Market Work?

In the capital market, things move slower but with bigger impact. A company that wants to expand decides to raise ₹500 crore. It can issue new shares in the primary market through an IPO. Investors buy them, and the company gets the money to grow.

Later, those investors can sell the shares on the stock exchange to others. Prices change every second based on supply, demand, company news, and economic conditions. SEBI makes sure companies share honest information so investors can decide wisely. Over time, successful companies reward shareholders with dividends and price growth. It is like planting a seed and watching the tree grow for years.

Key Differences Between Money Market and Capital Market

To make it crystal clear, here is a simple comparison:

Feature Money Market Capital Market
Time Horizon Up to 1 year More than 1 year
Purpose Short-term liquidity and working capital Long-term growth and capital formation
Instruments T-Bills, CPs, CDs, Repos, Call Money Shares, Bonds, Debentures, ETFs
Risk Level Low Higher
Returns Low but stable Potentially high but variable
Market Type Mostly OTC, informal Formal stock exchanges
Participants Banks, RBI, big corporations, mutual funds Retail investors, companies, FIIs
Regulator (India) RBI SEBI
Liquidity Very high Moderate to high (depends on the security)
Role in Economy Keeps daily operations running Drives long-term development and jobs

In short, the money market is for safety and speed. The capital market is for growth and patience. One is like a savings account for emergencies; the other is like investing in your future.

Advantages and Disadvantages

Money Market Advantages: Safe, easy to cash out, helps manage daily cash needs. Disadvantages: Low returns, not great for big wealth building.

Capital Market Advantages: Chance for high returns, helps companies grow, open to small investors through mutual funds. Disadvantages: Prices can drop suddenly, needs more research and patience.

Both markets are important. Smart investors often use both—one for safety, one for growth.

How Should You Choose?

If you need money soon or hate risk, look at the money market (maybe through liquid mutual funds). If you are saving for retirement or a child’s education and can wait, the capital market (stocks or equity funds) might suit you better. Always start small, learn, and maybe talk to a financial advisor.

Final Thoughts

The money market and capital market are two sides of the same coin. One keeps the economy breathing every day, while the other helps it grow taller over time. By knowing the difference, you can make better choices—whether you are a student, a business owner, or someone saving for the future.

Next time you hear about interest rates changing or a big IPO launching, you will understand exactly where that action is happening. Start small, stay curious, and let these markets work for you. Happy investing!

New Income Tax Rules 2026: 23 Key Updates

April 1, 2026 is not just the start of a new financial year — it marks the beginning of a completely new tax era in India. The old Income-tax Act, 1961, which has been the foundation of India’s tax system for over six decades, is being replaced by the new Income-tax Act, 2025. On top of that, several changes from the Union Budget 2025-26, announced by Finance Minister Nirmala Sitharaman on February 1, 2025, also kick in from this date.

Together, these changes touch almost every aspect of personal finance — from how you calculate your tax to how your company perquisites are valued, from the way you invest in gold bonds to how credit card transactions are tracked.

The good news is that income tax slabs and rates remain unchanged. But the way taxes are reported, claimed, and calculated has seen significant updates. Whether you are a salaried professional, a stock market investor, a mutual fund holder, or someone who sends money abroad, at least one of these changes will affect you.

In this article, we break down all 23 key income tax changes from April 1, 2026, in simple, plain language, so you know exactly what is different and what you need to do.

Income Tax Changes 2026

1. The Income Tax Act, 2025 Replaces the 1961 Act

This is the biggest change of all. The Income Tax Act, 2025 officially comes into force on 1st April 2026, replacing the Income Tax Act, 1961 — a law that had been in place for over 60 years.

The old Act had become very complicated over time, filled with hundreds of amendments, explanations, and provisos that made it hard for ordinary people to understand. The new Act uses plain, simple language and removes all the outdated provisions that were no longer relevant.

Key improvements under the new Act include:

  • Simpler language so that taxpayers can understand the law without needing a lawyer
  • Removal of redundant or obsolete sections that caused confusion
  • Fewer legal disputes because the rules are now clearer
  • Easier compliance for both individuals and businesses

If you previously found reading the Income Tax Act confusing, the new version is designed to be much more accessible.

2. ‘Tax Year’ Replaces the FY/AY System

Under the old system, you had to deal with two terms: Financial Year (FY), the year in which you earn income, and Assessment Year (AY), the year in which you file your return for that income. This dual system often confused taxpayers, especially when filling out forms or responding to notices.

The new law introduces a single concept called the ‘Tax Year.’ The Tax Year 2025-26 (April 1, 2025 to March 31, 2026) replaces both FY 2025-26 and AY 2026-27. Income earned in Tax Year 2025-26 will be reported and taxed in Tax Year 2025-26 itself. This makes the entire process more intuitive and easier to understand.

3. Income Tax Rules 2026 – Updated Deductions and Reporting

Along with the new Act, the Central Board of Direct Taxes (CBDT) has also notified the Income Tax Rules, 2026, which replace the old Income Tax Rules of 1962. These new rules bring several practical changes that directly affect salaried employees and other taxpayers.

The most notable updates include:

  • Education allowance deduction increased from Rs. 100 to Rs. 3,000 per month per child — a 30x increase that better reflects modern education costs
  • Hostel allowance deduction increased from Rs. 300 to Rs. 9,000 per month per child — again, a massive jump from figures set decades ago
  • Higher threshold limits for quoting PAN in specified financial transactions, making it easier for smaller transactions to go through without PAN requirements

The education and hostel allowance limits had not been updated in a very long time, so this revision is long overdue and brings real relief to working parents.

4. House Rent Allowance (HRA)

HRA is one of the most common tax exemptions claimed by salaried employees. From April 1, 2026, the rules around this exemption become stricter. If you pay rent to a landlord, you must now provide your landlord’s PAN and documented proof of rent payments such as rent receipts or bank transfer records when claiming HRA.

This change is aimed at reducing false HRA claims. If your landlord does not have a PAN, you may face difficulty claiming the exemption. It is a good idea to speak to your landlord in advance and collect the necessary documents before the financial year progresses.

5. More Cities Get 50% HRA Exemption — Metro City List Expanded

The HRA calculation allows employees in metro cities to claim 50% of their basic salary as the exempt component, while non-metro employees can claim only 40%. Until now, only Mumbai, Delhi, Kolkata, and Chennai were considered ‘metro cities’ for this purpose.

From April 1, 2026, the list of metro cities has been expanded to include Bengaluru, Hyderabad, Pune, and Ahmedabad. This is a major relief for employees in these cities, where rents are high but they were only getting 40% exemption earlier. If you live and work in any of these new metro cities, your HRA exemption could go up significantly.

6. Meal Card Tax-Free Limit Raised from ₹50 to ₹200 Per Meal

Many employers provide meal cards or food coupons to employees as part of their benefits package. Under the old tax regime, the value of free meals or non-alcoholic beverages provided by the employer was tax-free only up to ₹50 per meal. This limit was set years ago and had become unrealistic given today’s food costs.

From April 1, 2026, this limit has been raised to ₹200 per meal. So if your employer gives you a meal card and tops it up at ₹200 per working day, the entire amount is tax-free. For two meals a day, that is ₹400 per day, which can add up to meaningful savings over a full year.

7. Gift and Festival Voucher Exemption Raised to ₹15,000

Employers often give gift cards, vouchers, or coupons to employees during festivals, birthdays, or other occasions. Under the old rules, only ₹5,000 worth of such gifts per year was tax-free. Anything above that was added to your taxable income.

From April 1, 2026, this annual limit has been raised to ₹15,000 per employee. This applies under both the old and new tax regimes, which makes it broadly beneficial. If your employer gives you gift vouchers worth up to ₹15,000 in a year, you pay no tax on them.

8. Children’s Education and Hostel Allowances Revised Upward

Children’s education allowance has been stuck at ₹100 per month per child for many years. Similarly, hostel expenditure allowance was only ₹300 per month per child. These amounts were set decades ago and were completely out of sync with actual education and hostel costs today.

From April 1, 2026 (under the old tax regime), these limits are revised to:

  • Children’s education allowance: ₹3,000 per month per child (up from ₹100)
  • Hostel expenditure allowance: ₹9,000 per month per child (up from ₹300)

These new amounts are much more realistic and can provide meaningful tax relief for parents, especially in urban areas where education and boarding costs are high.

9. Company Vehicle Perquisites Get New Tax Values

If your employer provides you with a car for personal and professional use, the value of this benefit (called a ‘perquisite’) is added to your taxable income. Until now, the perquisite values were calculated on the basis of older figures that no longer reflected the cost of maintaining or using a vehicle.

From April 1, 2026, the new taxable perquisite values are:

  • Cars with engine up to 1.6 litres: ₹8,000 per month (previously lower)
  • Cars with engine above 1.6 litres: ₹10,000 per month (previously lower)
  • Driver provided by employer: ₹3,000 per month (previously lower)

These revised values apply to both old and new tax regimes. If your employer provides a large car plus a driver, the total taxable perquisite value would be ₹13,000 per month. This will increase the taxable salary of employees using company vehicles and should be factored into tax planning.

10. New PAN Application Rules — Aadhaar-Only Applications Stopped

The way you apply for a PAN has changed significantly. Earlier, there was an option to apply for PAN using only your Aadhaar number, without the usual documentation. This option has now been removed.

Instead, applicants must use specific new forms based on their category:

  • Form 93: For Indian individual taxpayers
  • Form 94: For companies registered in India
  • Form 95: For foreign individuals
  • Form 96: For foreign entities (companies, trusts, etc. registered abroad)

PAN is now mandatory for a range of high-value financial transactions, including cash deposits of ₹10 lakh or more per year in any bank account, purchase of a vehicle costing over ₹5 lakh, hotel or foreign travel bookings or event payments over ₹1 lakh, and purchase of immovable property worth more than ₹20 lakh. If you do not have a PAN and plan any such transaction, obtaining one becomes a priority.

11. Share Buybacks Now Taxed as Capital Gains

Earlier, when a company bought back its own shares from shareholders, the income received was treated as ‘deemed dividend,’ and the company paid a 20% tax on it under a special buyback tax. Shareholders did not pay any additional tax.

From April 1, 2026, this system changes. Buyback proceeds are now taxed in the hands of the shareholder as capital gains, similar to how profits from selling shares are taxed. The company will no longer pay buyback tax. Instead:

  • Corporate promoters: Pay 22% tax on buyback gains
  • Non-corporate promoters (individuals/HUFs): Pay 30% tax on buyback gains

For regular retail investors, capital gains tax (short-term or long-term, depending on how long they held the shares) will apply. This change makes buybacks less attractive as a tax-efficient way to return money to shareholders.

12. STT Hike on Equity Derivatives — F&O Traders Take Note

Securities Transaction Tax (STT) is charged every time you buy or sell securities on stock exchanges. From April 1, 2026, STT rates on equity derivatives have increased:

  • Futures: STT increased from 0.02% to 0.05%
  • Options: STT increased from 0.1% to 0.15%

This is a significant increase for active traders in the Futures and Options (F&O) segment. If you trade frequently, this higher STT will directly eat into your profits. For example, a trader who does ₹1 crore in futures turnover per month will now pay ₹50,000 in STT per month instead of ₹20,000 earlier. The increase is meant to generate additional revenue and may also discourage excessive speculation.

13. Sovereign Gold Bonds (SGBs) — Secondary Market Buyers Lose Tax Exemption

Sovereign Gold Bonds issued by the Reserve Bank of India offered a very attractive tax benefit: redemption proceeds at maturity were fully exempt from capital gains tax. This made SGBs one of the most tax-efficient gold investment options.

From April 1, 2026, this exemption applies only to bonds purchased at the original issue price (i.e., when the RBI first offers the bond for subscription). If you buy SGBs from the stock exchange (secondary market), the capital gains when you redeem or sell them will be fully taxable. This distinction is important — it means the tax advantage is now limited to primary market buyers.

14. Dividend and Mutual Fund Income — No Deduction for Interest

If you had taken a loan to invest in shares or mutual funds, you could earlier claim the interest paid on that loan as a deduction against your dividend or mutual fund income. This was a way to reduce your tax liability on investment income.

From April 1, 2026, this deduction is no longer allowed. Income from dividends and mutual funds will be calculated without deducting any interest expense, no matter how the funds were raised. This change will particularly affect investors who borrow to invest, making leveraged investing more expensive from a tax perspective.

15. Single Declaration for Non-Deduction of Tax

Earlier, investors had to submit separate Form 15G or 15H declarations (for non-deduction of TDS) for each investment — separately for mutual fund units, each dividend-paying stock, and each bond. This was an administrative burden, especially for investors with diversified portfolios.

From April 1, 2026, you can submit a single consolidated declaration that covers all your mutual fund units, dividends, and bonds. This reduces paperwork significantly and makes compliance easier for retail investors.

16. Simplified TDS on Property Purchase from NRIs

When you buy property from a Non-Resident Indian (NRI), you are required to deduct TDS (Tax Deducted at Source) before making payment. Until now, this required you to obtain a Tax Deduction Account Number (TAN), a separate registration that many buyers were unfamiliar with.

From April 1, 2026, this requirement has been removed. As a buyer, you can now deduct and deposit TDS using only your own PAN, without needing a TAN. This simplification removes a significant compliance barrier and makes property transactions with NRIs smoother and less stressful for buyers.

17. TCS Rates Rationalised

Tax Collected at Source (TCS) is collected by certain sellers at the time of payment for specified transactions. The rates for several categories have been revised:

  • Overseas tour packages: Reduced from dual rates of 5% and 20% to a flat rate of 2%
  • LRS remittances for education (through loans): Reduced from 5% to 2%
  • LRS remittances for medical treatment abroad: Reduced from 5% to 2%
  • Alcoholic beverages sold by retailers: Increased from 1% to 2%

The reduction in TCS on overseas tour packages is a welcome relief for travellers. If you are sending money abroad under the Liberalised Remittance Scheme (LRS) for your child’s education or for medical treatment, the TCS burden also reduces. Remember that TCS is not a final tax — it is adjustable against your total tax liability when you file your return.

18. Motor Accident Compensation

Interest received from Motor Accident Claims Tribunal (MACT) awards has always been a grey area in tax law. From April 1, 2026, this has been clearly settled: all interest received from motor accident claims tribunal awards is fully exempt from income tax.

Additionally, no TDS will be deducted on these payments, which means accident victims and their families will receive the entire amount without any tax being withheld. This is a compassionate and much-needed change that ensures people who have suffered loss or injury are not further burdened by tax complications.

19. Extended ITR Filing Deadlines for Non-Audit Cases

The deadline for filing Income Tax Returns (ITR) has been extended for certain categories of taxpayers:

Form Who Files It Due Date
ITR-1 Salaried individuals, pensioners 31st July
ITR-2 Individuals with capital gains, multiple properties 31st July
ITR-3 Individuals with business/professional income (non-audit) 31st August
ITR-4 Presumptive taxation filers (non-audit) 31st August
Tax Audit Cases Businesses and professionals needing audit 31st October

This extension gives non-audit businesses and trusts one additional month to complete their return filing. It reduces the pressure during the busy July period and gives more time to gather documents and reconcile accounts.

20. Credit Card Reporting, PAN Mandatory for New Cards

From April 1, 2026, high-value credit card spending will be reported to the Income Tax Department by card issuers. Specifically:

  • Payments over ₹10 lakh per year by non-cash methods (debit, credit cards, online transfers) will be reported
  • Any cash payment of ₹1 lakh or more in a single transaction will also be flagged

Additionally, a PAN is now mandatory for all new credit card applications. You also can use recent credit card statements (up to 3 months old) as valid proof of address when applying for a PAN. These changes are designed to improve tax compliance, reduce unreported high-value spending, and prevent tax evasion through credit card routes.

21. Revised Return Deadline Extended to 31st March

Until now, taxpayers had 9 months from the end of a financial year to file a revised return. From April 2026, this window has been extended to 12 months, meaning the new deadline to file a revised return is 31st March of the following year.

However, there is a small catch — if you file the revised return after 31st December, you will need to pay an additional fee. So while you have until March, it still pays to file sooner rather than later.

The deadline for belated returns (returns filed after the original due date) remains unchanged. If you miss your original deadline, you can still file a belated return with the applicable late fee.

22. New Income Tax Forms

The CBDT has revamped all income tax forms under the new rules. The form numbers you have been familiar with for years are changing. This is primarily a structural change to align with the new Act, but it can cause confusion if you are not aware of the new numbering.

Old Form Name New Form Name Purpose
Form 16 Form 130 TDS certificate for salary income
Form 16A Form 131 TDS certificate for non-salary income
Form 12BB Form 124 Declaration of deductions by employee to employer
Form 26AS Form 168 Annual tax credit statement

These new form numbers apply from FY 2026-27 onwards. Your employer will issue Form 130 instead of Form 16. Your bank or mutual fund will issue Form 131 instead of Form 16A. Keep this in mind when checking your documents.

23 New Utility Tool to Compare Old and New Tax Act Sections

The Income Tax Department has released an online utility tool to help taxpayers, accountants, and lawyers cross-reference section numbers between the old Income Tax Act, 1961 and the new Income Tax Act, 2025. Since the new Act has completely renumbered all sections, this tool is genuinely useful for professionals who need to map their existing knowledge to the new framework.

The tool is available on the official income tax website at incometaxindia.gov.in. Anyone filing taxes, advising clients, or simply trying to understand which section applies to them will find it helpful.

What Should You Do Now?

These 23 changes together represent one of the most comprehensive updates to India’s tax landscape in recent memory. Here is a quick action list to make sure you are prepared:

  • Salaried employees: Ask your employer for Form 130 (the new Form 16) and check the updated HRA calculations if you live in Bengaluru, Hyderabad, Pune, or Ahmedabad
  • F&O traders: Revisit your cost structure with the higher STT rates and factor them into your profitability estimates
  • SGB investors: If you bought SGBs from secondary markets, plan for capital gains tax at redemption
  • Collect your landlord’s PAN and rent receipts if you plan to claim HRA
  • Review your company car and driver perquisites with your HR or payroll team
  • Submit a consolidated 15G/15H declaration instead of multiple separate ones
  • Ensure your PAN is linked and active before any high-value transaction
  • If you use credit cards heavily, maintain clean records and ensure income is declared

Disclaimer: This article is for informational purposes only. Tax laws are subject to change. Please consult a qualified chartered accountant or tax advisor before making any financial or tax-related decisions.

Money Market Instruments in India: Types & Guide

Many individuals believe that investing means essentially tying up your money for an extended duration, similar to purchasing stocks or real estate that you retain for a lengthy timeframe. However, this is not always required. There are instances when you or a company might need cash back quickly, possibly to settle a bill with a supplier next month, or even just to keep extra funds for a brief duration. This is the point at which money market instruments become relevant.
These are basic financial tools that assist in enabling money borrowing and lending for a brief duration, typically less than a year. They make certain that the financial system operates effectively by allowing convenient access to cash while minimizing risks. Financial institutions, companies, and the government all need money market instruments for their immediate requirements. In India, the Reserve Bank of India oversees these matters to ensure fairness in all processes.

Imagine money markets as the “quick cash corner” in the world of finance. They differ from the stock market, where prices tend to fluctuate. In this one, it is all about safety, speed, and regularity. Let us take a closer look and find out what these really are, why they are important, and what types you need to be aware of.

money market

What are Money Market Instruments?

Money market instruments are short-term debt products that are used for borrowing and lending money, usually for a period of one year or less. They are popular due to the high liquidity of the product (you can quickly turn it into cash), the extremely low risks involved, and the easy returns that are generated.

These instruments are used by the government, banks, and large corporations when they need money quickly or want to invest excess funds for a short period of time. For example, a company may issue one of these instruments to raise money for paying salaries the next quarter, or a bank may buy one to earn a small but consistent profit on the funds it has in excess.

In India, the RBI controls the money market instruments tightly. This ensures that only reliable institutions issue the money market instruments and that the market remains a clean and transparent one. Some of the major money market instruments include Treasury Bills, Commercial Papers, Certificates of Deposit, and a few others. Each of these has a small but vital role to play in the economy in facilitating the free flow of money.

Features and Objectives of Money Market Instruments

To get a clear picture of money market instruments, it helps to look at what makes them special. Here are the main features that define them, explained in simple terms:

Short-Term Maturity: Most of these instruments last from a few days to one year at the most. This short timeline makes them ideal when you need money back quickly rather than locking it away for years.

High Liquidity: You can buy or sell them easily in the market without the price changing much. This means if an emergency pops up, you can turn the instrument into cash fast.

Low Credit Risk: They are usually issued by reliable entities like the government or strong banks and companies. So the chance of losing your money is very low compared to riskier investments.

Predictable Returns: You know in advance what you will earn. Some pay a fixed interest, while others give returns through a discount (you buy cheap and get full value back later).

Electronic Format: Almost everything happens online these days. Deals are settled quickly through electronic systems, which saves time and reduces errors.

Efficient Cash Management: Businesses and banks use these tools to invest extra money safely or to borrow just enough to cover short gaps in their cash flow.

Support Policy Implementation: The RBI uses these instruments to control the amount of money in the economy and to influence interest rates. This helps keep inflation in check and supports overall economic growth.

Trusted by Institutions: Banks, mutual funds, and large companies rely on them every day. Even regular investors can access some of them indirectly through liquid mutual funds or bank products.

These features make money market instruments a smart choice for anyone who wants safety and flexibility rather than chasing high-risk, high-reward gains.

Types of Money Market Instruments

India’s money market offers several instruments, each designed for different needs. Here is a quick overview in table form to help you compare them at a glance:

Instrument Typical Issuer Maturity Period Key Purpose
Treasury Bills (T-Bills) Government of India 91, 182, or 364 days Government short-term funding; risk-free option
Commercial Paper (CP) Corporates and Financial Institutions 7 days to 1 year Short-term working capital for companies
Certificates of Deposit (CDs) Banks and Financial Institutions 7 days to 1 year (banks); up to 3 years (FIs) Raise bulk deposits with better returns than regular savings
Repurchase Agreements (Repo) Banks and Financial Institutions Usually 1 to 14 days Short-term borrowing using securities as collateral
Call/Notice Money Banks and Primary Dealers Overnight to 14 days Daily liquidity management between banks
Banker’s Acceptance (BA) Corporates (guaranteed by banks) Up to 1 year, often 180 days Finance international trade deals

Now let’s look at each one in more detail so you can understand how they work in real life.

Treasury Bills (T-Bills)

Treasury Bills, abbreviated as T-Bills, are one of the safest money market securities in India. The Government of India issues them through the RBI. The idea behind them is to bridge short-term funding requirements. You can imagine them as an offer from the Government saying, “Lend me money now, and I will return the full amount after a few months.”

There are three types of T-Bills with maturity periods of 91 days, 182 days, and 364 days. You buy them at a discount, meaning you pay less than the face value. At maturity, you receive the face value. The difference between what you paid and what you receive is your profit. There is no separate payment for interest.

The major advantages include almost no risk because the government fully backs them. They are also liquid investments because they can be easily sold in the secondary market in case of any cash requirement before maturity. Banks and institutions always like T-Bills, but individuals can also invest in them through banks and stock brokers or the RBI’s retail direct platform. They actually act as a base for other interest rates in the market.

Commercial Paper (CP)

Commercial Paper is an unsecured short-term loan that big companies and financial institutions issue to meet immediate needs like paying suppliers or managing payroll. Only companies with a strong credit rating (usually A1 or better) can issue CPs. This keeps the risk under control.

Like T-Bills, CPs are sold at a discount and redeemed at face value. Maturity ranges from 7 days to one year. Because they carry slightly more risk than government paper, they usually offer a higher return.

Corporates like these because they can raise large sums quickly without going through the lengthy process of a bank loan. Investors, on the other hand, get better yields than savings accounts. However, liquidity is a bit lower than T-Bills, so you should plan to hold until maturity unless you are okay with possible price changes in the secondary market.

Certificates of Deposit (CDs)

 Certificates of Deposit are similar to fixed deposits but are issued for larger amounts and for a shorter period. They are issued by banks and financial institutions to raise funds for investors. You are promised a fixed rate of interest, and the money is locked in for a specific period, which is between 7 days and one year in the case of banks.

CDs are considered to be safer than bonds issued by companies because they are issued by banks. They promise a higher rate of interest compared to savings accounts or even fixed deposits. Both individuals and companies invest in CDs.

The only thing to remember is that if the money is withdrawn before the end of the period, a penalty is charged, although CDs can also be traded in the secondary market. They are a compromise between investors who want higher returns than what a savings account would give but also need the money back within a year.

Repurchase Agreements (Repo)

A Repo deal is a short-term loan backed by collateral, usually government securities. One party sells securities today and agrees to buy them back after a few days at a slightly higher price. The difference in price is the interest.

Repos are mostly used between banks and the RBI for overnight or up to 14-day liquidity management. They are very safe because of the collateral. The RBI also runs repo auctions to inject or absorb money from the banking system, which helps control inflation and interest rates.

For banks facing a sudden shortage of cash, repos act like a quick lifeline. The market is highly active and liquid, making it an important tool for daily financial housekeeping.

Call/Notice Money

Call money and notice money are the shortest of all the short-term money markets. Call money has to be paid back in one day, or one night. Notice money can be extended up to 14 days. Only banks and financial institutions are allowed to participate in this market.

The interest rate fluctuates every day depending upon how much cash is available in the system. If banks have more money, their interest rate will be low. If they are facing a cash crunch, their interest rate will be high. It is a high liquidity and low-risk investment because all parties are regulated. For a common man like us, we won’t be directly involved in this market, but this is what keeps the entire banking system stable and helps all of us.

Banker’s Acceptance (BA)

Banker’s Acceptance is a special promise made by a bank to pay a certain amount on a future date. Companies use it mainly for international trade. An exporter, for instance, feels safer receiving a BA because a bank stands behind the payment.

The bank “accepts” the bill after checking documents, and the instrument can then be sold in the market if the holder needs cash early. Maturity is usually up to 180 days. Risk depends on the bank’s strength, but overall it is considered low.

Though less common than the other instruments, BAs play a vital role in smooth cross-border business deals. They reduce payment worries for traders and keep trade finance flowing.

Things to Consider Before Investing

Money market instruments are generally safe and liquid, but you should still think carefully before putting your money in. Here are some practical points to keep in mind:

  • Match the maturity period with your actual short-term goals so you don’t end up needing cash before the instrument matures.
  • Always check the issuer’s credit rating – higher ratings mean lower chance of default.
  • Understand how you earn money: some pay interest, others work through discounts.
  • Make sure the instrument is liquid enough if you might need to exit early.
  • Think about tax rules on the interest or gains you make.
  • Confirm that the minimum investment amount fits your budget.
  • Stick to regulated instruments for better safety and clear rules.
  • Compare returns across different options so you pick the one that suits you best.

Taking a few minutes to review these points can help you avoid surprises and choose wisely.

Conclusion

Money market instruments are a practical and low-risk way to handle short-term money needs. They provide safety, quick access to cash, and steady returns without the stress of big market ups and downs. Whether you are a business owner managing daily expenses or an individual looking for a safe parking spot for surplus savings, these tools have something useful to offer. From rock-solid government T-Bills to flexible bank CDs, each instrument serves a clear purpose in India’s financial system.

By understanding them better, you can make smarter choices that protect your money while keeping it ready when you need it. In the end, they help keep the wheels of the economy turning smoothly for everyone.

FAQs

Q1. Which money market instrument is ideal for very short-term needs?

Call money and repos work best for periods as short as one day up to two weeks. They are super liquid and mainly used by banks and institutions to fix daily cash shortages.

Q2. Can money market instruments be part of an emergency fund?

Yes, Treasury Bills and Certificates of Deposit are excellent for this. They are safe and have clear maturity dates, so you know exactly when you can access your money.

Q3. Are there any risks in investing in these instruments?

Most carry very low risk, but Commercial Papers depend on the company’s health. Always check credit ratings to stay on the safe side. Government-backed options like T-Bills have almost no risk.

Q4. Do money market instruments offer fixed returns?

Some do, such as CDs that pay fixed interest. Others, like T-Bills and Commercial Papers, give returns through the difference between purchase price and face value.

Q5. What are some common money market instruments examples?

The most popular ones are Treasury Bills, Commercial Papers, Certificates of Deposit, Call/Notice Money, Repos, and Banker’s Acceptances. Each fits different short-term needs.