Blog Page 128

Sovereign Gold Bond Scheme – SGB Calculator Download

SGB Calculator – The Sovereign Gold Bond Scheme (SGB), introduced by the Government of India, offers an excellent opportunity for investors to earn returns on their gold investments without the hassle of physical storage. The SGB calculator given here is designed to help investors know the investment return on Sovereign Gold Bond so that they can plan their finances accordingly.

You must be aware that investing in gold is considered a safe and lucrative option. Gold serves as a protection against inflation. Every investor should include Gold in their investment portfolio. Therefore, it is logical to explore – What the Sovereign Gold Bond Scheme entails and the process of calculating returns with the SGB Calculator.

What is the Sovereign Gold Bond Scheme?

The Indian government introduced the Sovereign Gold Bond Scheme (SGB) in 2015. The goal is to offer investors a safer option to physical gold and decrease the country’s dependence on gold imports. SGBs are bonds issued by the government, valued in grams of gold, providing investors with both consistent interest income and potential capital growth tied to the gold market price.

Objectives of the Scheme

  • To provide a safe and effective investment option in gold for investors.
  • To decrease the need for physical gold and reduce gold imports.
  • To encourage the use of household savings for productive investments.

Key Features and Benefits

  • Denomination – SGBs are issued in denominations of one gram of gold and multiples thereof.
  • Interest Rate – Investors earn a fixed interest rate of 2.5% , payable semi-annually.
  • Tenure – The bonds have an eight-year tenure, with an exit option available from the fifth year.
  • Tax Benefits – Capital gains tax arising on redemption is exempted, and indexation benefits are available for long-term capital gains.

Sovereign Gold Bond (SGB) issue dates 2024-25

The RBI is expected to release the first installment (Series 1) of the Sovereign Gold Bond (SGB) 2024-25 in June 2024, based on historical patterns. In the past, the RBI has released four sets of SGBs during the financial year (April-March), beginning with the Series 1 release in June. Still, RBI has not made any announcements regarding the SGB 2024-25 series.

Sovereign Gold Bond 2023-24 Series IV

Subscription Period

Issue Date

Investment Limit

Interest

Issue Price Per Gram

12 February 2024 – 16 February 2024

21 February 2024

1 gm to 4 kg

2.5% per annum

Rs. 6,263

How the Sovereign Gold Bond Scheme Works 

Eligibility Criteria

Indian residents, including individuals, HUFs, trusts, universities, and charitable institutions, are eligible to invest in SGBs. You can also invest on behalf of a minor.

Application Process

Investors can apply through banks, post offices, Stock Holding Corporation of India Limited (SHCIL), and designated stock exchanges. Applications can be submitted in both online and offline modes.

SGBs can only be issued by RBI on behalf of the Central Government, and they are traded on the Stock Exchange.

You must adhere to the Know-your-customer (KYC) requirements while investing in SGB. Submitting copies of identity proof like PAN Card and address proof such as a passport, driving license or Voter’s ID card is required to complete KYC verification.

The interest rate is fixed at 2.5% per annum, payable semi-annually. The bonds have a maturity period of eight years, with an option to exit from the fifth year onwards.

SGB Calculator – Download

The Sovereign Gold Bond Scheme Calculator is designed to help investors estimate their returns from SGB investments. It provides a detailed breakdown of interest earnings, capital appreciation, and overall returns.

Using an SGB investment calculator allows investors to prepare for the future and guarantee they have enough savings to achieve their financial objectives.

The calculator uses the provided inputs to compute the total returns over the investment period, taking into account the fixed-interest earnings and potential capital appreciation based on the gold price trends.

Inputting Necessary Details

  • Enter the SGB Issue price per gram
  • Enter the Units in Grams.

Interpreting the Results

The calculator will display the total interest earned, the capital appreciation, and the overall returns at the end of the chosen tenure. It will also show the annual breakdown of interest earnings.

Click Here to Download SGB Calculator.

SGB Calculator Download

Advantages of Investing in Sovereign Gold Bonds

Security and Safety

  • SGBs eliminate the risks and costs associated with storing physical gold.
  • The bonds are backed by the Government of India, ensuring high security.

Interest Earnings

  • Apart from potential capital gains, investors earn a fixed annual interest rate, adding to the overall returns.

Tax Benefits

  • Interest earned is taxable as per the investor’s income tax slab.
  • Capital gains tax on redemption is exempted, offering significant tax advantages.

Why You Should Use SGB Calculator?

The calculator provides a precise estimate of returns, aiding in effective financial planning. Investors can compare the projected returns from SGBs with other investment avenues like fixed deposits, mutual funds, and physical gold. By projecting future returns based on current market conditions, the calculator helps in making informed investment decisions.

This means by using this calculator you can do accurate investment planning by comparing it with other investment options and knowing returns.

After understanding how SGB works and calculating returns you must be thinking about investing in SGB Online. Here are the steps –

How to Invest in SGB Online?

It is very easy to invest in the Sovereign gold bond online. The facility of investing in SGB is available at almost every commercial bank. The investment can be made via Internet banking or via a demat account.

Internet Banking – ICICI Bank

A step-by-step method for applying for a Sovereign Gold Bond online at ICICI Bank is given below. You can use a similar method for applying of SGB at other banks.

  • Login to your ICICI Online Internet banking account using your user id and password.
  • In the navigation bar, you will find the Investment and Insurance section. Click on Invest Online under this section.
  • Here you will find the option to Invest in SGB. Click on the Invest Now button.
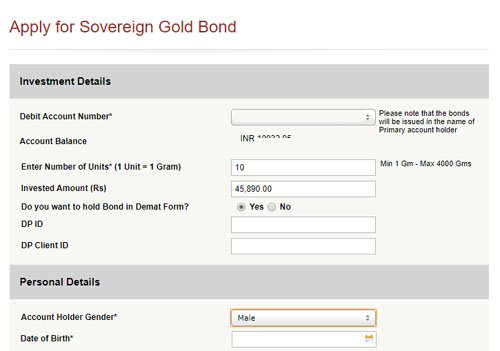
  • You will be prompted to enter the number of Units. Once you enter Units system will calculate the total investment amount.
Apply SGB Bond

  • Now you need to enter your DP ID and DP Client ID, if you want to hold bond in Demat Form.
  • Input your personal details including date of birth, and PAN Number, and Click on the submit button.
  • You will be taken to the payment page. Once you make a payment, the system will show confirmation message. The Units will be credited to your DP account shortly.

Demat Account

For Demat Account holders buying SGB is very easy. You need to log in to your online demat account. You will find the link to buying bonds in the FD/Bond section. Fill up the online form and make the payment online. The units will be credited to your demat account on the issue date.

For buying SGB online you will also get a discount.

Conclusion

The Sovereign Gold Bond Scheme offers a secure and profitable way to invest in gold. By using the Sovereign Gold Bond Scheme Calculator, investors can make informed decisions and maximize their returns. This tool is essential for accurate investment planning, enabling comparisons with other investment options, and forecasting future returns.

Whether you have a passion for gold or you’re seeking a reliable investment opportunity, utilizing an SGB investment calculator can assist in reaching your financial objectives. If you’re prepared to begin investing in gold and reap the benefits of SGB, it’s time to utilize an SGB calculator right away!

FAQ – Frequently asked questions

What is the minimum and maximum investment in SGB?

An investor/trust can buy 1gm to 4 Kg/20 Kg worth of gold every year. The limit is fixed for the financial year.

How is the interest on Sovereign Gold Bonds calculated?

Interest is calculated on the initial investment amount and paid semi-annually. The interest is simple interest at the rate of 2.5%.

Can I exit SGB before maturity?

Despite having a maturity period of 8 years, the Sovereign Gold Bond (SGB) can be cashed in early on coupon payment dates starting from the 5th year of issuance. There will be a fee of ₹150 plus an additional 18% GST for rematerialisation or redemption.

How accurate is the Sovereign Gold Bond Scheme Calculator?

The calculator provides an accurate estimate based on fixed interest rates. You can get the total interest amount earned on investment using this calculator.

Can I use the SGB calculator for partial withdrawals?

Typically, the SGB calculator is designed for full investment tenure calculations. For partial withdrawals, consult with your financial advisor for precise estimates.

Does the calculator account for tax benefits?

While the calculator estimates gross returns, tax implications can vary. It’s advisable to consult with a tax professional for personalized advice.
Best Banks to Invest in Fixed Deposits – Secure Your Savings

For Indian investors, fixed deposits (FDs) remain one of the most trusted and widely-used investment tools for growing their hard-earned savings. With their guaranteed returns, rock-solid safety and diverse tenor options, FDs provide the ideal risk-free avenue to build an income stream or accumulate a corpus.

However, not all fixed deposits are created equal. Interest rates can vary substantially across banks based on factors like size, credit rating, lending profile and business strategy. Identifying the right issuers currently offering the highest fd interest rates is key to maximising your earnings from this traditional yet powerful wealth compounding instrument.

If you’re looking to start or switch your fixed deposit investments, here’s a look at some banks and NBFCs offering high interest rates on fixed deposits:

FD Issuer Tenor Minimum Deposit (₹) Maximum Interest Rate (p.a.)
Mahindra Finance Ltd. 12 months – 60 months 5,000 8.35%
Bajaj Finance Ltd. 12 months – 60 months 15,000 8.85%
AU Small Finance Bank 7 days – 10 years 1,000 8.50%
YES Bank 7 days – 10 years 10,000 8.25%
PNB Housing Finance Ltd. 1 year – 10 years 10,000 8.05%
Ujjivan Small Finance Bank 7 days – 10 years 1,000 9.00%
Shriram Finance 12 months – 60 months 5,000 8.97%
ICICI Bank 7 days – 10 years 10,000 7.75%
HDFC Bank 7 days – 10 years 5,000 7.75%

Disclaimer: Interest rates are applicable on domestic term deposits under ₹2 Crores for senior citizens as of 8th May 2024. Rates are subject to change as per the bank/NBFC’s discretion and policies. Please refer to the official website for more details.

fixed deposit senior citizens

Key Factors to Consider While Choosing the Right Issuer

Here are some key factors to consider when selecting an issuer for your FD investment:

Interest Rates

This is undeniably a crucial factor. Higher interest rates translate to greater returns on your investment. However, resist the urge to chase the absolute highest rate blindly. Conduct due diligence and ensure the bank/NBFC offering the most attractive rate is reputable and financially sound. Here’s where a reliable FD interest calculator comes in handy. These online tools, readily available on many bank/NBFC websites, allow you to compare interest rates across different issuers for various tenors.

Financial Stability

The safety of your principal investment is paramount. Opt for issuers with a strong track record, healthy financial ratios, and a good credit rating. Look for those that are well-capitalised and have a minimal history of bad loans. This reduces the risk of the bank /NBFC facing financial difficulties that could potentially impact your ability to access your funds.

Deposit Insurance Coverage

DICGC or the Deposit Insurance and Credit Guarantee Corporation offers deposit insurance coverage for bank deposits, including FDs, up to ₹5 Lakhs per depositor per bank. This acts as a safety net in case the bank encounters financial trouble. While exceeding the insured limit isn’t necessarily unwise, be aware of the potential risks involved and diversify your FDs across multiple banks if investing a larger sum.

FD tenor

The tenor, or lock-in period, of your FD determines how long your money will be inaccessible. Banks and NBFCs generally offer FDs with varying tenors, ranging from a few months to several years. Consider your investment horizon. Aligning your FD tenor with your financial goals is crucial. For short-term needs, shorter tenor FDs might be suitable. Longer tenors, however, benefit from the power of compounding interest, leading to potentially higher returns.

Additional Features and Convenience

While core considerations like interest rates and safety are essential, some issuers offer additional features that can enhance your FD experience. These may include online account management tools for easy tracking of your FDs, the ability to invest through mobile banking apps, or the option for premature withdrawals (though often with a penalty). Consider which features hold value for you and factor them into your decision.

Building a Well-rounded Portfolio

For optimal growth and risk management, consider creating a diversified portfolio with a mix of investments that cater to different risk profiles. Here are some additional asset classes to explore alongside FDs:

  • Mutual Funds: Mutual funds offer a convenient way to pool your money with other investors and gain exposure to a diversified group of stocks, bonds, or other assets. Depending on your risk tolerance, you can choose from various mutual fund schemes, ranging from conservative to aggressive.
  • Stocks: Investing directly in stocks allows you to potentially earn higher returns than FDs, but it also comes with a higher degree of risk. Stock prices can fluctuate significantly, and there’s always the possibility of losing some or all of your investment. This option is best suited for investors with a longer investment horizon and a willingness to tolerate market volatility.
  • Real Estate: Real estate can be a valuable asset class, offering the potential for rental income and capital appreciation over the long term. However, it’s a relatively illiquid investment, meaning it can take time to sell your property and access your funds. Investing in real estate also requires a significant initial investment.

Fixed Deposits are a valuable tool for risk-averse investors seeking a safe haven for their savings and predictable returns. By considering factors like interest rates, bank reputation, deposit insurance coverage, tenor options, and additional features, you can select an issuer that aligns with your specific needs like Ujjivan fd. Consulting a financial advisor can provide valuable guidance in navigating the investment landscape and achieving your financial aspirations.

A Guide to Public Adjusters and the Claims Process

Insurance claims process can be daunting and confusing to the average homeowner or business owner, especially after experiencing significant property damage due to a natural disaster or other unforeseen events. There are no better experts to help you understand the claims process than public insurance adjusters.

A public insurance adjuster is a licensed professional who represents a homeowner or business owner in the insurance claims process to ensure that they maximize the benefits of their claim for property losses.

public insurance adjusters

Initial Consultation

Once you find a reputable public insurance adjuster in your area, you will have an initial consultation with  them. This is  where  they will conduct a preliminary inspection of the property to understand the extent of the damage. They can then examine your insurance policy to determine coverage, limits, and exclusions. If you have concerns or questions about your policy, a public insurance adjuster is there to help you understand everything you need to know. They will listen to your concerns and explain how they can assist you further throughout the claims process.

Detailed Damage Assessment

A detailed damage assessment is crucial to maximizing compensation from your insurance. Your public insurance adjuster will conduct a thorough inspection of your property, documenting all damage that could help you with your claim. This includes taking photos and videos, listing damaged items, and estimating repair costs. Photos and videos provide visual evidence of the damage. Creating an inventory of all affected items, from structural components to personal belongings helps ensure that no stone is left unturned. Your public insurance adjuster will then work with contractors and other professionals needed to help replace or fix damage and estimate the cost of these repairs or replacements.

Understanding Your Insurance Policy

Understanding the nuances of your insurance policy is crucial. A public insurance adjuster works on your behalf, helping you understand your policies better to get you the compensation you need to recover after property damage or loss. They can clarify coverage details, limits, and exclusions and determine what you are entitled to under your policy.

Preparing and Submitting the Insurance Claim

With all the necessary information in hand, the public adjuster will prepare and submit the insurance claim. This includes all documented evidence, estimates, and a compelling argument for the claim amount. Your public insurance adjuster will ensure that all forms and documents are correctly filled out and submitted to the insurance company.

Negotiation

Some cases of filing insurance claims require further negotiation to get you the maximum amount you can receive from your policy. The public adjuster will handle all communications and negotiations with the insurance company. They respond to inquiries from the insurance company and provide additional information as needed. It is reassuring to homeowners or business owners that public insurance adjusters are there to advocate on their behalf for a fair settlement, based on the documented evidence and policy terms. In the event of a disaster, you will need their expertise to file your claim.

Settlement

Public insurance adjusters are not done once the settlement is reached. They will stay with you to ensure it is fair and adequate to cover all damages and losses. They may even need to provide guidance on whether to accept the offer or continue negotiations. Because they work on your behalf, it’s encouraged to ask follow up questions and make sure you have a full understanding of where you are in the claims and settlement process.

Follow-Up

A good public adjuster will follow up to ensure you are happy with the settlement and that all repairs or replacements are in motion to help you recover your property. They may also assist with any additional claims or issues that arise during the rebuilding process.

Navigating the insurance claims process after a significant loss can be overwhelming, but a public adjuster can make it much more manageable. From the initial assessment to the final settlement, public adjusters work diligently to ensure you receive the maximum compensation you are entitled to under your policy. By understanding each step of the process, you can make informed decisions and feel confident in your ability to recover and rebuild.