A sole proprietorship is among the easiest forms to set up a business in India, owned and managed by an individual person without the complexity involved in a firm or LLP. One may do online registration of a sole proprietorship business using the relevant registrations and licenses of the business, depending on its nature and the state concerned, such as Udyam (MSME) registration, a Shops and Establishment license, or a professional tax registration.
Registration under GST is different from registering as a sole proprietorship business. It will be necessary only when the proprietor is bound to get GST registered due to the GST Act, or when he opts to get himself GST-registered voluntarily. Whether GST registration will be applicable or not depends on certain criteria including turnover, nature of supply, place of business, and compulsory registration criteria.
What Is GST Registration for a Sole Proprietorship?
GST registration is the process by which a business is formally recognised under the Goods and Services Tax regime, enabling it to collect GST on taxable supplies and, subject to eligibility, claim input tax credit on GST paid on its purchases and expenses.
On successful registration, the business is issued a GSTIN (Goods and Services Tax Identification Number), a unique 15-digit alphanumeric number that serves as the business’s identifier under GST for all filings, invoices, and communications with the tax authorities.
For a sole proprietorship, the GSTIN is directly linked to the proprietor’s own PAN, since a proprietorship has no separate legal identity apart from its owner. The first ten digits of the GSTIN are derived from the proprietor’s PAN, followed by digits denoting the state code and registration sequence. This is an important distinction from companies or LLPs, which register using a separate business PAN.
It’s worth being clear on one point: a sole proprietorship and its GST registration are not two separate legal entities. The proprietor remains personally responsible for the business and its GST compliance, and the GST registration is simply a compliance layer attached to the same individual and business.
Finally, GST registration is state-wise, not nation-wide. If a proprietor operates from more than one state, a separate GST registration is generally required for each state in which the business has a place of operation, even though all registrations are linked to the same PAN.
Is GST Registration Mandatory for a Sole Proprietorship?
GST registration is not automatically mandatory for every sole proprietor. Applicability depends on turnover, the nature of the business, and certain provisions that apply irrespective of turnover.
GST Registration Based on Turnover
Aggregate turnover refers to the total value of all taxable supplies (excluding inward supplies taxed under reverse charge), exempt supplies, exports, and inter-state supplies made by a person under the same PAN, computed on an all-India basis, not turnover from a single state or a single line of business.
Registration thresholds depend on the nature of supply and the state in which the business operates:
- Suppliers of goods: registration is generally required once aggregate turnover exceeds ₹40 lakh in a financial year, in most states.
- Suppliers of services: registration is generally required once aggregate turnover exceeds ₹20 lakh in a financial year.
- Special-category states: several north-eastern and hill states have lower limits, typically ₹20 lakh for goods and ₹10 lakh for services.
These thresholds have been revised over time through government notifications, so it’s important to rely on the current applicable limits rather than older GST FAQs or outdated blog references, and to reconfirm the limit specific to your state and nature of supply before assuming you’re below (or above) it.
Mandatory Registration in Certain Cases
Turnover is not the only trigger for registration. Under Section 24 of the CGST Act, certain categories of persons must register for GST regardless of turnover, including (among others):
- Persons making inter-state taxable supplies, subject to specific exceptions and notified relaxations for certain small suppliers
- Casual taxable persons
- Persons liable to pay tax under the reverse charge mechanism
- E-commerce operators required to collect tax at source
- Persons supplying goods or services through an e-commerce operator, subject to applicable exceptions
- Input Service Distributors
- Non-resident taxable persons
- Suppliers of OIDAR (online information and database access or retrieval) services to unregistered persons in India, from outside India
Because several of these provisions carry specific conditions and notified exceptions that are periodically amended, proprietors falling into any of these categories should verify current applicability for their exact business model rather than assuming the general threshold rules apply to them.
Voluntary GST Registration
A proprietor whose turnover is below the applicable threshold, and who is not covered by any compulsory-registration provision, can still choose to register voluntarily. Common reasons include:
- B2B business requirements, many businesses prefer to transact only with GST-registered vendors.
- Eligible input tax credit, registration allows claiming credit on GST paid on business purchases, reducing overall tax cost.
- Business credibility, a GSTIN can lend legitimacy to a small or newly started business.
- Expansion plans, registration is often a practical prerequisite for scaling into new states, channels, or larger clients.
- Customer/vendor requirements, certain marketplaces, corporate buyers, or tenders require a valid GSTIN before onboarding a supplier.
Voluntary registration brings the same ongoing compliance obligations as mandatory registration, so the decision is worth weighing against the administrative effort it introduces.
GST Registration vs Sole Proprietorship Registration Online
| Factor | Sole Proprietorship Registration | GST Registration |
| Purpose | Establish/identify the business through applicable registrations | Register under GST |
| GSTIN | Not provided | Provided after registration |
| Applicability | Depends on business requirements | Depends on GST provisions |
| Turnover criterion | Not necessarily applicable | Relevant in determining GST liability |
| Tax collection | Does not by itself authorise GST collection | Allows GST collection subject to applicable law |
| Ongoing compliance | Depends on registrations obtained | GST returns and other applicable compliance |
Eligibility for GST Registration as a Sole Proprietor
At a basic level, a sole proprietor is eligible to apply for GST registration when:
- The proprietor holds a valid PAN (used as the basis for the GST registration itself)
- The business is carrying out, or intends to carry out, taxable supplies, where applicable
- The principal place of business is clearly identified, with supporting address proof available
- The required business and identity information, such as business name, nature of activity, and contact details, is available and accurate
- The applicant meets the applicable GST registration criteria, whether based on turnover, a compulsory-registration provision, or a voluntary application
During the application, the GST portal captures detailed information across several categories, including business information, promoter/proprietor details, authorised signatory details, principal place of business, additional places of business (if any), the goods and services supplied, and, for most applicants, Aadhaar authentication of the proprietor.
Documents Required for GST Registration for a Sole Proprietorship
Identity and PAN Documents
- PAN of the proprietor, since a proprietorship uses the owner’s own PAN, this is central to the application
- Aadhaar, or other applicable identity/verification details, used for Aadhaar-based authentication
- Photograph of the proprietor, in the format specified on the portal
Business Address Proof
Depending on the nature of the premises, one or more of the following are typically required as proof of the principal place of business:
- Electricity bill
- Property tax receipt
- Municipal/khata document
- Rent or lease agreement (where the premises are rented)
- Consent letter (where premises are shared or provided by a family member/relative without a formal lease)
- Government-issued document establishing ownership or occupancy, where applicable
The GST portal’s current document checklist specifically lists these categories of proof for the principal place of business, and the exact combination required depends on whether the premises are owned, rented, leased, or shared.
Other Details
- Mobile number (for OTP verification)
- Email ID (for OTP verification and portal communication)
- Bank account details, where applicable, such as a cancelled cheque, bank statement, or passbook copy
- Details of the goods and services supplied, including relevant HSN/SAC codes
- Details of any additional place of business, if the proprietor operates from more than one location within the state
How to Apply for GST Registration for a Sole Proprietorship
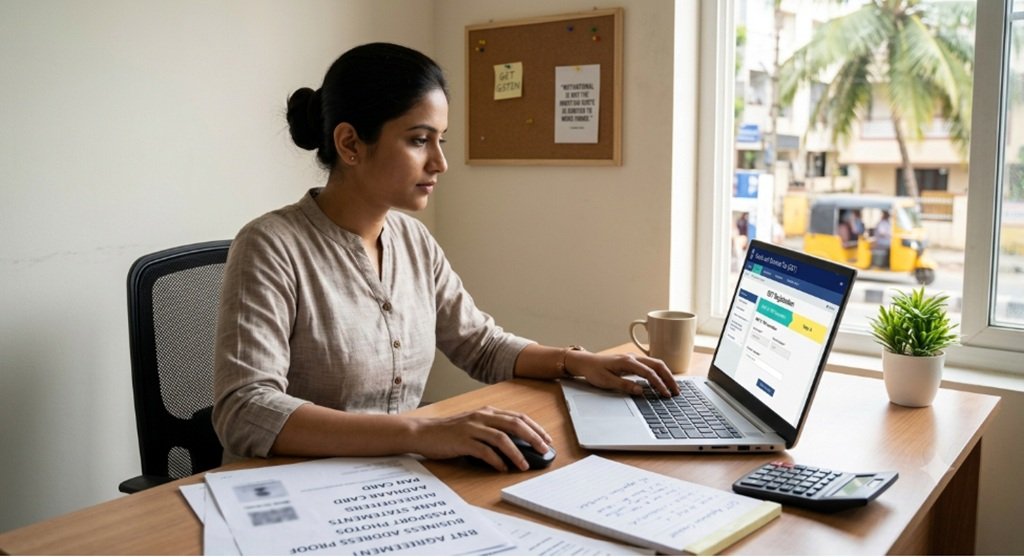
This is the core, practical part of the process. GST registration is completed entirely online through the GST portal, in two broad parts, Part A (basic details, resulting in a Temporary Reference Number) and Part B (the detailed application).
Step 1: Visit the GST Portal
The proprietor begins the registration application on the official GST portal, under the “New Registration” option, selecting “Taxpayer” as the type of registration being applied for.
Step 2: Enter Basic Details
This initial stage (Part A of the application) requires:
- Legal name of the proprietor, as per PAN
- PAN of the proprietor
- State in which registration is being sought
- Mobile number
- Email ID
Once these details are submitted, the portal sends separate OTPs to the registered mobile number and email ID for verification. On successful OTP verification, a Temporary Reference Number (TRN) is generated, which the applicant uses to log back in and complete the remainder of the application within the prescribed validity period.
Step 3: Complete Part B of the Application
Using the TRN, the applicant proceeds to Part B, which covers the detailed sections of the application, including:
- Business Details, trade name, constitution of business (proprietorship), date of commencement, reason for registration, etc.
- Proprietor/Promoter Details, personal, identity, and contact information of the proprietor
- Authorised Signatory, typically the proprietor themselves, unless a separate authorised signatory is appointed
- Principal Place of Business, address and nature of possession of the premises
- Additional Place of Business, details of any other business locations within the state, if applicable
- Goods and Services, HSN codes for goods and SAC codes for services supplied
- State-specific information, such as professional tax employee code or state excise license details, where relevant
- Aadhaar Authentication, opting in for Aadhaar-based authentication of the proprietor
- Verification, a final declaration confirming the accuracy of the information submitted
The GST portal confirms these as the standard application sections and workflows that every applicant, including sole proprietors, must complete.
Step 4: Upload Supporting Documents
Each section of the application requires supporting documents to be uploaded in the prescribed format and file size, PAN, Aadhaar, photograph, and address proof, among others. It’s important to ensure that all uploaded documents are clear, valid, and current, since illegible or outdated documents are among the most common reasons applications get delayed or flagged for clarification.
Step 5: Complete Aadhaar Authentication
Where the applicant opts for Aadhaar-based authentication, an OTP is sent to the mobile number linked with the proprietor’s Aadhaar, and authentication is completed by entering this OTP on the portal. The GST portal specifies that Aadhaar verification must be completed within the prescribed period after the application is submitted; if authentication is not completed within this window, the application may instead be routed for physical verification of the business premises, which can extend the overall processing time.
Step 6: Submit the Application
The completed application is submitted using an applicable authentication method, typically an Electronic Verification Code (EVC) sent via OTP, a DSC (Digital Signature Certificate) where mandatorily required (such as for certain categories of applicants), or e-Sign, depending on the applicant’s setup and the category of registration.
Step 7: Receive ARN and Track Application
On successful submission, the portal generates an Application Reference Number (ARN), which is sent to the applicant’s registered mobile number and email. The ARN can be used to track the status of the application on the GST portal at any time. If the tax officer reviewing the application requires additional information or clarification, a notice is issued through the portal, and the applicant must respond within the specified timeframe to avoid rejection of the application.
How Long Does GST Registration Take for a Sole Proprietorship?
GST registration timelines can vary depending on several factors, including:
- The time taken for application processing by the tax authorities
- Whether Aadhaar authentication is completed promptly and successfully
- Whether the application requires additional document verification
- Whether a clarification notice is issued, and how quickly the applicant responds to it
- Whether physical verification of the business premises becomes necessary, which adds further processing time
Because these factors vary from application to application, it isn’t accurate to promise a fixed approval timeline. Applicants who complete Aadhaar authentication promptly and submit clear, accurate documents at the outset generally experience smoother processing, while applications requiring clarification or physical verification can take noticeably longer.
What Happens After GST Registration?
Once the proprietor receives the GSTIN, several responsibilities follow:
- Download the GST registration certificate from the portal, which serves as official proof of registration
- Display the GSTIN at the principal place of business and on other locations, as required under GST rules
- Issue GST-compliant invoices for all applicable taxable supplies
- Charge GST on supplies where applicable, at the correct rate
- Maintain records of invoices, purchases, sales, and input tax credit as required under GST law
- File applicable GST returns within the prescribed due dates
- Claim eligible input tax credit on GST paid on business purchases and expenses, subject to conditions
- Monitor turnover and registration status on an ongoing basis, particularly if turnover fluctuates near relevant thresholds
- Update registration details whenever there is a change, such as a change in business address, addition of a new place of business, or change in authorised signatory
GST Compliance After Registration
Receiving the GSTIN is the starting point, not the end, of GST compliance. Ongoing obligations typically include:
- GST return filing, periodic filing of applicable returns based on the registration type and turnover
- Tax payment, timely payment of GST liability for each tax period
- Invoice compliance, issuing invoices that meet the format and content requirements prescribed under GST law
- Input tax credit reconciliation, regularly matching credit claimed with supplier filings to avoid mismatches or denial of credit
- Record maintenance, retaining invoices, books of account, and other records for the period prescribed under GST law
- Annual/periodic compliance, as applicable, such as annual returns or reconciliation statements, where applicable to the proprietor’s turnover
- Amendment of GST registration details when required, promptly updating the portal for changes in business details, address, or contact information
Common Mistakes to Avoid During GST Registration
- Using incorrect PAN or proprietor details, which can lead to mismatches and application rejection
- Providing an incorrect business address, particularly one not supported by valid proof
- Uploading unclear documents, such as blurred scans or outdated proofs
- Selecting incorrect business activities, which can misrepresent the nature of the business on record
- Entering incorrect HSN/SAC information, affecting invoicing and return filing accuracy later on
- Ignoring Aadhaar authentication requirements, which can trigger physical verification and delay approval
- Missing clarification notices issued by the tax officer, which can result in rejection if not responded to in time
- Assuming GST registration is automatically included with sole proprietorship registration online, the two are separate processes entirely
- Assuming GST registration ends once GSTIN is received, compliance obligations continue well beyond the registration stage
Why Choose Zolvit for Sole Proprietorship and GST Registration?
Getting GST registration right, and staying compliant afterward, is easier with the right support at each stage:
- Understand your registration requirements, get help determining whether your business needs GST registration, based on turnover, nature of supply, and applicable provisions.
- Complete registration support, assistance from documentation to application submission, covering every section of the GST portal process.
- Expert guidance, get support with GST-related registration requirements and business details, so nothing is missed or misfiled.
- End-to-end business support, manage sole proprietorship registration and other business compliances through one platform.
- Ongoing compliance assistance, support that goes beyond simply obtaining the GSTIN, covering returns, invoicing, and amendments as your business evolves.
Get Started with Zolvit
Conclusion
For sole proprietors who fulfill the turnover or supply threshold, location or mandatory registration requirement, GST registration is essential to comply with the law. The registration for sole proprietorship and GST are two distinct processes.
After the registration process, the proprietor will be responsible for managing their GST returns, invoicing, taxation and record keeping. Zolvit can help you in setting up a sole proprietorship and GST registration process.

