Blog Page 73

Direct vs Regular Plan: Which Mutual Fund Is Better?

Let’s be honest — investing in mutual funds can feel overwhelming at first. You finally decide to take the plunge, open a fund portal, and then bam! You’re staring at two options: a regular plan and a direct plan. Most people just pick one at random, or worse, let someone else pick for them without really understanding what they’re signing up for.

Here’s the thing, though — that one decision can quietly cost you lakhs of rupees over the years. No kidding.

This article is all about helping you understand the real difference between these two options, with a spotlight on Direct Funds — what they are, why they’re gaining so much traction among savvy investors, and whether they’re the right fit for you. We’ll walk through the nitty-gritty in plain English, no financial jargon pile-ups, and no beating around the bush.

So grab a cup of chai and let’s get into it.
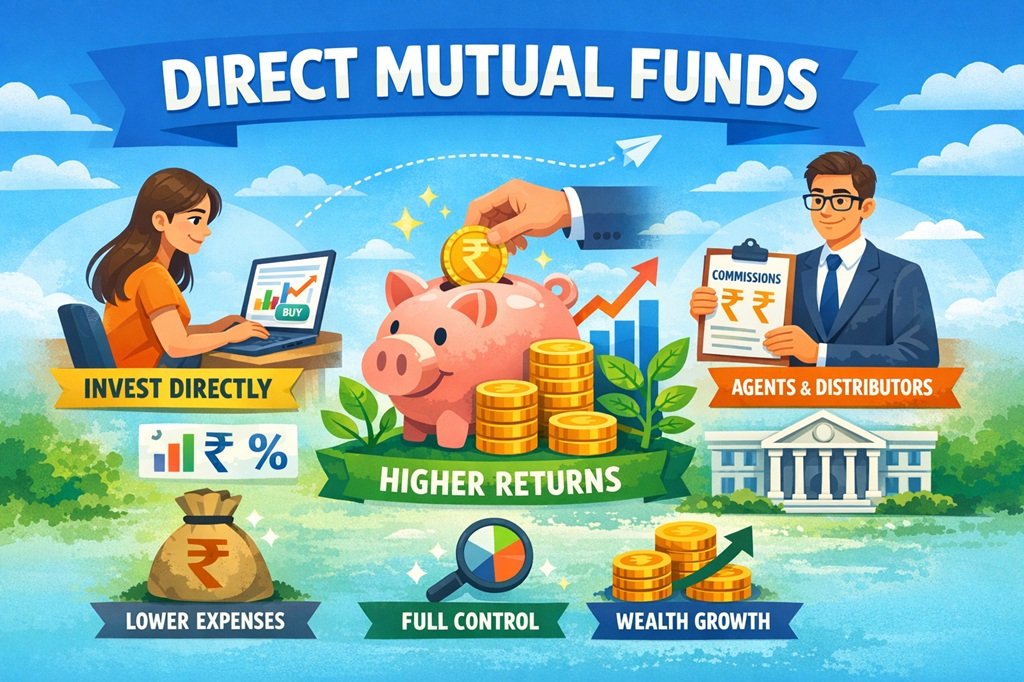
Direct Mutual Funds

What Are Mutual Fund Plans, Anyway?

Before we get into the differences, let’s quickly get on the same page about how mutual funds work.

When you invest in a mutual fund, you’re pooling your money with thousands of other investors. A fund manager then takes that pooled money and invests it across stocks, bonds, or other securities — depending on the fund’s objective. So far, so good.

Now, here’s where it gets interesting. The same mutual fund can be offered in two different “versions” or plans:

  1. Regular Plan — You invest through a broker, distributor, or financial advisor.
  2. Direct Plan (or Direct Funds) — You invest directly with the fund house, cutting out the middleman entirely.

That’s the core distinction. But trust me, the impact of this seemingly small difference is anything but small.

Understanding Direct Funds

Direct Funds are mutual fund plans where you invest straight with the Asset Management Company (AMC) — no distributor, no broker, no agent in between. They were introduced by SEBI (Securities and Exchange Board of India) in January 2013, and they’ve been growing in popularity ever since.

Since there’s no distributor involved, the fund house doesn’t have to pay any commission. And here’s the beautiful part — those savings get passed directly on to you in the form of a lower expense ratio.

The expense ratio is basically the annual fee charged by the fund to manage your money. Even a difference of 0.5% to 1.5% in expense ratio might sound trivial, but over a 15 to 20-year investment horizon? It compounds into a massive difference in your final corpus.

Think of it this way: in a regular plan, you’re inadvertently paying someone a fee every single year — even if they haven’t spoken to you or given you any advice in years. With Direct Funds, that fee simply doesn’t exist.

Regular Plan vs. Direct Funds

Alright, let’s put these two side by side and really dig into the differences.

1. Expense Ratio — The Biggest Difference

This is where it all starts. Every mutual fund charges an expense ratio — an annual fee expressed as a percentage of your investment.

  • Regular Plans have a higher expense ratio because they include the distributor’s commission (typically 0.5% to 1.5% extra).
  • Direct Funds have a lower expense ratio because there’s no commission baked in.

For example, if a regular plan charges 1.8% annually and the direct version of the same fund charges only 0.9%, you’re saving nearly 1% every year. On a ₹10 lakh investment over 20 years at 12% returns — that difference can translate to over ₹20–25 lakhs in your pocket. That’s not pocket change!

2. NAV — Direct Funds Always Have a Higher NAV

NAV stands for Net Asset Value — essentially the price per unit of the fund. Since Direct Funds have a lower expense ratio, their NAV grows faster than the regular plan of the exact same fund.

Yes, you read that right. It’s the same underlying portfolio, managed by the same fund manager, investing in the same stocks or bonds. But the direct version consistently delivers slightly better returns because less money is being eaten away by fees.

3. Returns Over Time

Over the short term, the difference in returns between regular and direct plans might look insignificant — maybe 0.5% to 1% per year. But don’t let that fool you! Compounding is a powerful force, and over 10, 15, or 20 years, that seemingly tiny difference snowballs into a substantial gap.

Here’s a rough illustration:

Investment Period Regular Plan Returns Direct Fund Returns Approximate Difference
5 Years ₹17.6 Lakhs ₹18.2 Lakhs ~₹0.6 Lakhs
10 Years ₹31.1 Lakhs ₹33.3 Lakhs ~₹2.2 Lakhs
20 Years ₹96.5 Lakhs ₹1.11 Crores ~₹14.5 Lakhs

(Assuming ₹10 lakh lump sum, 12% vs 12.8% annualised returns)

The numbers don’t lie, do they?

4. Who Can Invest?

  • Regular Plans: Anyone can invest — typically through a bank, broker, financial advisor, or distribution platform.
  • Direct Funds: Anyone can invest too, but you have to do it yourself — through the AMC’s website, their official app, or SEBI-registered direct platforms like MF Central, Coin by Zerodha, Groww (in direct mode), etc.

There’s no eligibility barrier for Direct Funds. You don’t have to be rich, experienced, or a finance wizard. You just have to be a little proactive.

5. Guidance and Advice

This is honestly the most legitimate reason someone might prefer a regular plan. When you invest through a distributor or advisor, you potentially get financial guidance — help with goal planning, portfolio rebalancing advice, tax-saving recommendations, and so on.

With Direct Funds, you’re flying solo. There’s no one holding your hand. You’ll need to do your own research or rely on free resources, robo-advisors, or fee-only financial planners (who charge a flat fee rather than a commission).

So the trade-off is clear: regular plans cost more but may come with guidance; Direct Funds cost less but require self-initiative.

The Hidden Cost of Regular Plans

Here’s something that most distributors won’t bring up in conversation: the commission they earn on regular plans creates an inherent conflict of interest.

A distributor or agent earns more when:

  • You invest in funds with higher commissions
  • You stay invested (trail commission keeps rolling in)
  • You switch funds frequently (in some cases, generating new commissions)

This doesn’t mean every agent is acting in bad faith — many genuinely care about their clients. But the incentive structure is set up in a way that doesn’t always align with your best interests.

Direct Funds, on the other hand, put you in the driver’s seat. There’s no salesperson nudging you toward a higher-commission product. You’re choosing based on performance, ratings, and your own financial goals.

Who Should Actually Go for Direct Funds?

Not everyone is ready to go the DIY route, and that’s completely okay. So here’s an honest breakdown:

You’ll probably love Direct Funds if you:

  • Are comfortable doing basic online research
  • Can spend a few hours a year reviewing your portfolio
  • Have a clear understanding of your risk appetite and financial goals
  • Don’t need hand-holding or constant reassurance
  • Want to maximise long-term returns

You might prefer a regular plan if you:

  • Are a complete beginner and feel genuinely lost
  • Have a trusted, fee-transparent advisor who adds real value
  • Don’t want to spend any time managing investments yourself
  • Are investing in complex categories like international funds or dynamic asset allocation

There’s no shame in admitting you need a little guidance. The key is making sure the guidance you’re paying for is actually worth what it costs.

How to Start Investing in Direct Funds

Okay, so you’re intrigued. How do you actually get started with Direct Funds? It’s simpler than you might think.

Step 1: Complete Your KYC Before anything else, you need to be KYC-compliant. This involves submitting your PAN card, Aadhaar, and a photo. Most platforms let you do this digitally in under 10 minutes.

Step 2: Choose Your Investment Platform You can invest directly through:

  • The AMC’s own website (like HDFC Mutual Fund, SBI MF, etc.)
  • MF Central — the official AMFI portal
  • SEBI-registered platforms like Coin (Zerodha), Groww (in direct mode), Paytm Money, ET Money (direct option)

Step 3: Select Your Fund Do a bit of research! Look at:

  • Fund category (equity, debt, hybrid)
  • Past performance (3-year, 5-year returns)
  • Fund manager’s track record
  • Expense ratio
  • Risk level

Step 4: Invest! You can start a SIP (Systematic Investment Plan) with as little as ₹500 per month, or make a lump sum investment. It’s that easy.

Common Myths About Direct Funds

Let’s address some of the misconceptions floating around, shall we?

Myth #1: “Direct Funds are only for experts.” Nope! Plenty of first-time investors use Direct Funds successfully. The platforms are user-friendly, and there’s tons of free content online to guide you.

Myth #2: “The returns difference is too small to matter.” Oh, it matters alright. As we showed earlier, even a 1% difference compounds dramatically over two decades. Ignoring it is like leaving money on the table.

Myth #3: “I’ll miss out on good funds if I go direct.” Every fund house offers a direct plan for all its schemes. There’s no “exclusive” fund that’s only available in regular mode. You have access to the exact same funds.

Myth #4: “Regular plans are safer.” The underlying investment is identical. The risk profile doesn’t change based on whether you’re in a regular or direct plan. It’s the same portfolio, same fund manager.

Tax Treatment

Great question! The tax treatment for Direct Funds and regular plans is exactly the same. Whether you’re looking at:

  • Short-Term Capital Gains (STCG) — for equity funds held less than 1 year: taxed at 20%
  • Long-Term Capital Gains (LTCG) — for equity funds held more than 1 year: gains above ₹1.25 lakh taxed at 12.5%
  • Debt Funds — taxed as per your income slab

No differential treatment here. Your tax liability doesn’t change based on which plan you choose. What does change is how much money survives after fees — and that’s where Direct Funds shine.

Over the last few years, there’s been a noticeable shift. More and more retail investors are waking up to the commission story and making the move to Direct Funds.

A few reasons behind this trend:

  • Rise of DIY investing apps: Platforms like Zerodha Coin and Groww have made it incredibly easy to invest directly without needing a distributor.
  • Financial literacy boom: Thanks to YouTube, personal finance blogs, and podcasts, millions of Indians now understand what an expense ratio is and why it matters.
  • Post-pandemic awareness: With time on their hands, many people went deep into personal finance during lockdowns and came out the other side as confident self-investors.
  • SEBI’s transparency push: Regulators have made it mandatory for funds to disclose total expense ratios prominently, making comparisons easier.

It’s safe to say Direct Funds are no longer a niche choice for finance enthusiasts — they’re going mainstream.

FAQs

Q1. Can I switch from a regular plan to a Direct Fund?

Yes, you can! But keep in mind that switching is treated as a redemption and fresh purchase for tax purposes, so any capital gains will be taxed. It’s worth doing the math before making the switch, especially if you have significant unrealised gains.

Q2. Are Direct Funds available for all types of mutual funds?

Absolutely. Every mutual fund scheme — equity, debt, hybrid, index funds, ELSS, everything — has a direct plan option. You’re not limited in terms of choice.

Q3. Is there a minimum investment amount for Direct Funds?

Nope! The minimum investment is the same as regular plans. Most SIPs start at ₹500/month, and some funds accept lump sums from as low as ₹1,000.

Q4. What if I want advice but still invest in Direct Funds?

You can! Look for a SEBI-registered Investment Adviser (RIA) who charges a flat fee for advice — not a commission. This way, you get professional guidance AND benefit from the lower costs of Direct Funds. Best of both worlds!

Q5. How do I know if I’m already invested in a direct or regular plan?

Check your account statement. If the fund name says “Direct” or “Direct-Growth,” you’re in a direct plan. If it just says “Growth” without the “Direct” prefix, you’re likely in a regular plan.

Q6. Do Direct Funds guarantee better returns?

They don’t guarantee anything — no fund does. But because of the lower expense ratio, the net returns (returns after fees) tend to be higher for direct plans, all else being equal. It’s a structural advantage, not a promise.

Q7. Is it safe to invest directly through an AMC’s website?

Yes, completely. AMCs are regulated by SEBI and RBI. Investing directly through their official portals is safe and secure.

Conclusion

Look, at the end of the day, investing is personal. There’s no one-size-fits-all answer here. But if you’re looking to squeeze every bit of return out of your hard-earned money and you’re willing to put in a little legwork, Direct Funds are genuinely tough to beat.

The math is undeniable. The lower expense ratio, the higher NAV growth, and the absence of commission-driven bias all stack up in your favour over time. We’re not talking about a minor edge — we’re talking about potentially lakhs of rupees more in your retirement corpus.

Is there a learning curve? Sure, a small one. But the tools available today — the apps, the calculators, the free content — make it more accessible than ever. You don’t need to be a financial genius to invest in Direct Funds. You just need the motivation to take that first step.

So next time you’re setting up a mutual fund investment, don’t just tap “invest” on whatever pops up first. Pause. Check whether you’re in a direct plan or a regular plan. Because that one decision, repeated across multiple investments and compounded over decades, could genuinely change your financial future.

Your money deserves that five seconds of attention. Don’t you think?

Disclaimer: This article is for educational purposes only and does not constitute financial advice. Please consult a SEBI-registered financial adviser before making investment decisions.
Different Types of E-commerce Business Models (2025)

Welcome to the bustling bazaar of the 21st century — the internet! It’s no exaggeration to say that e-commerce has become the new normal. In 2025, with drones dropping off packages, AI bots giving customer support, and cashless payments ruling the roost, knowing your way around the E-commerce Business Models isn’t just handy — it’s essential.

Gone are the days when only big fish could swim in these digital waters. Whether you’re a one-person army selling homemade candles or a tech startup looking to shake up the supply chain game, there’s a model that fits like a glove.

So, ready to decode the secret sauce behind online success? Let’s unravel the Different Types of E-commerce Business Models (2025) and how each can help you click, cart, and conquer the market.

E-commerce Business Models

Different Types of E-commerce Business Models

1. Business-to-Consumer (B2C): The Classic Click & Buy

What is B2C, and Why Is It So Popular?

Imagine ordering pizza from your favorite food delivery app or buying that funky phone case on Amazon — that’s B2C in action. It’s the most recognizable and user-friendly of all E-commerce Business Models.

Key Features of B2C:

  • Direct sales from businesses to individual customers
  • Typically involves a short buying cycle
  • Highly dependent on digital marketing and customer engagement

Why B2C Still Dominates in 2025

Despite the rise of niche models, B2C remains king of the hill. Here’s why:

  • Convenience is Queen: Shoppers crave ease and speed.
  • Brand Loyalty is Gold: Social media fuels engagement and repeat purchases.
  • Mobile-first Mindset: With more purchases happening on smartphones, B2C platforms have adapted beautifully.

Real-world Examples:

  • Flipkart
  • Myntra
  • Swiggy
  • Nykaa

Pro Tip: If you’re launching a product-based startup, this model might just be your golden ticket!

2. Business-to-Business (B2B): Big Players, Bigger Deals

Behind the Scenes of the B2B Boom

B2B is where the corporate chessboard comes alive. Think of manufacturers selling bulk goods to retailers or software vendors supplying tools to enterprises. It’s more strategic, less impulsive — but don’t let that fool you, it’s a behemoth in the world of E-commerce Business Models.

Key Features of B2B:

  • Longer sales cycles, but larger transaction volumes
  • Emphasis on relationships, contracts, and custom pricing
  • Integration with ERP and inventory systems

2025 Trends Driving B2B Growth

  • Digital Transformation: Companies want seamless procurement.
  • AI-powered Negotiations: Dynamic pricing is changing the game.
  • Global Trade Access: Platforms are enabling cross-border B2B transactions like never before.

Examples to Watch:

  • Alibaba
  • Udaan
  • IndiaMART
  • Salesforce Commerce Cloud

Heads-Up: If your target market includes businesses and not individuals, B2B might be your playing field.

3. Consumer-to-Consumer (C2C): Peer Power Unleashed

What Makes C2C Tick in 2025?

Have something lying around you don’t use anymore? Just post it online and sell it — boom, that’s C2C! It’s a model where regular folks sell directly to each other through a platform that acts as a digital marketplace.

C2C E-commerce Model Must-Haves:

  • Trust and user ratings
  • Dispute resolution systems
  • Secure payment gateways

What’s New with C2C in 2025?

  • Decentralized Platforms: Blockchain ensures transparency.
  • Eco-commerce: A surge in second-hand product sales is pushing green buying.
  • Hyperlocal Marketplaces: City-specific platforms for faster delivery and pickup.

Top Players:

  • OLX
  • eBay
  • Facebook Marketplace
  • Quikr

Hot Tip: Got a community or product that encourages sharing or reselling? This model could skyrocket your reach.

4. Consumer-to-Business (C2B): Turning the Tables

Wait, Consumers Selling to Businesses? Yep!

The C2B model flips the script. It’s when individuals offer products or services to companies — like photographers selling stock images, or influencers pitching sponsored content to brands.

Core Characteristics of C2B:

  • Value flows from consumer to business
  • Businesses pay for rights, leads, or services
  • Often tech-enabled and gig-economy powered

Why C2B is Gaining Ground in 2025

  • Freelance Boom: The gig economy isn’t just surviving — it’s thriving!
  • Creator Economy: Influencers, bloggers, and artists monetize their following.
  • Data Value Realization: Users now get paid for their feedback, surveys, or even data!

Platforms Supporting C2B:

  • Upwork
  • Fiverr
  • Shutterstock
  • Patreon

Quick Thought: If you’re building a platform or marketplace for freelancers or digital creators, C2B is your go-to model.

5. Direct-to-Consumer (D2C): Cutting the Middleman Clean

What’s the Big Deal About D2C?

In the D2C model, brands sell directly to the end customer, bypassing retailers and wholesalers. It’s like B2C — but sleeker, sharper, and super-brand-centric.

Unique D2C Traits:

  • Full control over brand narrative and customer experience
  • Often relies on social media, influencer marketing, and storytelling
  • Lower costs, higher margins

D2C in 2025: Personalization is Everything

  • AI-Powered Personalization: Tailored offers based on browsing behavior.
  • Subscription Commerce: Think monthly beard oils, gourmet snacks, or even undies!
  • Community Building: Customers aren’t just buyers — they’re brand evangelists.

Popular D2C Names:

  • Mamaearth
  • boAt
  • Lenskart
  • The Souled Store

Pro Tip: Got a unique product with a story? D2C gives you the spotlight without sharing the stage.

6. Dropshipping: Sell First, Source Later

How Dropshipping Works in 2025

With dropshipping, you don’t keep any inventory. You simply list a product on your site, and once it sells, a third party ships it directly to the customer. Minimal risk, minimal capital, and a low barrier to entry — sounds dreamy, right?

Why Dropshipping Still Rocks:

  • No warehouse worries
  • Easy to scale across geographies
  • Perfect for testing new product categories

The 2025 Dropshipping Scene: Smarter, Faster, Leaner

  • Automation Overdrive: From order processing to customer service, it’s all AI now.
  • Niche Niches: Micro-targeted products are the new cash cows.
  • Sourcing Transparency: Consumers want to know where their stuff comes from.

Top Dropshipping Platforms:

  • Shopify + Oberlo
  • GlowRoad
  • Spocket
  • Printful

Caution Ahead: While easy to start, it’s competitive. Pick your niche wisely, and add serious value!

Bonus: Emerging Hybrid Models Worth Noticing in 2025

The lines between business models are blurring. Some exciting hybrids include:

  • B2B2C: Brands supply products to businesses who then sell to customers (like cloud kitchens).
  • D2C + Subscription: Recurring revenue magic!
  • C2C + Blockchain: Secure peer-to-peer marketplaces with smart contracts.

In short, the e-commerce chessboard is ever-evolving.

FAQs: Everything You Wanted to Ask About E-commerce Business Models (2025)

1. What is the most profitable e-commerce business model in 2025?

While D2C and B2B are raking in big bucks, profitability really depends on execution, niche, and customer acquisition strategy. D2C is hot for new-age brands with storytelling edge.

2. Is dropshipping still a viable option in 2025?

Absolutely! But with rising competition, success now hinges on brand-building, marketing smarts, and choosing the right suppliers.

3. Can I mix different e-commerce business models?

Of course! Many businesses today blend B2B and B2C, or D2C with subscriptions. The key is maintaining clarity in your value proposition.

4. Which e-commerce model is best for beginners?

Dropshipping or D2C are great starting points due to lower upfront costs and direct consumer access.

5. How do I choose the right e-commerce model?

Ask yourself: Who is my target customer? What’s my product or service? What are my resources? The answers will guide your model selection.

6. Are hybrid e-commerce models sustainable?

If well-managed, hybrid models can unlock multiple revenue streams. But they do demand tighter operations and customer segmentation.

7. How is AI impacting e-commerce business models?

AI is revolutionizing personalization, logistics, customer service, and dynamic pricing — making every model smarter and more scalable.

8. Is C2C secure in 2025?

Thanks to escrow systems, blockchain, and user verification, C2C is safer than ever.

9. Do I need a website for all e-commerce models?

Not necessarily. Social commerce and app-based selling are booming. But having a website still helps build credibility.

10. Which is the fastest-growing model in India?

D2C and B2B2C are rapidly gaining traction, thanks to digital infrastructure, social media, and supply chain evolution.

Conclusion 

There you have it — a deep dive into the Different Types of E-commerce Business Models (2025). Whether you’re gunning for a B2C empire, testing waters with dropshipping, or rallying freelancers under a C2B umbrella, the opportunities are wide open.

The secret sauce? Know your audience. Understand your value. And stay nimble.

In this digital age, success isn’t just about selling stuff. It’s about crafting an experience, solving a problem, or sometimes, just putting a smile on someone’s face when they open that neatly packed box.

So, which e-commerce route are you taking this year? Whatever your pick, here’s to making 2025 your most profitable one yet. Let the shopping spree begin — from the backend, of course!

Ensuring MCA and GST Compliance: Why Virtual Offices Are the Smart Choice

0

In the hectic corporate environment of today, following regulatory organizations like the Goods and Services Tax (GST) Department and the Ministry of Corporate Affairs (MCA) is extremely imperative. For startups, MSMEs, even established companies, keeping compliance with MCA and GST requirements usually calls for a genuine registered office address in numerous Indian states.

Here is where the concept of a virtual office for GST registration starts to shine as a legally sound, tactically savvy, and financially practical solution.

GST Compliance

Acquiring the MCA and GST Compliance Manuals

Every registered firm per MCA has to maintain a registered office where all official records and correspondence are held. This location must be current and immediately accessible for government body correspondence, statutory inspections, and document submission. Companies under the GST system have to concurrently show a main place of business (PPOB) in many states coupled with any pertinent additional places of business (APOB) or virtual places of business (VPOB). These sites are really essential for GST registration, compliance documentation, and audit requirements. Company operations could be substantially hampered by fines, delayed approvals, or even registration cancellation for MCA or GST restrictions.

 Why would one want to register for GST via a virtual office?

A virtual office for GST registration allows businesses a firm address in well-known commercial areas without using real premises. Legal use of this address might be for business connections, MCA letters, and GST registration. Even if the business operates from many sites or remotely, a virtual office provides a physical address coupled with required services including mail handling, authorized representative support, and compliance facilitation unlike a traditional office.

For what reason does MCA and GST compliance most benefit virtual offices?

  1. Regulatory approval and legal validation: As long as virtual offices follow prescribed documents and apply policies, MCA and GST officials have generally accepted them. A recognized virtual office address could be used as a PPOB, APOB, or the reverse under GST; under MCA guidelines, it would be used as a registered office. This enables businesses to satisfy legal requirements without incurring costs connected to leasing or owning real estate throughout numerous states.
  1. Monetary value Particularly for small businesses or startups, leasing or purchasing prime location commercial property can be expensive. Virtual offices simplify rent rates, maintenance costs, and employment expenses. By registering for GST using a virtual office, businesses might acquire premium addresses for a fraction of the cost, therefore greatly reducing running costs and capital expenses.
  1. Flexibility and expansion Virtual offices offer a lot of freedom. Companies could set many virtual addresses under several jurisdictions to follow MCA laws or multi-state GST registration criteria. This scalability allows organizations to expand geographically free from physical infrastructure limitations, therefore enabling faster market access and simpler compliance management.
  1. Enhanced self-awareness The company presents professionalism and credibility by using a virtual office with a reputable business address. This is what helps one build confidence with government authorities, suppliers, and customers. A virtual office address ensures that all official mail is received at a consistent location, therefore facilitating speedier regulatory filings and improved interactions.
  2. Simplified Management of Compliance Leading virtual offices offer value-added services including signed boards, approved agents, and assistance with documents required by MCA and GST authorities. These services guarantee that the virtual office address maintains compliant with legal criteria, therefore lowering the probability of rejection during registration or validation processes.
  1. Operational efficiency and simplicity A virtual office serves to save the need for actual presence at the registered address by let businesses run electronically. Compliance guarantees the support of modern hybrid or work-from-home models. Timeliness of official mail delivery and government office receipt also helps to streamline correspondence and reduce regulatory issue delays. Important Legal Issues Affecting Virtual Office Selection for GST Registration Although virtual offices offer several advantages, businesses must make sure the chosen service meets particular legal requirements to avoid compliance issues:
  • Exact records The virtual office has to transmit notarized rental agreements, updated proof of ownership or lease, and the necessary NOCs—no object certificates—from the property owner. Respectable virtual office providers are required by GST authorities to display the company name and GSTIN on a signs board at the registered address.
  • Authorized Representative: Should required, an authorized person could be contacted to conduct official contacts and schedule visits compliant with MCA and GST policies.
  • Address Verification and Geotagged Images: Some state GST inspectors want geotagged images of the property for proofreading. The virtual office system should allow these as recommended by the government.
  • No Subletting or Unauthorized Use: Local zoning and municipal guidelines should guide the virtual office site; the provider should not sublet the premises in a way that violates the law. Last but not least, businesses striving to fairly follow MCA and GST guidelines would be sensible and legally sound to choose a virtual office for GST registration.

It offers the perfect balance between cost control, operational freedom, and regulatory compliance. Companies can boldly use virtual offices to meet legal needs since regulatory authorities approve them, therefore alleviating their worries on the weight of actual office buildings. With this innovative approach, startups, MSMEs, and established companies may now preserve perfect compliance and effortlessly grow. Whether your company wishes to boost its presence all throughout India or simplify MCA and GST compliance, your first attention should be on looking at virtual office solutions.

e-Passport in India – Benefits, How to Apply & Why It’s a Game-Changer!

Imagine zipping through airport immigration without fumbling for papers, no longer having to deal with worn-out passports or long queues. Sounds like something out of a sci-fi flick, right? Well, hold on to your boarding passes—India’s e-passport is here to make that dream a reality!

Launched with a bang, the e-passport in India is a high-tech leap in the way we identify ourselves across borders. It’s smart, secure, and incredibly slick. But let’s be honest—new tech can sometimes be a bit overwhelming. What is an e-passport? How is it different from the one buried in your drawer? And more importantly—how do you get one?

In this in-depth guide, we’ll unpack everything about the e-passport in India—benefits, how to apply, eligibility criteria, safety features, and even how it stacks up globally. Buckle up; this one’s gonna fly high!

e-passport in India

What’s an e-Passport Anyway?

Let’s start with the basics—because no one wants to sound clueless at the check-in counter.

An e-passport (also known as a biometric passport) is a traditional passport upgraded with an embedded electronic microprocessor chip. This chip securely stores your biometric data, personal info, and a digital signature. In short, it’s your passport, but smarter, faster, and far harder to forge.

🇮🇳 The Indian Take:

India officially rolled out e-passports for public use in 2022, starting with diplomats and government officials. Now, it’s expanding to regular citizens. With a chip embedded in the back cover and printed using laser-engraved personalization, this passport is built like a tech fortress.

Top Benefits of e-Passport in India

So, what’s the big deal? Why are folks lining up (digitally, of course) for these shiny new travel documents? Let’s break it down.

1. Next-Level Security

Gone are the days when passports could be easily tampered with or duplicated. e-Passports come with robust encryption and digital verification that make counterfeiting nearly impossible.

  • Anti-skimming technology
  • Public key infrastructure (PKI) verification
  • Tamper-proof data encoding

2. Faster Immigration Checks

Ever watched someone breeze through immigration while you’re still fishing out your pen to fill forms? That could be you—with an e-passport.

  • Automated e-gates at international airports
  • Quicker identity verification using biometrics
  • No more repetitive manual entries

3. Global Compatibility

More than 120 countries already support e-passports. So, if you’re planning to travel to Europe, the US, or the Middle East, you’re gonna love the seamless scanning.

4. Efficient Government Processing

From issuing visas to tracking immigration data, e-passports help the government streamline operations. That means quicker services for you, less paperwork, and fewer headaches.

5. Eco-Friendly Upgrade

Fewer pages, better materials, and laser printing mean your passport’s greener than ever. Mother Earth approves!

Who Can Apply for an e-Passport in India?

You’re probably wondering, “Can I get one of these fancy passports?” The good news? You probably can.

Eligibility Checklist

  • Indian citizen (obviously!)
  • Must be applying for a new passport or passport renewal
  • All age groups are eligible, including minors and senior citizens
  • Must have complete KYC documents (Aadhaar, PAN, etc.)

How to Apply for an e-Passport in India: A Step-by-Step Guide

Okay, now let’s get to the part you came here for—how to apply. Spoiler: It’s not rocket science!

Step 1: Register on Passport Seva Portal

Visit passportindia.gov.in and register yourself on the official Passport Seva Portal.

  • Fill out the application form online
  • Choose “Reissue” if you already hold a passport and want to upgrade
  • Select the nearest Passport Seva Kendra (PSK) or Post Office Passport Seva Kendra (POPSK)

Step 2: Pay the Fee Online

Once the form’s in, you’ll be redirected to the payment page.

  • Regular Passport (36 pages): ₹1,500 approx.
  • Jumbo Passport (60 pages): ₹2,000 approx.
  • Tatkal Services: Extra ₹2,000

Payment can be made via debit/credit card, net banking, or UPI.

Step 3: Book Your Appointment

Pick a date and time slot at the nearest PSK or POPSK. Don’t forget to note the ARN (Application Reference Number).

Step 4: Visit the PSK/POPSK

On the appointment day:

  • Carry your appointment receipt
  • Bring original documents + self-attested copies
  • Complete biometric and document verification
  • Officers will capture your photo and fingerprints on-site

Step 5: Wait for Delivery

Once everything’s verified and cleared, your brand-new e-passport will be printed and delivered straight to your doorstep. Usually takes 7–10 working days (longer in rare cases).

What’s Inside That Chip? Tech Specs of the Indian e-Passport

Let’s geek out for a moment. What exactly does that chip carry, and how secure is it?

Data Stored in the Chip:

  • Holder’s name
  • Date of birth
  • Gender
  • Passport number
  • Nationality
  • Biometrics (photograph, fingerprints)
  • Digital signature of issuing authority

Safety Features:

  • RF Shield: Prevents unauthorized scanning
  • Public Key Infrastructure (PKI): Validates digital signature and data integrity
  • ICAO Compliant: Fully compatible with global border systems

e-Passport vs Traditional Passport: What’s the Difference?

Let’s face it—passports aren’t something we upgrade often, so it’s fair to ask: how is the new kid on the block different?

Feature Traditional Passport e-Passport in India
Chip Embedded ❌ No ✅ Yes
Biometric Data ❌ Manually Verified ✅ Stored & Auto-Verified
Global Compatibility ✅ Partial ✅ Widespread
Counterfeit Protection ❌ Low ✅ Very High
Processing Time ⏳ Manual ⚡ Faster with automation
Eco-Friendliness ❌ Standard Materials ✅ Laser & Low-impact Tech

Where Can You Use e-Passports?

Still wondering if it’s worth the upgrade? Here’s where e-passports make a difference:

Travel To:

  • USA, UK, Canada
  • Schengen countries
  • UAE, Singapore, Japan, Australia

Use at:

  • e-Gates for automated entry/exit
  • Visa application centers for fast-tracked scanning
  • Hotel check-ins in international destinations

Things to Remember

Every rose has its thorn, right? While the e-passport is super cool, here are a few things to keep in mind:

You Can’t Upgrade Mid-Term

Already have a passport valid till 2030? You’ll need to wait for expiry or request an early reissue.

Chip Isn’t Readable Everywhere (Yet)

Some immigration desks still use manual systems, so don’t ditch your printed visa pages just yet.

Take Good Care of That Chip

Keep your passport away from water, magnetic surfaces, and strong pressure—chips can get damaged too!

FAQs

Q1. Is it mandatory to get an e-passport in India now?

Nope. It’s optional for now. But new issuances and reissues will gradually transition to e-passports.

Q2. What happens if my chip gets damaged?

You’ll need to apply for a reissue just like with a lost or damaged traditional passport.

Q3. Can kids and elderly citizens get e-passports too?

Yes! There are no age restrictions. Just apply like you would for any other passport.

Q4. Is the e-passport more expensive?

Not really. Pricing is in line with traditional passports, except for any Tatkal services.

Q5. Can I use my e-passport for Aadhaar or other ID verification?

Yes, it’s a valid identity proof across most services—just like the traditional one.

Q6. How can I tell if I’ve received an e-passport?

Look for a small chip icon on the front cover, and you’re good to go!

Conclusion 

From fingerprint-scanning border gates to enhanced global acceptance, e-passports in India are a giant leap into the future of hassle-free travel. No more sweating over last-minute visa stamps or worrying about misplaced documents. With tighter security, smoother processing, and faster travel experiences, it’s high time you upgraded that old booklet.

So, if you’re applying for a passport anytime soon, go ahead—opt for the e-passport. It’s not just a travel document; it’s your digital key to the world.

Ready to board the future? Your e-passport awaits.