Blog Page 367

Rakesh Jhunjhunwala’s Tips for Stock market

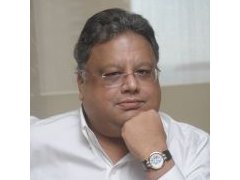
Rakesh Jhunjhunwala

Big bull Rakesh Jhunjhunwala is called as king of Indian stock market. Rakesh Jhunjhunwala has started n stock market with investment capital of just 5000 Rs/- and right now his net worth is more than 5000 Cr. Rakesh Jhunjhunwala has proved that if you adopt correct strategy and select right stock you can win the market and earn good returns.

Many individuals today follow rakesh jhunjhunwala and always eager to know about investment secrets & stock selection criterion of Rakesh Jhunjhunwal. We are herewith 11 tips of Rakesh Jhunjhunwala for stock market.

Rakesh Jhunjhunwala‘s Tip No. 1: Don’t Look For Multi-baggers

Rakesh Jhunjhunwala‘s first investment mantra on how to find multibaggers stock is surprisingly different from what you would expect. Rakesh Jhunjhunwala says: “Don’t look for multibaggers. Don’t seek them at all. Let the multibaggers come to you!”

Rakesh Jhunjhunwala says: Don’t go out into the investment world saying “I only want to invest in potential multibaggers”. Instead of that “Go back to the old-fashioned way of making investments try to do enough homework and select fundamentally sound companies with good growth prospects, your investments will by themselves become multibaggers after some time”.

Rakesh Jhunjhunwala‘s Tip No. 2: Forget ‘Large Cap, Small Cap’ – Look For Value

We always hear debate from analyst whether large cap, mid cap or small cap stocks are better.

Rakesh Jhunjhunwala says “Forget all that and Look for Value, If there is value in Large Cap, buy it. If there is value in Small Cap, buy it. But don’t obsess on irrelevant matters”

But Rakesh Jhunjhunwala makes his preference quite clear. He says that given a choice and all things remaining equal, a mid-cap or a small-cap is a preferred bet because the valuations will be low and they can scale it up quite quickly.

‘Rakesh Jhunjhunwala‘s Tip No. 3: Don’t Look for Profits; Look For Sources Of Profits

Rakesh Jhunjhunwala cautions that most investors obsess about the current sales and profits. They look at each quarter and focus obsessively on short-term profits. “That’s missing the wood for the trees” says Rakesh Jhunjhunwala.

Instead Rakesh Jhunjhunwala says “Look at the sources of Profits. What are the reasons/factors that will give rise to Profits in the medium and long-term term”.

Rakesh Jhunjhunwala gives classic example: That of Praj Industries, a company engaged in manufacture of bio-ethanol fuel. When Praj Industries started out, nobody realized the massive demand that would arise for alternate fuels like ethanol. An investor could have foreseen that would have had his multibagger.

Rakesh Jhunjhunwala‘s Tip No. 4: Give it Time, Be Patient:

Rakesh Jhunjhunwala repeats what investment guru Warren Buffet have been advising over the past several decades. Warren Buffet was plain in his advice “Our favourite holding period is Forever”. Rakesh Jhunjhunwala gives the same advice: “Give your investments time to mature. Be Patient for the World to discover your gems”. Rakesh Jhunjhunwala cites the examples of Crisil, Titan and Pantaloon Retail which he has held on for several years now and has absolutely no intention of divesting them any time soon.

When Rakesh Jhunjhunwala bought Lupin it was just another mid-cap pharma company starting out into the world of generic drugs. What Rakesh Jhunjhunwala saw was a good efficient management which knew its job, a debt-free status, a good product line up and a growing market. That’s all. Rakesh Jhunjhunwala bought and played the waiting game. When the market matured, Rakesh Jhunjhunwala raked in his billions.

Rakesh Jhunjhunwala‘s Tip No. 5: Don’t get carried away by short-term aberrations:

Rakesh Jhunjhunwala cannot stop criticizing investors who are obsessed with short-term trends. Rakesh Jhunjhunwala emphasizes that he does not worry about quarterly results. If the results are bad in one quarter, he does not get disturbed. What Rakesh Jhunjhunwala is looking for is: Is there a trend? Are the quarterly results showing a trend and suggesting something or are they a mere aberration?

Rakesh Jhunjhunwala also cautions that one should not get carried away by short-term trends. He cites the oft-repeated example of 1999 when investors bought truck loads of Himachal Futuristic, Global Tele, Pentasoft while he used to buy Shipping Corporation and Bharat Electronics because he saw long-term value in them. The Oracle of Mumbai says “Never get carried away by aberrations, recognize and respect them but do remember that the market corrects its aberration though it takes time.”

Rakesh Jhunjhunwala‘s Tip No. 6: Invest in a business that you can understand:

If you look at it hard enough, you will realize that Rakesh Jhunjhunwala‘s reluctance to buy Himachal Futuristic, Global Tele and Pentasoft even in their heydays and his preference to stick to Shipping Corporation, Bharat Electronics and the other tried and tested names reveals another great investment tip from the Prince of Dalal Street: Buy what you know. Do you understand the business enough to be able to know what will happen 10 or 20 years from today. With Shipping Corporation, you can because shipping of goods will continue to happen for our foreseeable future. But you can’t tell that with technology companies which may have a great product today but which may become obsolete in 5 years.

Rakesh Jhunjhunwala‘s Tip No. 7: Don’t worry about the macro stuff like fiscal deficit, inflation etc which are unknowable. Focus on what is knowable:

Another immensely practical tip from Rakesh Jhunjhunwala, India’s greatest investor, for us folk who keep obsessing about currency fluctuation rates, inflation, fiscal deficit, political turmoil is: “Don’t worry about things that you neither know about nor can do anything about. It’s not important. Instead focus your energies on what you can and should know well enough – the business of the company you are investing in“.

Rakesh Jhunjhunwala‘s Tip No. 8 : Don’t Try To Time The Market:

Rakesh Jhunjhunwala endorses the validity of investment advice that has been propounded time and again by the wizards of investment time and again. Never try to time the market because you can never find the bottom of the market. Instead if you are getting the stock cheap in terms of its intrinsic value and future prospects, buy it.

Rakesh Jhunjhunwala simply resonances words of the Oracle of Omaha when he says that you must get right is the business. If you get that right, everything else falls into place.

Rakesh Jhunjhunwala‘s Tip No. 9 : If it’s cheap, buy it- Don’t pass up something cheap today in the hope that it will get cheaper tomorrow:

Rakesh Jhunjhunwala says: If you see the opportunity today, GRAB IT! Many wonderful opportunities are lost to postponement and then you rue your missed opportunities. Rakesh Jhunjhunwala says that it is not only important to identify the opportunity but then to be decisive and to act on it. Rakesh Jhunjhunwala cautions against getting stuck in a trap where you are perpetually seeking extra information to validate your idea.

In this, Rakesh Jhunjhunwala echoes the wisdom of Warren Buffet, the Oracle of Obama, who in the depths of the great stock-market depression of 2008 inspired investors by his clarion call “If you wait for robins, summer will be gone”.

Rakesh Jhunjhunwala‘s Tip No. 10: Don’t buy stocks that have a fixed return:

Rakesh Jhunjhunwala‘s next tip seems to be a no-brainer but it is surprising how many investors overlook it. What is the point of buying shares in a company such as an electricity company where the return on investment cannot by law exceed a certain amount, asks Rakesh Jhunjhunwala. But, Rakesh Jhunjhunwala, emphasizes that this logic does not mean that electricity and utility companies should not form part of your portfolio because they offer an excellent defense mechanism to the vagaries of the stock market with the undemanding demand for their product and their predictable cash flows.

Rakesh Jhunjhunwala‘s Tip No. 11: Ride your winners!!

The one question on everybody’s mind is “When do I sell my multibagger?” Rakesh Jhunjhunwala answers with aplomb “Never”.

One must be careful to understand what Rakesh Jhunjhunwala is saying here. What the Greatest Investor in India is saying is: “Don’t sell for the sake of selling because you can never say that the 10-bagger today will not become a 20-bagger tomorrow”.

But, Rakesh Jhunjhunwala hastens to clarify that this does not mean that one will never sell a multibagger. He gives two situations when even he may sell his beloved multibagger. The first is when he is short of funds and he needs capital to invest in a stock that will give even better returns than what the existing one will give. And second, when the stock market has become so irrational that the perception of earnings and the P/E is unsustainable. Rakesh Jhunjhunwala gives the example of what happend in 2000 when euphoric investors laid bets that Infosys’ earnings would double every year for the next 10 years. Infosys’ P/E at the then current earnings was 100-150 times. So, says Rakesh Jhunjhunwala, when the expectation of earnings peaks and the P/E is unsustainable, that is the time to sell.

India’s 10 most competitive companies for long-lasting results

top 10 compaines

Nomura has identified top 10 listed Indian companies with strong competitive strength that can deliver long-lasting returns.

These companies have been shortlisted by carrying out detailed analysis of the sources of competitive strength across sectors and in-depth look at management capabilities.

The brokerage has also minimised subjective and personal bias by combining quantitative and historical analysis to rank firms based on competitive strength.

Following are the companies that have been identified as the most competitive companies:

1) Amara Raja Batteries 

Action: Strong technology partner, growing brand awareness and cost advantage will remain key sources of competitive advantage.

Technological innovation, superior product quality, strong brand building efforts, and expansion of distribution networks and relationships with OEMs have helped AMRJ to gain significant market share across all segments. We expect the company to continue to deliver consistent earnings growth over the next five years as industry conditions remain favourable and AMRJ delivers on its strong execution capabilities.

The stock has re-rated significantly over the past two years on strong earnings and market share gains delivered across all segments. Current valuation (on 1-yr fwd P/E) is at a 13 per cent discount to EXIDE. We believe as Amara Raja increases its scale of operations and continues to deliver strong and consistent earnings growth, it should trade in line with EXIDE.

2) Cummins India

Action: Solid long-term fundamentals story

Cummins India has delivered a solid PAT CAGR of 22 per cent and 20 per cent over the past 10 and five years, respectively. We believe KKC remains a fundamentally strong business with a solid long-term opportunity in power-short India. With strong competitive advantages such as technology leadership in MHP and HHP engines, localized manufacturing, a wide service network and strong management, KKC looks poised to grow at a steady rate in the long term.

The stock is trading at ~16x one-year forward P/E and we believe captures most of the downside it currently faces from cyclical headwinds. We see limited downside from the current level, but given that our target price of Rs 496 (18x FY15F EPS of INR27.6) offers only limited potential upside, we remain neutral on the stock.

3) ITC 

Action: One of the top five companies to own in India – simply put.

Since the turn of the decade, ITC has delivered 32 per cent -plus CAGR vs. the Sensex 21 per cent-plus and HUVR 15 per cent-plus.

The significant alpha generated by the stock amply demonstrates, in our view, the company’s ability to deliver consistent returns for shareholders despite various changes to tax laws over the past decade or so.

ITC’s one-year forward P/E was 10x in FY03, which is currently at 24.6x FY15F (EPS: INR13.57). This, in our view, clearly reflects confidence of the market in the company over the past decade. We believe multiples are likely to hold at these levels, with earnings growth being the key driver of stock price performance.

4) Nestle India 

Action: Short term growth challenges should not cloud long term attractiveness.

Under-penetrated market categories, market leadership across segments, established brands, strong distribution and a global parent with a large portfolio of brands are all factors which we believe will remain the key drivers for Nestle in the long term. Nestle’s performance over the last few quarters has been underwhelming, but that should not concern long-term investors too much, in our view.

Over the last decade, Nestle has been an expensive stock, but the reason for that is the potentially attractive long-term opportunity it presents in the packaged food sector. For this, we believe Nestle’s valuation multiples should hold at high levels even within the consumer sector. However, we think high multiples are justified for a business with a high RoE and strong growth over the medium term. Our TP is under review.

5) Asian Paints 

Action: Brands, execution, distribution network should continue to be key growth drivers and sources of competitive advantage.

Asian Paints over the last decade has not only been able to maintain its strong momentum, but has also meaningfully expanded market share vs both domestic and international players. The company’s efforts in brand building and excellence in execution has meant that APNT’s profits have increased at 23 per cent CAGR over FY03-13.

We see expensive valuations as continuing to sustain despite the fact that APNT does go through cycles and is impacted significantly by macro conditions. Valuations are likely to continue to remain high as, over the longer term, the company has delivered consistent shareholders returns higher than market average. We are reviewing our target price.

6) Pidilite Industries 

Pidilite is a market leader in a range of categories within the consumer & bazaar segment (C&B) that includes adhesives, sealants, construction chemicals and art materials. We believe its strong brand, solid distribution network, and ability to launch innovative products in niche categories will help the company to sustain its competitive advantage.

The company has a strong balance sheet, with net cash and average FCF generation of INR2.3bn over FY09-12. Low capex and a longer product cycle have resulted in high ROCE, which has exceeded 20 per cent over the last 10 years ex FY09 and looks sustainable going forward.

We maintain our neutral rating and are reviewing our target price.

7) Sun Pharmaceuticals

A strong domestic business and balance sheet that allow the company to pursue value-accretive inorganic opportunities are the key sources of competitive strength, in our view. In the India formulation space, Sun Pharma has consistently grown ahead of the broader market. The company has an unparalleled presence in chronic segments, in our view.

We use the SOTP approach to value Sun. The parts we value are: a) specific product upsides at 8x FY15F; b) cash as at FY14F; c) Protonix liability; d) Taro at 10x FY15F, and; e) base business at 22.5x FY15F. Our Target Price is Rs 842/share. We maintain our buy rating and are reviewing our target price.

8) Lupin 

The company has a successful track record of execution. In India, there is a complete transformation for the company from an anti-TB and anti-infective player to a prominent chronic therapy player. In the US, Lupin has emerged as the largest Indian generic company in terms of volume with higher per product sales.

Lupin trades at 22.6x FY14F and 18.2x FY15F our EPS of Rs 33.5 and Rs 41.5, respectively. We expect Lupin to trade at a premium to the peer group average given our expectation of sustained growth and the possibility of consensus earnings estimate hike. We maintain our buy rating and are reviewing our target price.

9) HDFC Bank 

For HDFC Bank, we dissect the sources of competitive advantage which has helped it deliver 30% plus y-y PAT growth over the past 55 quarters, driving a significant valuation premium over its peers. Brand strength and reach, product diversification and management quality are the overarching sources of its edge, but we dig deeper into their impact on profitability.

At our target price, HDFC Bank trades at 4x FY14F ABV of INR175.5 and 21x FY14F EPS of Rs 34.3 for FY14F ROA of 1.8 per cent and ROE of 21 per cent.

10) Axis Bank 

While HDFC Bank’s strengths are well received, Axis’ evolution as a fiercely competitive bank across asset and liability franchise has largely been overshadowed by its large corporate exposure. We list parameters on which we believe Axis has built a sustainable competitive edge.

Despite the risk perceptions, Axis’ delinquency ratio has been the lowest barring HDFC Bank’s. Proactive provisioning policy has ensured a similar rank in NNPL ratios. Axis’ portfolio is well diversified, with below 5 per cent funded exposure to the power sector. With its sustainable edge over quite a few components of profitability (RoA), we think Axis offers a compelling story given its steep discount to HDFC Bank.

Download New 15G -15 H Forms

15g

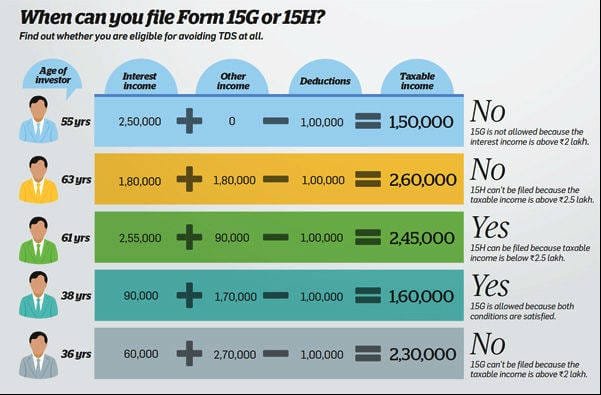
The New Form No. 15G and 15H is applicable to all Tax payees who do not want TDS Deduction on their Income from Fix deposits of Bank/company, postal fix deposit, Senior citizen Saving Scheme.

When can you submit form 15G/15H?

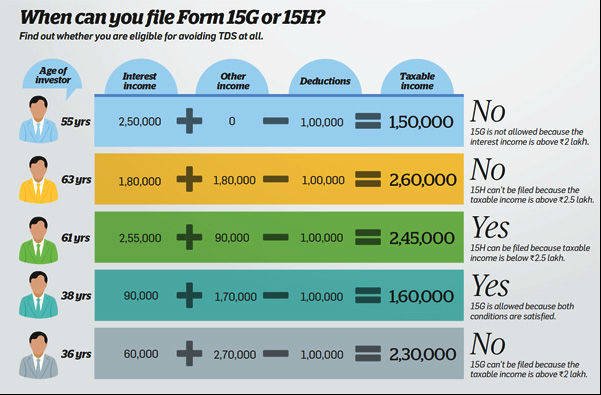
  • Depositor whose tax liability is NIL can only submit the 15G/15H form.
  • Depositor having interest income above basic income tax slab will not be able to submit the 15G/15H form. Suppose if any depositor has interest income of 4 lakh which is above basic slab cannot submit 15G/15H form.
  • Submit 15H form if depositors age is above 60 years.

Also Read – File Form 15G and Form 15H Online and Save TDS

  • One can submit form 15G/15H if interest income from particular branch of bank is above Rs.10,000/- and for company deposits its above Rs.5000/-

Submit

Download New 15G/15H forms:

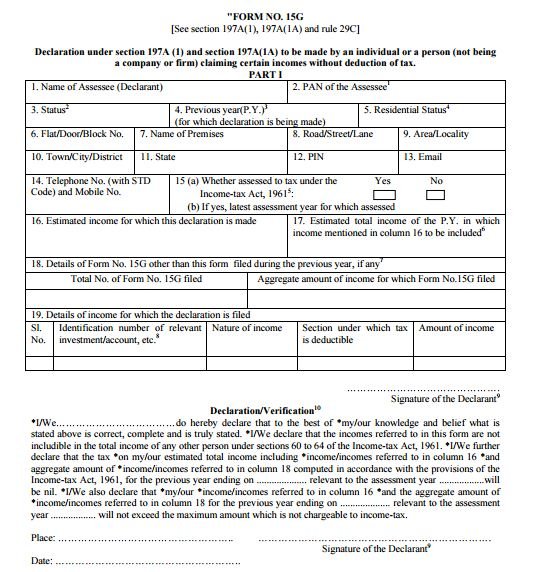
New 15G/15H forms are applicable from AY 2013-14 & old forms won’t work anymore. In the new form Income Tax department has ask for additional information like e-mail ID, Mobile Number, Profession, AO Code/Ward/Circle.

Another major change in these forms, compared to the earlier versions, is the addition of a column to mention the total estimated income from all sources, including the income for which exemption from TDS is requested.

Remember in order to avoid TDS you should submit Form No. 15G or 15H  at the beginning of the year. In case you are late and bank has already deducted tax  you have no other option but to file your income tax return and claim the amount of TDS a refund.

This form submission is valid only for 1 year and you need to submit this form again at starting of every financial year.

Please ensure to mention and submit your PAN card detail to the bank while submitting form 15 G or 15 H. In case you fail to submit PAN card detail bank will deduct TDS @20%.

Don’t forget to take acknowledgement of this form submission from the bank.

Also Read – 15 High Value Transactions tracked by Income Tax

If your tax liability is NIL please submit form 15G/15H to avoid TDS.

Click on following image to download form 15G/15H

Download new form 15G 15H

Download Form 15G  pdf form

Download Form 15H pdf form

Tips to prevent credit card frauds

Credit card Fraud

Credit card and Debit card is good alternative to physical money. Most of the people use credit card & debit card to make payments. But this plastic card has to be used with care else you may end up lending in to fraud. According to a Times of India report today, a global gang has skimmed Rs 30 crore off Indian credit card users in just two months.

As per the report, numerous credit cards have been cloned by using skimmers and the card details have been used to make international online transactions. Cloning may happen when cardholders travel to some global destinations that are notorious for cloning. Not only that sometime cloning may happen with cards where the holder has neither travelled abroad nor used it for online transactions.

As per report all top credit card issuers — ICICI Bank, HDFC Bank, Citibank, SBI Cards and Axis Bank — have been affected by these frauds.

So how you can prevent various types of frauds? Here are quick answers.

First thing you must understand that there are two types of transaction you do with your credit card. One is online on internet for making online purchase and other is offline where card is required during transaction like shopping in mall or payment of restraint bill etc.

So your card is exposed to two types of risk cloning during online transaction or during offline transaction.

Online Transaction:-

Check out following tips to prevent online fraud using credit card.

  1. While doing online transaction with credit card look for website with https as starting web address and not http. Here“s” stands for “secured”. Http website passes information to server in plain text while Https transmit information in encrypted format so information cannot be accessed by any party/hacker other than the client and end server.
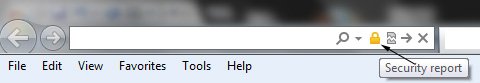
  2. Also look for a lock sign in the address bar as shown in picture below.

website lock

  1. Online transactions in Indian has two step authentications, where apart from using the card number and CVV (three digit number on the reverse side of the card) you need to use password a one-ime password provided by your bank and the secured access password via Verified by Visa and Master secure code, depending on your card service provider. If the website does not ask for authentication do not go ahead with the transaction.
  2. Check the security certificates on the payment gateways sites. Certificate looks like:-

website certificate

  1. Avoid using credit cards online, instead use virtual credit cards. A virtual card is a new 16-digit number, generated on the basis of your physical credit cards. You also get a CVV2 number and expiry date. You can generate a virtual card by doing a one-time registration with your bank. You get a unique login and password. You will need to specify the amount you want to spend with your virtual card. This ensures your entire credit limit is not exposed to the online transaction.
  2. Get yourself another card with a smaller credit limit, and dedicate this card for use in online transitions alone. That way you would decrease the risk of exposing a high credit limit online.

Offline Transaction:-

There is not much you can do about frauds that happen on your physical card. As card can be cloned easily by doing offline transaction, if person swipe your card on machine which capture data of card he/she can create clone easily. You can take following precaution to prevent this.

  1. Never give card to anyone. While shopping closely watch your card that it is not swiped on any other machine. But in some cases it is noticed that hacker has attacked EDC machine and stolen all data in this case you can’t do much about this.
  2. Move to a chip-and-PIN-based card. This card has a sim-card like chip on the front of the card and can be used only with a four digit PIN. So, unless you punch the PIN into the EDC machine, the card transaction won’t go through. Also chip-based card, the account information is stored on the chip and that too in an encrypted format. Since chip-based card stores the data in an encrypted format, the data cannot be skimmed.
  3. Also ensure that you blacken the CVV number (the three digit number at the reverse of your card) with a permanent ink marker. And, memories the number instead. That way, the fraudster won’t have access to this sensitive information.

The truth is that fraudsters are getting sophisticated by the day. So you have no option but to be careful and follow the tips given above to avoid any fraud.