Blog Page 322

7 Best Free Credit Card India

0

Credit card in India has become important payment instrument for the middle class and upper-class families. It eliminates a need of carrying cash and help you to do shopping without money. It also offers multiple lucrative benefits such as cash back and rewards. However, many people don’t opt for a credit card due to annual fees and charges. In order to help them here is a list of 7 Best Free Credit Card in India. These type of card are also known as life time free cards or credit cards with no annual fees.
Business Credit Card Cashback

7 Best Free Credit Card India

#1. Standard Chartered Platinum Reward Credit Card

First life time free credit card without any annual fee is Standard Chartered Platinum Reward Credit card.  A special advantage of Standard Chartered Platinum Reward Credit card is this card provides a lucrative offer of 20% cashback per month on Uber rides. This means you can save sustainable amount on Uber ride per year.

5 Best Premium Credit Card in India

Best Suited for – Salaried People

Additional Benefits –

  • No Annual and Joining Fees
  • Earn 5 reward points for every Rs.150 spend on dining outlets and on fuel.
  • 20% discount for first time user of the big basket.
  • 1000 reward points on the first transaction of a credit card.
  • Additional 500 reward points for registering online banking.

You can apply for Standard Chartered Platinum Lifetime Free Credit Card from Here.

#2. ICICI Platinum Chip Credit Card
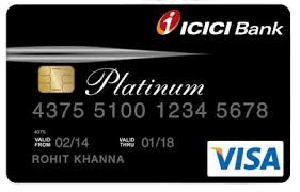
ICICI Platinum Credit Card

ICICI Platinum Chip credit card is life time free credit card. This card is claimed to be lifetime free card by ICICI. However, you need to Rs.50000 or above using this card to waive off annual fees.

Best Suited for – First-time credit card users

Features and Benefits –

  • 15% saving on dining bill
  • Fuel surcharge 1% waiver
  • Earn 2 payback point on every Rs.100 spent
  • Extra layer of security

Top 5 Best Business Credit Card in India

If we compare both Standard Chartered Platinum card with ICICI Platinum Chip card it is clear that Standard Chartered Platinum Card is a better choice.

Apply for ICICI Platinum Chip Credit Card.

#3 HSBC Visa Platinum Card

HSBC Visa Platinum Card is one of the best cards without any annual or joining fees. This card offers multiple benefits such as cash back, free movie voucher & fuel surcharge waiver.

Best Used for Cashback

Features and Benefits –

  • 10% cashback on all spends during first 90 days.
  • 15% discount as dining privileges in major cities.
  • Fuel Surcharge Waiver
  • Movie Voucher Offer
  • Multiple reward and discount on selected products.

#4 Kotak Royale Signature Credit Card

Kotak Royale Signature Credit card is lifestyle credit card. This card is offered with annual fees of Rs.999. However, this fees can be waived off at an annual spend of 1 Lakh.

Best Used for Life Style Expenses

Features and Benefits –

  • 4x and 2x Reward points
  • Fuel Surcharge Waiver
  • Free access to Airport Lounge
  • 5 Lakh cover against fraudulent usage

#5 SBI Simply Save

SBI Simply Save is another best credit card. This card is not a free credit card. The annual fee of this card is Rs.499, this fee can be waived off if your annual spend is Rs.90000 or above.

Best Used for Reward and saving money

Features and Benefits –

  • Enjoy 10x Reward per Rs.100 spent on Dining, Movies, Department stores, and Grocery
  • Fuel surcharge waiver
  • Auto utility bill payment
  • Cash on the Go Facility

#6 HDFC Moneyback Card

HDFC Moneyback as the name suggests it is best suited free credit card in India for Money back. The annual fees for this card can be waived off by spending Rs.50000 using this card.

Best Suited for Moneyback and Online Shopping

Features and Benefits –

  • 2x Reward Points on online shopping
  • Zero liability on lost card
  • Fuel Surcharge waiver

#7 Citibank Rewards Domestic Credit Card

Citibank Rewards Domestic Credit card is one of the best free credit cards in India. Annual fees of this card will be waived off if your annual spend is more than Rs.30000 per year. This card offers extensive rewards benefits on shopping.

Best suited for Rewards

Features and Benefits –

  • 10X Reward Points for every Rs125 spent at departmental store
  • 5% saving across participating restaurants
  • Personal Concierge Services
  • Gift Vouchers Benefits

Don’t forget to share 7 Free Credit card in India with your friends and relatives.
Loan against LIC Policy – Online Facility

0

Ever found yourself in a tight spot where you needed quick money but didn’t want to break your savings or sell your assets? That’s where a Loan against LIC Policy – Online Facility comes to the rescue! Instead of panicking or swiping your credit card at sky-high interest rates, you can actually borrow against the life insurance policy you already hold.

It’s like borrowing from your future self while keeping your coverage intact. Sounds interesting, right? With the online facility introduced by LIC (Life Insurance Corporation of India), the whole process has become smooth, paperless, and super convenient. You don’t need to stand in long queues or chase an LIC agent—you can manage everything with a few clicks.

But wait, how does this loan against LIC policy actually work? What’s the eligibility? And is it really better than a personal loan? Let’s break it down step by step.

Loan against LIC Policy

What is a Loan against LIC Policy?

A Loan against LIC Policy is simply borrowing money using your LIC life insurance policy as collateral. Instead of surrendering your policy for its cash value, LIC allows you to take a loan against it.

Here’s the deal:

  • Your policy acts as security.

  • LIC lends you a percentage (usually up to 90%) of the surrender value.

  • You continue enjoying life cover while repaying the loan.

It’s a win-win: you get the much-needed funds, and your policy doesn’t lapse.

How Does the Loan against LIC Policy Work?

Think of it like pawning an asset but without losing ownership. Here’s how it works:

  1. Check Eligibility – Only policies with a surrender value (like whole life, endowment, or money-back plans) qualify. Term plans don’t count because they don’t have a surrender value.

  2. Apply Online – Use the LIC customer portal or app to request a loan.

  3. Loan Sanction – LIC calculates the surrender value and sanctions up to 90% of it.

  4. Fund Transfer – The approved loan amount gets credited directly to your bank account.

  5. Repayment – You pay simple interest (quarterly or annually) and can repay the principal anytime.

It’s way quicker than running to a bank for a personal loan, and the interest rates are usually lower too.

Why Choose a Loan against LIC Policy – Online Facility?

So, why not just swipe your credit card or apply for a personal loan? Well, here’s why this facility stands out:

  • Lower Interest Rates – LIC loans typically have interest rates around 9–11%, which is cheaper than personal loans (12–24%) or credit cards (30–40%).

  • Hassle-Free Process – No credit check, no endless paperwork, no income proof required.

  • Quick Disbursal – Funds are transferred within a few days—sometimes within 24 hours.

  • Flexibility in Repayment – Interest-only repayment option; principal can be repaid later.

  • Policy Coverage Continues – Even with a loan, your life cover remains active.

  • Online Convenience – Apply, track, and repay—all from the comfort of your home.

Eligibility for Loan against LIC Policy

Not every LIC policyholder is eligible. Here’s what you need to qualify:

  • The policy must have acquired a surrender value (generally after 3 years of premium payments).

  • The loan facility isn’t available on term insurance or ULIPs.

  • Premiums must be up-to-date. If your policy is in lapse, you can’t apply.

  • Policyholders must have a valid LIC online account for online applications.

Documents Required for Online Loan against LIC Policy

Thanks to the online facility, documentation is minimal. Usually, you’ll need:

  • LIC Policy number

  • Registered mobile number and email

  • Bank account details (linked with LIC)

  • PAN or Aadhaar (if not already updated with LIC)

Since everything is integrated online, in many cases, you don’t even need to upload documents if your KYC is already verified.

Step-by-Step Guide to Apply for Loan against LIC Policy Online

Let’s make it simple:

  1. Register/Login at LIC’s customer portal or LIC app.

  2. Navigate to “Online Loan” under Policy Services.

  3. Select your policy eligible for loan.

  4. Enter bank details (if not already updated).

  5. Submit the loan request.

  6. E-sign (using Aadhaar OTP).

  7. Wait for sanction and loan disbursal.

That’s it—no physical visits, no signatures on piles of forms!

Interest Rates on Loan against LIC Policy

The rate of interest on a loan against LIC policy is usually linked to LIC’s declared rates. For example:

  • As of recent updates, the rate hovers around 9–11% p.a.

  • Interest is charged on a half-yearly basis.

  • Unpaid interest gets added to the principal.

This makes it cheaper than personal loans, overdrafts, or credit card cash advances.

Repayment Rules

Repayment is flexible and borrower-friendly:

  • You can repay anytime during the policy term.

  • Only the interest must be paid regularly.

  • Principal repayment isn’t bound by EMI rules.

  • If you don’t repay before policy maturity, LIC deducts the outstanding loan from the maturity/survival benefit.

This ensures there’s no pressure like regular EMIs from banks.

Pros of Loan against LIC Policy

✔️ Quick and easy cash
✔️ No credit score check
✔️ Lower interest compared to personal loans
✔️ Flexibility in repayment
✔️ Policy remains active

Cons of Loan against LIC Policy

❌ Available only if your policy has surrender value
❌ Limited loan amount (depends on policy value)
❌ If unpaid, outstanding loan reduces maturity benefit
❌ Not ideal for very large funding needs

Loan against LIC Policy vs Personal Loan

Factor Loan against LIC Policy Personal Loan
Interest Rate 9–11% 12–24%
Collateral LIC policy None
Approval Time 1–3 days 3–7 days
Credit Check Not required Mandatory
Repayment Flexibility High Fixed EMIs
Loan Amount Depends on policy value Higher limits

Clearly, a loan against LIC policy is more pocket-friendly if you need small to medium funds quickly.

When Should You Take a Loan against LIC Policy?

It makes sense if:

  • You need urgent short-term funds (medical emergency, child’s education, travel).

  • You don’t want to disturb your savings or investments.

  • You’re looking for a cheaper alternative to a personal loan.

But avoid if:

  • You need a very high loan amount.

  • You’re unsure about paying back interest regularly.

Tips before Applying for Loan against LIC Policy Online

  • Always check the surrender value of your policy before applying.

  • Compare the interest rate with other loan options.

  • Pay at least the interest regularly to avoid compounding burden.

  • Avoid over-borrowing—take only what’s required.

  • Keep track of loan details on the LIC portal.

FAQs

Q1. Can I take a loan against any LIC policy?
No, only those policies with surrender value (like endowment or money-back plans) qualify. Term plans and ULIPs don’t.

Q2. What’s the maximum loan I can get?
You can borrow up to 90% of the surrender value of your policy.

Q3. Do I need a guarantor for the loan?
No, your policy itself acts as collateral.

Q4. How long does it take to get the loan?
With the online facility, you can get funds within 1–3 working days.

Q5. What if I don’t repay the loan?
The outstanding loan (including interest) will be deducted from your policy’s maturity or death benefit.

Q6. Can I repay the loan early?
Yes, you can repay partly or fully anytime without penalties.

Q7. Is the online loan safe?
Yes, the process is secured by LIC’s portal and Aadhaar-based e-signature authentication.

Conclusion

A Loan against LIC Policy – Online Facility is like having an emergency money cushion tucked inside your insurance policy. It’s faster, cheaper, and far less stressful than chasing personal loans or swiping credit cards.

By borrowing against your LIC policy, you’re not only unlocking funds but also ensuring that your life cover stays intact. Of course, it’s not the answer for everyone—if you need massive funds or struggle to manage repayments, you might want to explore other options.

But for most policyholders looking for quick, hassle-free liquidity, it’s a financial lifesaver. Next time you face a cash crunch, don’t stress—your LIC policy has your back!

LIC Jeevan Utkarsh Policy 846 – Features, Benefits and Review

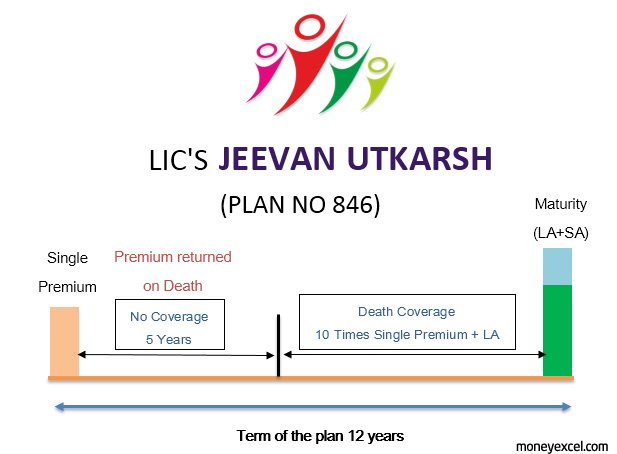
LIC Jeevan Utkarsh is a single premium, non-linked, with-profits, saving cum insurance plan. It is a traditional close ended plan. A launch date of LIC Jeevan Utkarsh (Policy 846) is 6th Sept 2017. The plan will be available up to 270 days from launch date. As it is non-linked plan amount is not invested in stock market. The risk cover of the plan is ten times of Tabular Single premium.

LIC Jeevan Utkarsh Plan – Key Features 

  • Premium – LIC Jeevan Utkarsh is a Single Premium Policy.
  • Term – The term of this plan is 12 Years.
  • This plan offers options for accidental death and disability benefit rider.
  • On the Life Assured surviving to the end of the policy term, “Sum Assured on Maturity”(Basic Sum Assured) along with Loyalty Addition, if any, shall be payable.
  • Insurance coverage will start only after five policy years. If death occurs within five years, the only refund of Single Premium (without interest) shall be available.
  • New Settlement Feature is a unique feature of this plan.
  • Loan Facility is available after 3 months from the policy start period.

LIC Jeevan Utkarsh

Eligibility Condition for LIC Jeevan Utkarsh –

  • Min Entry Age – 6 Years (Completed)
  • Max Entry Age – 47 Years
  • Mode of Payment – Single Premium
  • Min SA – Rs. 75000/-
  • Max SA – No limit
  • Policy Term – 12 Years

Also Read – LIC Jeevan Shiromani – Moneyback Plan | Features Reviews

Benefits Jeevan Utkarsh Policy 846

Maturity Benefits of LIC Jeevan Utkarsh Plan

On Maturity of Jeevan Utkarsh Plan “Sum Assured” (Basic Sum Assured) on Maturity along with Loyalty and bonus if any shall be payable.

Death Benefits of LIC Jeevan Utkarsh Plan

(a) On Unfortunate death within first 5 years of policy

This policy does not provide any insurance coverage during first five years of policy terms. This means on the unfortunate death of the policy holder within first 5 years of the policy term, no benefit shall be payable. LIC will refund single premium without any interest and tax amount to the nominee.

(b) On Unfortunate death after 5 years before 12 years (Policy Term)

Sum assured equal to 10 times single premium along with loyalty addition shall be paid to the nominee.

New Settlement Option under LIC Jeevan Utkarsh 846 Plan

Settlement Option is unique feature introduced by LIC. Settlement option is an option to receive claim amount (i.e. Maturity Benefit or Death Benefit) in installments over the chosen period of 5, 10 or 15 Years instead of lump sum amount. This option can be exercised only by the Life Assured aged 18 years or above for full or part of the Death/Maturity amount.

The Installments shall be made in advance at yearly or Half Yearly or quarterly or monthly intervals, as opted for, subject to minimum installment amount for different modes of payments. Minimum Installment payment would be Rs.5000. The Interest rates applicable for arriving at the installment payments under Settlement Option shall be as fixed by the Corporation from time to time.

The Death claim amount shall then be paid to the nominee as per the option exercised by the Life Assured and no alteration whatsoever shall be allowed to be made by the nominee.

Also Read – LIC Bima Shree (Plan 848) – Key Features, Benefits & Review

Review – LIC Jeevan Utkarsh Policy

Few important points about LIC Jeevan Utkarsh 846 Plan as a part of the review is given below.

  • LIC Jeevan Utkarsh Policy term is only 12 years. This period is not sufficient from the insurance point of view.
  • This policy does not provide coverage for first 5 years of the policy period.
  • It is claimed to be endowment plan where insurance and investment are mixed. You can expect 5-7% return from this plan.
  • It is single premium policy. This means once you buy this policy your money will be locked at least for 12 years.
  • Settlement Option is introduced as a unique selling point of this plan. However, it is a complex option and most of the things are in control of LIC.
  • A death claim shall be paid as per option exercised by the policy holder. Nominee cannot change any exercise option.
  • Two positive sides of this policy are 80 C tax benefit and insurance coverage up to 10 times single premium.

From above points, it is clear that although synonyms of LIC Jeevan Utkarsh is superior return and coverage it may not live up to mark.

10 Best Profitable Investment Options in India

0

Where to invest money? Which are the best investment options in India? These are commonly asked questions with varied answers. For conservative investors fixed investment instruments are the best investment option while for aggressive investors stock market best investment option. Whatever the case one thing is sure it is better to invest money rather than keep it idle. Investment helps you to meet your financial obligations like children’s education, post-retirement expenses, children’s marriage, etc. It also helps you to achieve financial freedom in the long run. In short, investment is making your money work for you. Keeping these thoughts in mind 10 Best Profitable Investment Options in India are given below.

investment options

10 Best Profitable Investment Options in India

  1. Start Up

Investment in a startup is a risky yet profitable investment option in India. Startup companies are like rising sun with huge upside potential and increases in valuation. There are many examples where people have earned a lot of money by investing in startup companies. The example like an employee becoming crorepati by opting for ESOP in Flipkart during a startup time is known to everyone. Few famous investors like Ratan Tata and Rakesh Jhunjhunwala also consider start up as a profitable investment option.

Who should invest in startups?

The startup is a slightly risky investment option. A person with excess cash and high risk-taking capacity can opt for investing in the startup.

  1. Stock Market

A stock market investment is another best investment option in India. Stock market investment can make you wealthy in short period of time. There are many examples of Mutlibagger stocks like MRF, Caplin Point Laboratories, Infosys, TCS that have made investors wealthy over the long run. However, it is difficult to identify good stock for Investment. If you have the skill to identify future multibagger stock for investment you should invest in the stock market.

Who should invest in Stock Market?

Knowledge and skill are must for stock market investment. If you have knowledge, skill and high-risk taking capacity you can plan to invest your money in the stock market.

Top 10 Long Term Investment Options in India

  1. Mid Cap & Small Cap Mutual Funds

Mid Cap & Small Cap Mutual funds are one of the most profitable investment options in India. In last one year, few mid-cap & small-cap mutual funds have generated more than 40% return for the investor. You can opt for Systematic Investment Plan (SIP) or lump sum method for investment.  It is better to select a direct mutual fund for investment. Direct mutual fund always gives you better returns compared to normal mutual funds.

Who should invest in Mutual Fund?

If you want to balance risk and return mutual fund investment is for you. You can expect very good returns from mutual funds over a long run.

  1. ELSS

ELSS or Equity link saving scheme is next best investment options in the list for tax saving. ELSS is a type of mutual fund that helps you to save tax and generate wealth. ELSS can generate 20-25% returns for the investor. However, ELSS comes with lock in period of three years.

Who should invest in ESS?

If you are looking for Tax saving option along with wealth generation ELSS is for you. You can claim deduction up to 1.5 Lakh by investing in ELSS.

  1. PPF

PPF or Public Provident Fund is most popular investment option in India. PPF offers an interest rate of 7.8%. PPF investment also offers tax benefits under section 80C. The PPF matures in 15 years. You can withdraw money from PPF account after 6 years.

Who should invest in PPF?

PPF is particularly relevant for individuals with a low-risk appetite looking to save money over the long term for retirement planning or any other long-term financial goal. A high-risk investor can also invest in PPF to balance their portfolio.

  1. Peer 2 Peer Lending

Peer 2 Peer Lending is new investment option in India. In this option, you need to lend money to individual or business through online services. You can expect 15-20% gain by lending money. However, it is risky investment option as a chance of losing money is high.

Who should invest in Peer 2 Peer Lending?

An investor with excessive cash and high risk taking capacity can opt for Peer 2 Peer lending option. You need to carry out due diligence before lending money to anyone.

  1. Real Estate

Real estate is profitable investment option over a long run. Real estate has many prospects like hospitality, commercial, retail, housing, manufacturing. However, money required for making an investment in real estate is huge. You can expect a decent return from real estate over a long run.

Who should invest in Real Estate?

If you have excess cash and you have exhausted by making an investment in other investment options you can invest in real estate. Real estate investment is nonliquid in nature and may require black money for investment.

  1. Company Fixed Deposit

Company Fixed deposit is beneficial investment option in comparison to the bank FDs. A company fixed deposit give superior return compare to normal bank FD’s. These types of FD comes with lock in period hence, you need to be careful in a section of the investment period. Company insurance scheme is not backed by Insurance.

Who should invest in Company Fixed Deposit?

A  conservative investor looking for risk return balance and long term fix gain can invest in company fixed deposit. You can expect 12-14% gain from company fixed deposit.

  1. Post Office Savings Schemes

Post office saving scheme is also on the list of best investment option in India. The post office offers multiple schemes for investment based on investors need. You can opt for Monthly Income Scheme, Recurring deposit, Sukanya Samrridhi Scheme for investment. All these schemes offer a return in the range of 8.5-8.7% return.

Who should invest in Post Office Saving Schemes?

If you are a conservative investor looking for the fixed return you can plan to invest in post office saving schemes. You cannot gain hefty returns from this schemes. However, your capital would be protected.

  1. Bonds

The last best investment options in the list is Bonds. If you are not comfortable in investing in risky investment options you can invest in bonds. There are several good bonds in the market that provide a high return on investment. Bonds are regulated by the government. A 10-year bond typically offers 8% interest.

Who should invest in Bonds?

A risk averse investor looking for long term fix gain can invest in bonds.

How to select best investment options?

You should consider following factors for the selection of Best Investment Options.

  1. Investment Objective – You should be clear about your investment objective before making an investment.
  2. Tenure – Second point for consideration is tenure. Investment options are different for long term and short term.
  3. Risk Taking Capacity – Another factor that matters for the selection of investment option is risk taking capacity. If you are high risk investor you can consider equity or real estate for the investment.
  4. Tax – Tax is another important factor in the selection of Investment. Tax saving options are different compared to normal investment options.
  5. Liquidity –  Your requirement of cash can affect the selection of investment option. Some investment options do not provide liquidity. Make sure to select right investment option as per your need.