

Blog Page 257

Pay LIC Premium Online via LIC portal, Mobile App & Paytm

Pay LIC Premium Online – It is easy to pay LIC premium online. You can make use of the LIC Portal or Paytm for paying LIC premium online. In this post, I will explain a method of registering for LIC online services and paying LIC premium online. I will also share additional methods of paying premiums via Paytm.

Pay LIC Premium Online

Through Consumer Portal

Life Insurance Corporation of India provides various online services to the policyholder. It includes policy registration, online premium payment and downloading premium paying certificate. This facility saves a lot of time as you need not visit LIC branch and stand in queues to get your work done.

LIC Login is mandatory to avail of these facilities. You will get LIC Login once you register on the LIC portal. If you are holding LIC policy it is recommended to register for LIC Online Services.

Here is a step by step process to register online for LIC Online services including online premium payment and premium payment statement download facility.

Also Read – Top 7 Best LIC Policy for 2020

LIC Online Services – Facilities

The list of services that can be availed by LIC Online Services is given below. 

  • Policy Details
  • Policy Status
  • Bonus Status
  • Online Premium Payment
  • Assignment and nominee status
  • Premium paid certificate
  • Complaint registration
  • Claim Status
  • Loan Status
  • Revival Quotations
  • Policy condition and other features

LIC Login Registration Process 

In order to register online for LIC services you require a policy number, policy premium amount (without tax), date of birth of policyholder, mobile number of policyholder, e-mail ID and a scanned image of PAN card or Passport. The size of the image should be less than 100 KB and file format should be jpg,png,bmp,gif or tiff.

Once you have the above information you can proceed with new user registration.

Step 1 – Visit the LIC website – www.licindia.in and Click on e-registration. You will be taken to the new page where you need to click on the New User.
Pay LIC Premium Online

Step 2 – On the new form provide details such as policy number, premium, birth date, mobile number, e-mail id, and gender.

Step 3 – Click on the submit button. You will be asked to select a user id and password for your choice.

Step 4 – Now you can log in via the newly created user ID and password and use basic services. You need to enroll for all your policies by clicking on “Add Policy”.

Step 5 – In order to enable premier services, click on the Service Registration from the dashboard. Now select Service Request for Premium Service Registration from the drop-down option.

Step 6 – Click on the proceed button. Now provide name, date of birth, Aadhaar UID, mobile number, e-mail ID and PAN number.

Step 7 – Click on the “Generate Application Form”. A new service request ID will be generated. Now you need to download and print the registration form.

Step 8 – Check the details given on the registration form and sign it. Upload the signed form along with the KYC document PAN or passport via the provided option. After documents are uploaded click on the submit request.

An acknowledgment SMS and e-mail will be sent to the mobile/e-mail id provided in the registration form. This request will be sent for verification. Once rthe equest is verified you will be intimated via e-mail and SMS about the enablement of premium services. 

LIC Login Online Premium Payment Process 

Online payment using the LIC online service is very easy. You need to sign in to the LIC portal with the registered username and password as a customer.

Once you sign in you will be able to see a dashboard showing various options such as basic services, premier services, online payment, profile management, etc.

You need to click on the online payment tab for online premium payment. The screen will show premium due policies. You need to select the policy for which you want to make payment. It also gives the option for paying for all premiums at single go as well as advance premium payment.

Now click on Check and Pay. The system will show billing invoice details mentioning policy number, date, amount, mobile number, and e-mail ID. Once you click on Check and Pay you will be prompted with bill payment options.

Select the suitable option and proceed with the payment of the premium. On the completion of the transaction, a premium receipt will be sent to your registered e-mail id. 

 Pay Direct (Without Login)

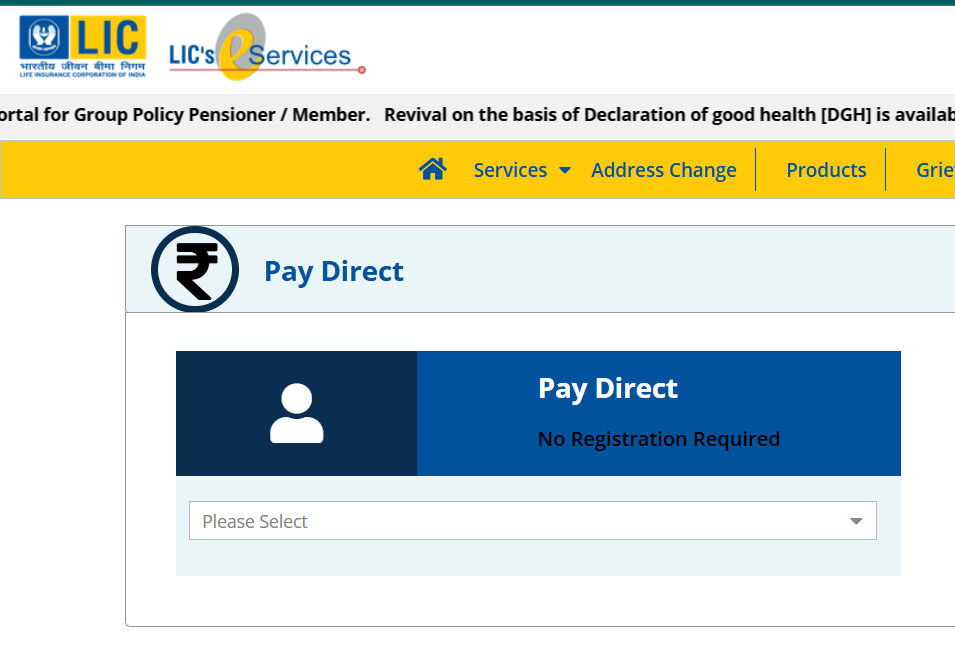
You can also pay LIC premium online without login. It is also known as the Pay Direct Option. In order to make a payment via this method click on the Pay Premium Online option given on the LIC website.

You will be taken to a new page where you need to click on the Pay Direct(Without Login) option.
lic payment direct online


Select the Renewal Premium/Revival or Advance Premium Payment option. You can make loan repayment or loan interest payments using this option also. After selection, you will be taken to a new page where you need to provide your policy number, date of birth, mobile number, premium installment amount, and e-mail ID. Scroll down and select I agree button.

Now press the Submit button. The system will validate details from the LIC database and take you to the payment page.

Here you need to select a payment option. You can pay via debit card, credit card, and via Internet banking. The premium receipt will be generated and sent to a specified e-mail address.

Pay LIC premium via the Mobile App

You can also make premium payments viathe  Mobile App. You need to download the LIC PayDirect app from Google Play.

It is the official app from LIC. You can make LIC premium payment on the app by providing policy name, date of birth, premium installment amount, and other details. You can also make use of this app to view Premium paying transactions online.

Through Paytm

To pay LIC premium online using Paytm follow the steps given below.

Step 1: The first step is to download and Install the Paytm App on your mobile. Once it is installed open Paytm Application or just visit Paytm.com

Step 2: On the Paytm application, click on the More button.

Go to the Recharge and Bill Payment Section.Tap on “Insurance”

Paytm LIC Premium

Step 3: You can see all insurance companies list, and select LIC of India.

Step 4: Now enter your Policy number and proceed further

Step 5: On the next screen, your policy details like policy number, name of the policyholder, premium due date, number of the installment due, and premium amount will reflect. Tap on Proceed to Pay. This data is reflected in the LIC database.

Step 6: On the next screen, you can see the promo code page. Skip this option and proceed further to pay.

Step 7: Finally make premium payments using Net Banking, Debit card, credit card, ATM card or directly pay through Paytm wallet.

On the successful payment, Paytm will send you a message on your registered email ID and mobile number for the reference.

Over to you

I hope you have got complete understanding about various method to pay LIC premium online. If you have any queries on LIC premium paying option, please share it in the comment section given below.

Foreign Remittance New Tax Rule – Tax Collected at Source

Foreign Remittance

Foreign Remittance Tax rules are changed. Now you need to pay tax when you transfer money abroad. The new rule will be effective from Oct 1, 2020. The provision for a new rule of Tax Collected at Source (TCS) was made in Budget 2020-21.

There are many cases where you need to send foreign remittances such as for meeting education expenses, medical expenses, buying property abroad or stock market investments. The Liberalised Remittance Scheme (LRS) and RBI rules permit up to $2.5 Lakh of foreign remittance to the individual. This means you can remit up to $2.5 Lakh x Rs.76 = Rs. 1.9 Cr outside India. The remittance amount will now be taxed.

Also Read – Income Tax Calculator FY 2020-21 (AY 2021-22) – Excel Download

In this post, I will share detail about Foreign Remittance New Tax Rule.

Foreign Remittance New Tax Rule 

A Sum of 7 Lakhs in a particular financial year is allowed for the outside remittance. In case the amount of remittance is exceeding 7 Lakh you need to pay tax.

The rate of TCS would be 5% if you have PAN/Aadhaar. In case you don’t have PAN card the rate will be 10%. The TCS amount will be collected by the bank/ authorized dealer at the time of remitting money outside India.

Let’s try to understand this by example. Suppose, you want to do remittance of Rs.15 Lakh under the LRS (Liberalised Remittance Scheme). As this amount is exceeding Rs.7 Lakh limit TCS will be charged. The TCS in the above case would be charged to Rs.8 Lakh. As rate is 5%. Total TCS (Tax collected at source) would be Rs. 35000.

If the remittance is made via a loan secured from a bank or financial institution for the education purpose and amount is exceeding 7 Lakh you need to pay TCS at the lower rate. The rate under this case would be 0.5%. Suppose Rs.15 Lakh is remitted for the education purpose via loan the TCS would be Rs.3500.

The TCS for the foreign remittance is not applicable if TDS has been paid by the remitter under any provision of the Income Tax Act. If the remittance is done by the government or government notified person TCS is not applicable.

If the remitter is NRI then to the TCS charged an increase in surcharge as well as health and education cess are applicable.

The rule of TCS applies to foreign travel also. It is also proposed to apply TCS on the sale of an overseas tour package via tour operators. The TCS would be deducted by the tour operator. The entire tour package would be considered including travel, hotel stay, boarding, and lodging while placing the claim.

Takeaways from Foreign Remittance Tax Change 

Few important takeaways from the foreign remittance tax change are given below.

  • TCS does not mean that tax is paid to the government. It is a tax credit amount. You can file an Income tax return and either get the refund or adjust the amount against tax payable.
  • The new tax rule provision is made not to collect additional tax but to increase tax compliance. Currently, people transferring huge money outside get escape routes from Income tax. The new provision does not allow them to escape.
  • Income tax returns need to be file for getting a refund of tax collected at source money.
  • The amount of TCS remains blocked till the refund amount is obtained or credit is adjusted against your tax liability.
  • Additional paperwork needs to be done along with foreign remittance.
  • Banks and foreign tour operator needs to maintain additional compliance.

Overall it is a very good step taken by the government to increase the tax net. However, the honest taxpayer needs to suffer as their money gets blocked unnecessarily due to this step.

Job Loss or Pay Cut – How to Protect & Manage your Finance?

Losing a job or facing a pay cut can be one of the most stressful experiences in life. Whether it happens unexpectedly or you see it coming, financial instability can create anxiety and uncertainty. However, with the right mindset and strategies, you can navigate through these challenges and emerge financially stronger. This article will guide you on how to protect and manage your finances effectively when dealing with job loss or a salary reduction.

Job Loss Pay Cut

Living a life without a salary or less money would be challenging for many people. You have to change your lifestyle and smartly manage your finance to face and withstand the difficult situation. Here are a few important tips to make yourself ready against the adverse situation of layoff and salary cuts.

Also Read – How to save more money with limited income? – Practical Examples

Job Loss or Pay Cut – How to Protect & Manage your Finance?

Reduce your Expenses by living a frugal lifestyle

You need to live a frugal or economical lifestyle. The lockdown has taught us that we can live life with minimum expenses. We need not waste money on eating out, entertainment, leisure, and buying unnecessary things.

Find out how you can live life with less money. It is not as troublesome as it sounds. You need to note down all your monthly expenses on the paper. Question every expense and try to reduce or eliminate expenses.

Let me give a few examples –

  • Suppose you are living in a rented house which is costing you more money. You should think of moving into a smaller house or in another area where rented home cost is less.
  • If your family has two vehicles you can think of reducing it to one and opting for public transport or other means of transport. You can save a lot of money on fuel expenses by this step.
  • You can also look at your mobile plan and think of converting it to a prepaid plan based on actual usage.
  • Go for cancellation of a subscription such as Prime or Netflix.

Make sure not to go for excessive reduction at a single go. Gradually reduce living expenses and live a frugal lifestyle.

Go for Job Loss Insurance

If you are sure that your job is in danger due to the current financial crisis and your company may give a pink slip to you. Go for Job Loss insurance. Job loss insurance helps you in financial exigencies.

The stand along job loss insurance policy is not available in India. You need to purchase this as add on coverage to other policies. This policy covers EMI expenses. Job loss is not a dependable option as there is a waiting period of one to three months for claim settlement. The coverage offered by the plan is limited.

Few insurance policies that provide coverage to job layoffs are given below.

  • Safe Loan Shield by Royal Sundaram
  • Secure Mind by ICICI Lombard
  • Home Suraksha Plan by HDFC Ergo

Make use of the Emergency Fund

The next step is to make use of an emergency fund. You must have prepared yourself for the bad days by creating an emergency fund. You can make use of an emergency fund.

If you have not yet built an emergency fund it is high time to prepare yourself for the emergency fund. You should build an emergency fund to withstand at least six months of household expenses. Start saving money every month and keeping it aside either in a separate saving bank account or in a fixed deposit.You can help yourself at this time by finding ways to reduce dipping too much into your spare money, so that you are not depleting your finances too fast.

Home warranties are used by many homeowners, so you might want to look into the various ones that are available to ensure you save money. If you own a well pump for instance, you know how bad it can be if it malfunctions, your home needs the flow of water. Taking a look into a well pump warranty will show you how much you can save and get financial support with if your well pump happens to break. You won’t need to dip too far into your funds and you can keep them going for longer.

Look for additional Income  

In this adverse time, you also need to look for additional income. You can make use of your skills and hobbies to generate additional income. There are many part time online and offline options for earning additional income. You can also encourage your dependent, like your spouse to contribute.

Another way to increase your income is by leasing your property to someone.

Also Read – 40 Part Time Jobs from Home Online & Offline – No Investment

Review and Rebalance your portfolio

You should also assess your investment portfolio and rebalance it. Make sure your investment should be spread across various investment avenues. If possible, reduce exposure from the equity market as the market is likely to remain volatile in the days to come.

Invest in the fixed deposit with monthly income or other monthly return instruments. It will surely help you to manage your finance in a better way.

Arrange for additional liquidity

The last option to fight job loss or pay cut is to arrange for additional liquidity. Arranging liquidity at this time would be difficult. However, you can think of selling your investment or breaking your fixed deposit if you are facing severe cash issues.

Final Thoughts

Job loss or a pay cut can feel like a financial earthquake, shaking up your stability and sense of security. However, by taking immediate action, reassessing your budget, and planning for the future, you can regain control over your finances. Remember, tough times don’t last, but financially smart people do. Adapt, stay positive, and focus on rebuilding your financial well-being one step at a time.

FAQs

1. How long should my emergency fund last?

Ideally, an emergency fund should cover 3-6 months of essential expenses to help you stay afloat during financial setbacks.

2. What’s the best way to find new job opportunities quickly?

Networking, updating your resume, leveraging LinkedIn, and applying to multiple positions in your industry can help speed up your job search.

3. Should I take out a loan to cover expenses after job loss?

Taking on new debt is risky. Consider alternatives like cutting expenses, seeking temporary work, or government assistance before opting for a loan.

4. How can I negotiate bills during financial hardship?

Call service providers and creditors to request extensions, reduced rates, or flexible payment plans. Many companies offer hardship programs.

5. What side hustles can I start after a pay cut?

Freelancing, online tutoring, rideshare driving, selling handmade goods, or starting a small online business are great side hustle options.

6. Can I pause mortgage or rent payments during financial difficulty?

Some landlords and lenders offer forbearance options. Communicate with them early to explore any available assistance programs.

7. How do I cut my expenses without sacrificing my quality of life?

Focus on needs over wants, cook meals at home, use coupons, cancel unnecessary subscriptions, and find free entertainment options.

8. Should I dip into my retirement savings if I lose my job?

This should be a last resort as withdrawing retirement funds can have penalties and tax implications. Explore all other options first.

9. How can I prepare for potential job loss in the future?

Build an emergency fund, upskill, diversify income sources, network consistently, and keep your resume updated.

10. Is it possible to negotiate a salary after a pay cut?

Yes! Once your company stabilizes financially, you can discuss performance-based raises or promotions to regain your original salary.

Converting Credit Card Bill to EMI – Good or Bad?

Converting Credit Card Bill to EMI– Credit Card EMI is one of the most popular methods used nowadays for shopping. You might have seen an option on shopping site to convert your credit card payment to EMI. Converting a credit card bill to EMI means clearing credit card dues by EMI (Loan). You must be aware that there are two options to pay a credit card bill. You can either pay a full bill before the due date or you can pay minimum amount due. If you have difficulty in finding options to pay credit card bill, you can go through the article – 10 Methods to Pay Credit Card Bill Online and Offline. If you clear full fill before the due date you need to pay any interest. However, if you clear only minimum dues you need to pay interest amount.

EMI Conversion for clearing credit card due is another method. This method is used to attract the customer who is unable to pay entire bills on time. It is a convenient and easy option.

credit card bill to emi

How credit card bill to EMI option works?

In credit card EMI option you need to pay little amount every month. This option is similar to other loan EMI. Here you need to pay a portion of principal dues and interest component every month till the full amount is paid.

The option for EMI is available at the time of purchase or at the time of making credit card bill payment. Bank offers this option based on your card and credit behavior. At the first instance, you may find this option very useful as you can save yourself from paying a lot of money at a single go. However, you need to evaluate this option as a whole before opting.

How to convert Credit Card Bill to EMI Option?

The process of converting your credit card bill to EMI is very simple. You can use net banking, SMS or phone banking to avail this facility. Few banks also provide this facility via mobile app. The step by step method to convert credit card bill to EMI in SBI, ICICI is given below.

SBI Credit Card Bill to EMI

Through SBI Net Banking

  • Login to SBI Net Banking Account.
  • Under the Benefit Menu click on Flexipay.
  • Select the transaction which you want to convert to EMI.
  • Make selection of repayment period and confirm.
  • Your transaction will be converted to EMI.

Through SMS

You can also use method of SMS to convert your bill to EMI. You need to send SMS “FP” to 56767. You will receive call from SBI executive asking for detail about transaction which you want to convert to EMI. On sharing details your transaction will be converted to EMI.

ICICI Credit Card Bill to EMI

Through ICICI Net Banking

  • Login to ICICI Net Banking account.
  • Go to My Account and select credit card option.
  • Select Convert to EMI option from Menu.
  • Select credit card detail, EMI tenure and transaction.
  • On submission your transaction will be converted to EMI.

Through iMobile App

  • Download iMobile App and Register with your account.
  • Go to Cards section and select the credit card.
  • You will be able to see recent transactions.
  • Select the transaction and click on convert to EMI option.
  • Provide required detail for conversion.

Points to consider before taking credit card due to EMI option

You should consider following facts before converting your credit card dues to EMI.

Interest rate

The conversion to EMI is not free. You need to pay interest on the due amount. The interest rate range between 12-18% per annum. This rate of interest is lower compared to credit card interest rate which is in the range of 30-40% per annum.

Processing Fees

In order to convert credit card dues to EMI, you need to pay processing fees. The processing fees vary from bank to bank. Few banks do not charge any processing fees for the conversion of a credit card bill to EMI. The processing fees can be negotiated with bank.

Credit Limit Reduction

Once you opt for this facility your credit limit will be reduced by amount which you have opted for converting EMI. Your credit limit will increase by the amount you pay in EMI. Suppose your initial credit limit is Rs.150000 and you have opted for EMI facility for the amount Rs.40000. Your credit limit will be Rs.110000. It will increase every month with payment of EMI amount.

Over to you

Converting credit card bill to EMI is costly option as you need to pay additional interest cost on the goods purchased. It is recommended to use this option only in emergency when you are unable to pay your dues in time.

Do you use this facility? Do share your experience with us.