Blog Page 13

Reliance Option Chain Explained: What Every New Investor Should Know After Demat Account Opening

Stepping into the derivatives market marks an exciting milestone for retail wealth builders searching for sophisticated strategic tools. Immediately following a successful demat account opening sequence, a beginner faces massive amounts of real-time market metrics. Among these data pools, few structural instruments are as universally significant as a modern option chain matrix. Learning to read these financial grids protects your hard-earned capital from unguided, emotionally driven trading mistakes.

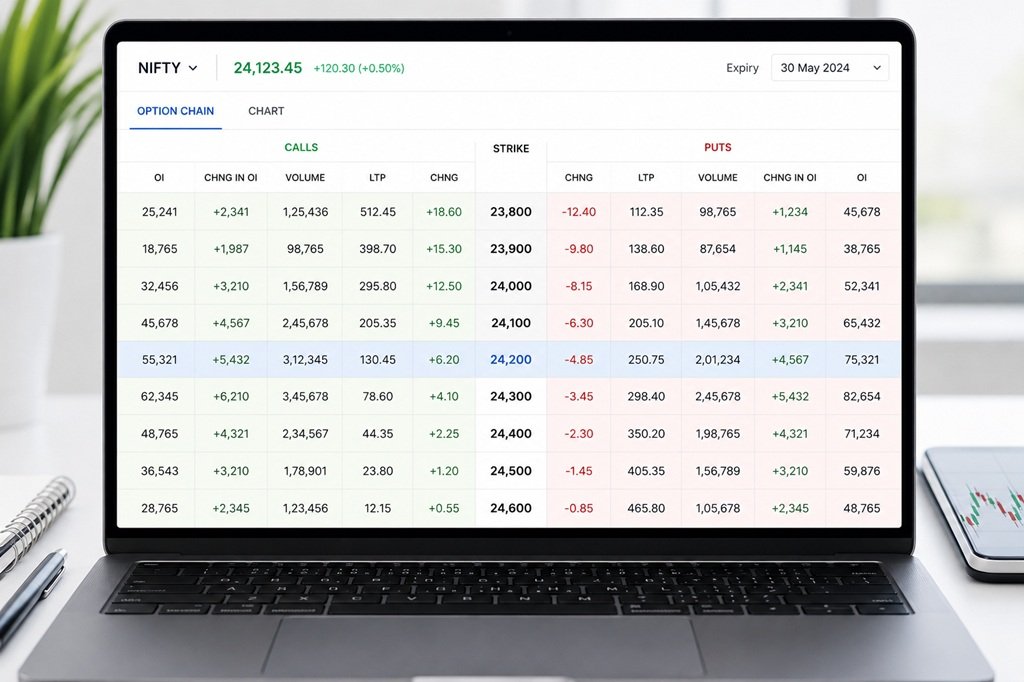
option chain

Understanding the Basics: What Is an Option Chain?

An option chain is a comprehensive, structured data table listing all available options contracts for an asset. It provides a clean, side-by-side view of call and put options arranged around central strike prices.

Key Components of an Option Chain

  • Strike Price: The predetermined mathematical rate at which the underlying stock contract can be actively exercised.
  • Option Premium: The current market price paid by buyers or collected by sellers to secure an open position.
  • Open Interest (OI): The total aggregate volume of outstanding derivative contracts that remain live and unexercised.
  • Implied Volatility (IV): A percentage metric showcasing the market’s expected speed of near-term underlying asset fluctuations.

Why Investors Use Option Chains

Traders inspect this synchronized table to gauge immediate consumer sentiment, evaluate trading volume, and identify potential market turning points. It transforms disjointed numbers into an explicit map showing strong zones of directional support and overhead price resistance.

Why Reliance Industries Is Popular in the Options Market

High Liquidity and Trading Volume

Reliance Industries options consistently display massive institutional and retail participation across the National Stock Exchange. This heavy trading volume ensures exceptionally tight bid-ask spreads for single derivative contracts. High liquidity guarantees that a retail saver can enter or exit option positions rapidly without facing bad execution slippage.

Strong Market Presence

As a heavyweight corporate component in major indexes, Reliance significantly dictates broad public market movements. Institutional managers frequently buy its options to hedge massive, underlying stock portfolios against sudden down cycles.

Regular Market Movements

The stock frequently exhibits clear technical trends driven by major corporate adjustments, earnings cycles, and macroeconomic factors. This steady, predictable price activity creates regular trading opportunities for derivative strategists looking to tap into structural trends.

Important Terms Every New Investor Should Know

  • Open Interest (OI): Measures total outstanding market contracts to show where large institutional participants are parking capital.
  • Change in Open Interest: Tracks the daily net shifting of contracts, confirming if a trend is strengthening or fading.
  • Volume: Represents the cumulative number of option contracts executed within a single active trading session.
  • Implied Volatility (IV): Dictates premium inflation; elevated IV levels signal upcoming risk and cause option premiums to swell.
  • Option Premium: The shifting cash price a trader pays to buy contract rights before their official expiration.

Common Mistakes New Investors Make

  • Treating Options Like Lotteries: Buying cheap, deeply out-of-the-money options assuming a massive sudden price spike will occur.
  • Ignoring Implied Volatility: Buying overvalued premiums right before major earnings announcements, only to face severe IV crush drops.
  • Overlooking the Expiration Calendar: Forgetting that stock options expire completely worthless on the final Thursday of their month.
  • Misinterpreting High Open Interest: Assuming heavy open interest implies a bullish breakout, ignoring that sellers dominate those zones.

Risk Factors to Consider Before Trading Reliance Options

Time Decay (Theta): Options are wasting assets; your contract values erode daily even if stock prices stay completely flat.

Volatility Risk: Sharp shifts in market fear levels can cause premium values to collapse suddenly despite accurate direction picks.

Liquidity Considerations: Distant strike prices suffer from low trading volume, trapping users in illiquid positions with wide spreads.

Sudden News and Event Risks: Unscheduled policy announcements or geopolitical adjustments can instantly trigger massive, unexpected gapping against your positions.

Capital Management: The leverage embedded within option lots can quickly multiply losses if risk metrics are completely ignored.

Tips for Investors After Demat Account Opening

  • Master Virtual Trading Tools: Utilize free paper trading screens to understand premium fluctuations safely before deploying cash.
  • Focus on Liquid Strikes: Stick strictly to at-the-money contracts where high trading volumes guarantee effortless trade exits.
  • Deploy Strict Stop Losses: Implement hard systematic exit targets on your active dashboard to automate risk protection.
  • Keep Your Records Updated: Complete your comprehensive demat account opening authentication steps to avoid unexpected back-office settlement holds.

Conclusion

Navigating a live reliance option chain transforms options trading from a guessing game into a calculated technical science. New investors must prioritize platform safety and comprehensive data tracking over fast, short-term speculative gains. Complete your seamless demat account opening procedures, practice proper position sizing rules, and approach the options market with discipline.

Close SBI Savings Account Easily: Online & Offline

0

You can close SBI Saving Account online and offline. There are many reasons why you may go for closure of your SBI Account such as dissatisfaction with services, relocation (moving out of town), death or unused account that is making you incur additional costs such as debit card charges, SMS charges, and minimum balance charges.

This article helps you understand how to go about closing your SBI account either online or offline.

Close SBI Account

How to Close an SBI Savings Account Online?

Presently, there is no option for closing an account online through SBI. You will have to go to your nearest branch, complete the account closure form, and submit it along with proof of identity and documents related to the account. You can visit any nearest branch of SBI for closing account it is not mandatory to visit branch where you have opened your account.

The process of closure can be completed only after clearing all dues and paying closure charges (if applicable).

How to Close an SBI Savings Account Offline?

Here is the process for closing your SBI account without using internet banking services:

Step 1: Go to the nearest branch of SBI and collect the account closure form from there.

Step 2: Fill in the form correctly and submit it at the bank branch.

Step 3: Submit copies of your proof of identity, proof of address, original cheque book, original pass book, and ATM/debit card.

Step 4: If there are any fees, pay them.

The representatives of SBI will process your application and close the account within seven business days.

SBI Account Closure Form

The SBI account closure form is available at the nearest branch of the SBI bank. After receiving the form, it should be filled in along with the relevant documents and submitted to the SBI bank branch where you maintain your account.

How to Close an SBI Account from Abroad?

The application for closure of your SBI account is available from the nearest SBI branch. On receipt of the form, all that you need to do is to complete the form and then submit it along with the required documents to your SBI branch.

Your SBI account can be closed when you are abroad. The following steps will help you close the account:

Step 1: Contact the SBI branch where you have your account. Make the SBI branch aware of your decision to close the account either through a phone call or an email.

Step 2: Send all the necessary documents to the SBI branch with a request in writing to close the account. You will need to provide a copy of your passport, visa, and proof of address.

Step 3: Clear any pending transactions and settle all your dues before the process of closing your account begins.

Step 4: Await the confirmation of the successful closure of your account by the SBI branch and transfer of the remaining balance into the account which you specify.

It should be noted that the procedure of closing an SBI account when you are abroad may vary depending on the place you are at and the policies of the particular SBI branch.

How to Close an SBI Account After Death?

The process for closing the SBI account due to the demise of the account holder includes filling out the claim settlement form.

As a nominee, one can close the SBI account belonging to the deceased by providing the following to the respective bank branch:

  1. The claim settlement form as per the standard format of the bank
  2. Full details of the accounts maintained by the deceased individual
  3. Death certificate issued by the appropriate authority for the deceased account holder
  4. KYC (Know Your Customer) documents for the nominee

In case the deceased account holder does not have any nomination, then his/her legal heirs can fill out the claim settlement form without legal representation and provide the necessary documents to the bank. The claim settlement form without legal representation can also be downloaded from the official website of SBI bank.

The documents required for the closure of an account of a deceased person without a nomination are as follows:

  • For a claim amount below Rs. 5 lakh:
    • Death certificate
    • KYC documents of all legal heirs
    • Account details of the legal heirs, if available
    • Claim form duly filled and signed by the legal heirs, other than those who signed the disclaimer letter
    • Stamped letter of Indemnity from the legal heirs
    • Letter of disclaimer, if applicable
    • Declaration in the claim form signed by one independent person well known to the family of the deceased, any account holder of SBI known to the family of the deceased or any government official whose signature is verifiable by SBI
  • For a claim amount above Rs. 5 lakh:
    • All documents required for a claim amount below Rs. 5 lakh (As listed above)
    • Declaration in the claim form has to be sworn as an Affidavit before the Notary Public or Judicial Magistrate by one independent person well known to the family of the deceased, any account holder of SBI known to the family of the deceased or any government official whose signature is verifiable by SBI
    • Surety, along with the stamped letter of Indemnity
    • Details of Sureties along with proof for compilation of the Opinion Report on Sureties

Documents Required to Close SBI Account

The following are the documents required to close the SBI account:

  • SBI account closure request form
  • Cheque book leaves
  • Debit card
  • Passbook
  • Identity proof documents
  • Address proof documents

Once one learns about closing an SBI account, it is imperative that the process be handled with utmost care and precaution so as not to commit mistakes. One needs to take into consideration the period and fees that go hand-in-hand with closing an account. After submitting the necessary paperwork and clearing all dues, your request will be processed by the bank.

How to Download the SBI Life Insurance Premium Receipt?

Downloading SBI Life Insurance premium receipt can make it easier for customers to get a record of their premiums for taxation purposes. You do not have to worry about downloading your SBI Life Insurance premium receipt because it can be done conveniently through the SBI Smart Care portal.

SBI Life Premium Payment Receipt

What Is an SBI Life Insurance Premium Receipt?

A premium receipt is basically proof that you have paid your insurance premium. It is a digital or printed document issued by SBI Life Insurance after each premium payment is processed successfully.

The receipt contains several important details about your payment and policy. Here is what you will typically find on an SBI Life Insurance premium receipt:

  • Policy number
  • Name of the policyholder
  • Date of premium payment
  • Amount paid
  • Mode of payment (online, cheque, NEFT, cash, etc.)
  • Policy tenure and plan name
  • Financial year in which payment was made
  • Next premium due date
  • Sum assured
  • Agent or broker details (if applicable)

All of this information is useful when you are filing taxes, raising a claim, or simply keeping your financial records in order.

How to Download the SBI Life Insurance Premium Receipt?

Follow these steps for a quick SBI life insurance premium receipt download:

Step 1: Login into the SBI Smart Care website.

Step 2: Select the ‘Policy Documents/Statements’ tab and select the ‘Premium Payment Acknowledgment’ option from the drop-down menu.

Step 3: Key in the policy number and date of birth, and select the ‘Get Acknowledgement’ button.

Step 4: Go through the soft copy and make any necessary corrections.

Step 5: Choose the ‘Download’ button to download an electronic copy of the SBI Life Insurance receipt.

You can also download premium receipt via mobile app.

How to Download SBI Life Insurance Premium Receipt via Mobile App

SBI Life also has an official mobile app called ‘SBI Life – mPolicy’ which is available on both Android (Google Play Store) and iOS (Apple App Store). You can use this app to download your premium receipts from your smartphone. Here is how:

  1. Download and install the ‘SBI Life – mPolicy’ app from the Play Store or App Store
  2. Open the app and log in using your policy number and OTP, or your registered credentials
  3. On the home screen, look for ‘My Policies’ and tap on your policy
  4. Navigate to ‘Policy Documents’ or ‘Statements’
  5. Select ‘Premium Payment Receipt’ or ‘Acknowledgement’
  6. Choose the specific payment for which you want the receipt
  7. Tap ‘Download’ to save the receipt on your phone

Using the mobile app is very convenient, especially if you are on the go or want to access receipts without sitting at a computer.

Purpose of Downloading the SBI Life Insurance Premium Receipt

Once you have made the payment towards your SBI Life Insurance Plan Premiums, you should always go for the SBI Life Insurance premium receipt download. The reasons behind downloading the receipts are:

You get tax deductions on the premiums paid towards life insurance plans. Therefore, downloading the premium receipts of SBI Life Insurance will prove useful when you file your tax returns.

It provides a proof that you have paid the premium and are therefore eligible to enjoy the benefits of the life insurance cover.

The receipts will prove helpful in claiming the life insurance cover by your nominee once you are gone. This will make the whole process of claim easier and faster.

You can check the details of your policy through the premium receipts as all details are mentioned in the receipt including policy number, payment date, amount of premium and policy tenure.

You can calculate the total cost of insurance through these receipts and then take decision regarding insurance coverage.

Tax Benefits of SBI Life Insurance Policy

You will be eligible to get a tax deduction for your SBI Life Insurance premium under Section 80C of the Income Tax Act, 1961. You cannot claim tax deduction for amounts above Rs.1,50,000 under Section 80C.

In case the premium payable for the life insurance policy is below 10% of the sum assured, then the maturity amount or the amount received after the demise of the insured will also be tax-exempt under Section 10(10D).

Process to Pay SBI Life Insurance Premium

Use the following steps to pay premium of your SBI Life Insurance online:

Step 1: Visit SBI Smart Care website and log in with your policy number and MPIN or Policy number and OTP or User ID and password.

Step 2: Select ‘Pay Premium’ option.

Step 3: Enter your policy number and date of birth, and then click on the ‘Submit’ button.

Step 4: Details of your policy will appear on the screen.

Step 5: Make the payment of premium through your credit or debit card.

Download of premium receipt of SBI life insurance is easy and important process for all those who wish to have hassle free tax filing, policy check and claims settlement in future. Through SBI Smart Care website, you can easily download premium receipt in few minutes.

LIC Policy Surrender Value 2026: Easy Calculation Guide

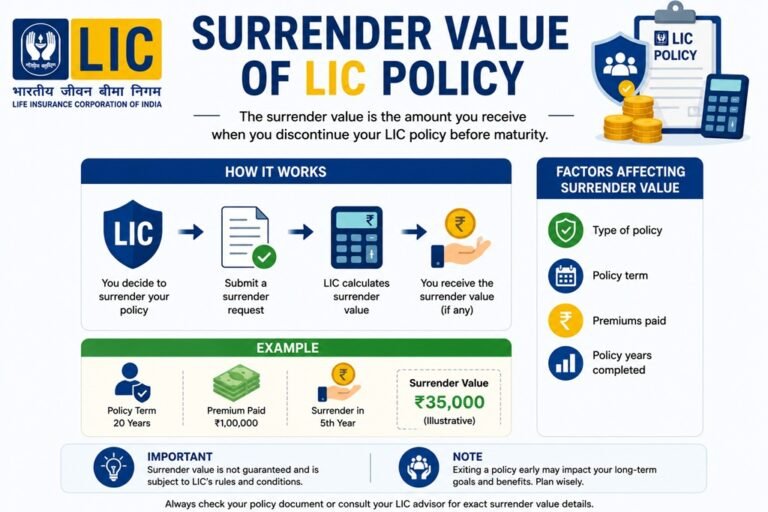
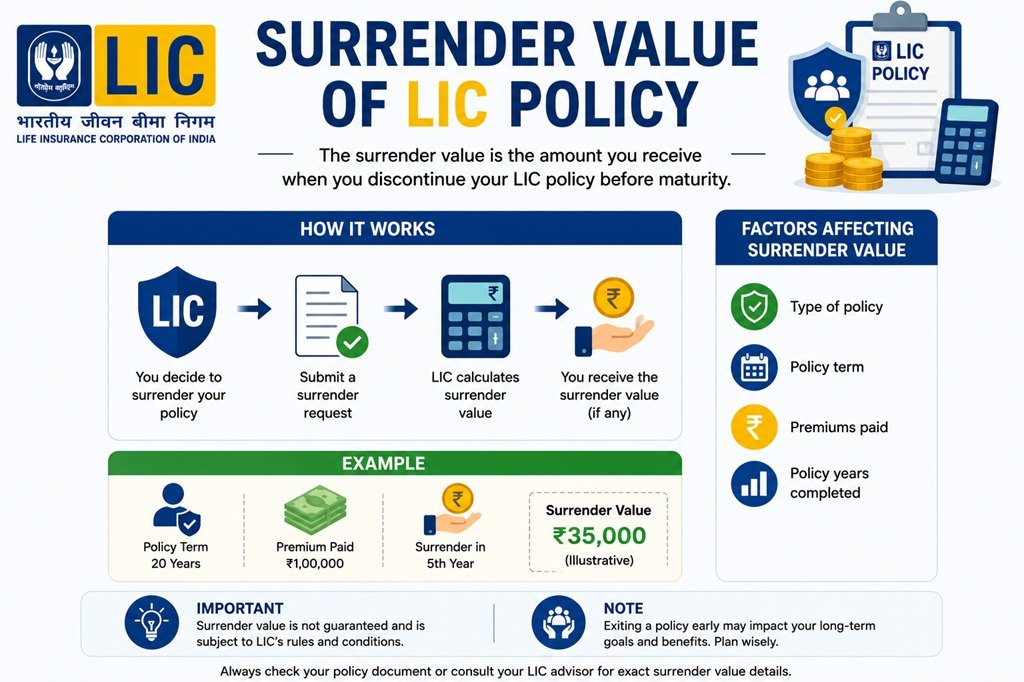
Surrender Value of LIC Policy means when you surrender LIC policy prematurely amount paid by LIC to you. The surrender of LIC policy may be due to an urgent need of money, such as a medical emergency, job loss, business loss, or anything.

Most of the people think that surrender value means whatever premium you have paid will be returned by LIC, but it is not the case. Surrender value is something else, and surrender value depends on total premium paid and the policy type. In this guide, I will explain what the surrender value of an LIC policy is and how to calculate it.
Surrender Value of LIC Policy

What Is the Surrender Value of LIC Policy?

The Surrender Value of LIC Policy is the amount of money LIC (Life Insurance Corporation of India) pays you if you decide to exit your policy before its maturity date. Think of it as a refund — but not a full one.

You must remember that you can not surrender all LIC policies. Only money back plans, endowment plans and whole-life plans can be surrendered. Term insurance policies, since they’re purely protective, don’t accumulate any cash value and hence have zero surrender value.

When Can You Actually Surrender a LIC Policy?

Great question! LIC has a simple rule here:

A policy becomes eligible for surrender only after the policyholder has paid premiums for at least 3 consecutive years.

So if you’ve been paying for, say, 2 years and you stop — you don’t get anything back. You’d lose your premiums entirely. But cross that 3-year mark, and the door opens.

In 2026, this rule remains unchanged. Whether your policy started in 2018 or 2022, the minimum 3-year paid-up requirement applies.

Two Types of Surrender Value You Must Know

This is where it gets a little interesting. The Surrender Value of LIC Policy is actually calculated in two different ways, and LIC pays you whichever amount is higher of the two. Here’s how they work:

  1. Guaranteed Surrender Value (GSV)

The Guaranteed Surrender Value is the baseline — it’s the minimum amount LIC is obligated to pay you. It’s pre-defined in your policy document and doesn’t change based on market conditions.

GSV Formula:

GSV = (Total Premiums Paid × GSV Factor%) + (Accrued Bonuses × Bonus GSV Factor%)

The GSV Factor is a percentage table that increases with policy duration. The longer you’ve held the policy, the higher the GSV factor — and the more money you get back. These factors are prescribed by the Insurance Regulatory and Development Authority of India (IRDAI).

A rough idea of GSV factors:

Policy Year GSV Factor (Approx.)
3rd Year 30%
4th–5th Year 50%
6th–7th Year 55%–60%
8th–9th Year 65%–70%
10th+ Year 70%–90%

So yeah — the earlier you surrender, the worse the deal for you.

  1. Special Surrender Value (SSV)

The Special Surrender Value is more dynamic. LIC calculates it based on the paid-up value of your policy and then applies a special surrender value factor.

SSV Formula:

Paid-Up Value = (Number of Premiums Paid ÷ Total Number of Premiums) × Sum Assured + Accrued Bonus

SSV = Paid-Up Value × SSV Factor%

The SSV factor, like the GSV factor, depends on the policy term and the number of years the policy has been in force. LIC periodically revises these factors, so in 2026, it’s worth checking the current table either on LIC’s official website or through your nearest LIC branch.

LIC pays you the higher of GSV or SSV. Always. That’s the rule.

How to Calculate Surrender Value of LIC Policy in 2026

Alright, let’s get practical! Here’s a clear, step-by-step process you can follow right now.

Step 1: Gather Your Policy Details

You’ll need:

  • Policy document (or e-policy from LIC portal)
  • Sum Assured amount
  • Policy term (total years)
  • Premium payment term
  • Number of years/premiums already paid
  • Accrued bonus (available in your policy statement or LIC portal)

Step 2: Calculate Total Premiums Paid

Simple math here:

Total Premiums Paid = Annual Premium × Number of Years Paid

Note: Don’t include the first year’s premium if it’s a regular premium policy, as LIC excludes it in some cases — check your policy terms.

Step 3: Find the Applicable GSV Factor

Look up the GSV factor table for your specific policy. The factor depends on:

  • The type of policy (endowment, money-back, whole life)
  • How many years you’ve paid premiums
  • The original policy term

If you can’t find the table, contact LIC’s helpline at 1800-227-717 (toll-free) or log in to the LIC portal at licindia.in.

Step 4: Calculate the Guaranteed Surrender Value

Plug your numbers into this formula:

GSV = (Total Premiums Paid × GSV Factor) + (Accrued Bonus × Bonus GSV Factor)

Step 5: Calculate the Special Surrender Value

First, find the paid-up value:

Paid-Up Value = (Premiums Paid ÷ Total Premiums Payable) × Sum Assured + Accrued Bonus

Then:

SSV = Paid-Up Value × SSV Factor

Step 6: Compare and Confirm

LIC will pay you whichever is higher — GSV or SSV. That’s your approximate surrender value.

A Practical Example — Let’s Make It Crystal Clear

Let’s say Ramesh has an LIC Jeevan Anand (Plan 915) policy with the following details:

  • Sum Assured: ₹5,00,000
  • Policy Term: 20 years
  • Premium Payment Term: 20 years
  • Annual Premium: ₹25,000
  • Years Premium Paid: 7 years
  • Accrued Bonus: ₹70,000

GSV Calculation:

  • Total Premiums Paid = ₹25,000 × 7 = ₹1,75,000
  • GSV Factor at 7th year ≈ 60%
  • Bonus GSV Factor ≈ 30%

GSV = (₹1,75,000 × 60%) + (₹70,000 × 30%) GSV = ₹1,05,000 + ₹21,000 = ₹1,26,000

SSV Calculation:

  • Paid-Up Value = (7/20) × ₹5,00,000 + ₹70,000 = ₹1,75,000 + ₹70,000 = ₹2,45,000
  • SSV Factor ≈ 60% (varies, let’s use this estimate)

SSV = ₹2,45,000 × 60% = ₹1,47,000

Since SSV (₹1,47,000) > GSV (₹1,26,000), LIC pays ₹1,47,000.

Of course, the actual amounts will depend on the exact GSV/SSV factor tables for that specific plan and year — but this gives you a solid ballpark!

Factors That Affect the Surrender Value of LIC Policy

Several things influence how much you’ll walk away with:

  • Policy duration: Longer you’ve paid, higher the surrender value. It’s as simple as that.
  • Type of policy: Endowment plans tend to have better surrender values than money-back plans.
  • Sum assured: A higher sum assured generally means a higher paid-up value and, consequently, a better SSV.
  • Accrued bonuses: LIC declares bonuses annually. More bonuses = more surrender value.
  • Policy status: Is your policy active (premiums being paid) or paid-up (you stopped paying)? Active policies usually yield better surrender values.
  • Loan outstanding: If you’ve taken a loan against your policy, that outstanding amount gets deducted from the surrender value.

What Happens to Your Bonus When You Surrender?

Ah, bonuses — the little gift inside every participating LIC plan! LIC declares reversionary bonuses each year, and these keep accumulating as long as your policy is active. When you surrender, LIC applies a bonus surrender factor — which is typically much lower than the face value of the bonus.

So don’t walk in expecting to get 100% of your accrued bonus. You’ll typically receive 30%–50% of it, depending on how long the policy has been running. Still, it adds up — and it’s money in your hand.

How to Apply for Surrender of LIC Policy in 2026

Ready to go ahead? Here’s the process:

  1. Visit your nearest LIC branch — bring your original policy bond, ID proof, address proof, cancelled cheque, and NEFT details.
  2. Fill out the Surrender Form (No. 5074) — available at the branch or downloadable from licindia.in.
  3. Submit all documents — the LIC officer will verify everything.
  4. Processing time — typically 7 to 10 working days.
  5. Amount credited — LIC directly transfers the surrender amount to your registered bank account via NEFT.

You can also initiate the process online via the LIC Customer Portal if your policy is digitally registered. It’s way more convenient than standing in line, honestly.

Should You Actually Surrender Your LIC Policy?

Look, here’s the truth — surrendering is usually not the best move unless you’re genuinely desperate. Here’s why:

  • You lose your life insurance cover permanently.
  • You lose the maturity benefit — which could be significantly higher than the surrender value.
  • The surrender value of LIC policy is always less than what you’d receive at maturity.
  • Bonus accumulation stops the moment you surrender.

Better alternatives to consider before surrendering:

  • Paid-up option: Stop paying premiums but keep the policy alive. You won’t earn new bonuses, but your life cover continues at a reduced level.
  • Policy loan: Borrow up to 90% of the surrender value without surrendering the policy. Interest rates are reasonable (typically 9–10% per annum in 2026).
  • Premium holiday: Some LIC plans allow temporary suspension of premiums.

That said, if you’ve held the policy for 15+ years and only a year or two remains until maturity — please don’t surrender! You’re so close to the finish line. Surrendering at that point would be like leaving a race with 200 meters to go.

Tax Implications of LIC Policy Surrender in 2026

Money received as the Surrender Value of LIC Policy is subject to income tax under certain conditions:

  • If the policy qualifies under Section 10(10D) of the Income Tax Act — meaning premiums paid were less than 10% of the sum assured — the surrender amount is tax-free.
  • If the premiums exceed that threshold, the surrender value becomes taxable as income under “Income from Other Sources.”
  • TDS (Tax Deducted at Source): LIC deducts 5% TDS if the surrender amount exceeds ₹1 lakh and the policy doesn’t meet Section 10(10D) conditions. However, if you submit a Form 15G or 15H, you may be exempt from TDS.

Always consult a tax advisor before surrendering — a little planning can save you a fair amount.

Common Mistakes People Make When Surrendering LIC Policies

Yikes! These are real slip-ups you’d want to avoid:

  1. Surrendering too early — surrendering in years 3–5 gives you back barely 30–50% of your premiums. That’s a significant loss.
  2. Not checking loan options first — many people surrender without realizing they could have simply taken a loan against the policy.
  3. Ignoring tax implications — getting hit with unexpected TDS or income tax is no fun.
  4. Not updating bank details — if your NEFT details are outdated, the credit gets stuck. Update them before applying.
  5. Surrendering close to maturity — as mentioned earlier, this is almost always a bad idea financially.

FAQs

Q1. What is the minimum period after which I can surrender my LIC policy?

You must have paid premiums for at least 3 consecutive years before your policy becomes eligible for surrender.

Q2. Will I get my full premium amount back when I surrender?

No, you won’t. The Surrender Value of LIC Policy is always less than the total premiums paid, especially in the early years. The longer you wait, the more you get back.

Q3. How do I check my LIC surrender value online?

Log in to licindia.in using your policy number and registered mobile number. Under the policy details section, you’ll find an option to view the current surrender value.

Q4. Is the surrender value of LIC policy taxable?

It depends. If your policy qualifies under Section 10(10D) of the Income Tax Act, it’s tax-free. Otherwise, it’s taxable as income, and LIC may deduct TDS.

Q5. Can I surrender a LIC term plan?

No. Term insurance policies have no savings component and therefore no surrender value. Only participating plans like endowment, money-back, and whole life policies can be surrendered for a cash value.

Q6. Does surrendering a policy affect my credit score?

No, surrendering a LIC policy does not impact your credit score in India. It’s simply a contractual termination between you and LIC.

Q7. What if I have a loan against my LIC policy and I want to surrender it?

LIC will deduct the outstanding loan amount (principal + interest) from your surrender value before crediting the balance to your account.

Q8. How is the surrender value of LIC policy different from paid-up value?

Surrender value is what you receive when you terminate the policy completely. Paid-up value is the reduced benefit you retain if you stop paying premiums but keep the policy alive without surrendering. Paid-up is the safer option if you want to retain some coverage.

Conclusion

I hope it is now clear that what the surrender value of LIC policy and how to calculate it. Before surrender of LIC policy, you must calculate surrender value and if required you must consult advisor and tax person to calculate your tax liabilities. Don’t take any finance decision blindly if required get in touch with LIC agent or LIC via free helpline, you can also visit LIC office if required.